Golar LNG Faces A Transition Quarter As Investors Await A Charter For FLNG Unit 4
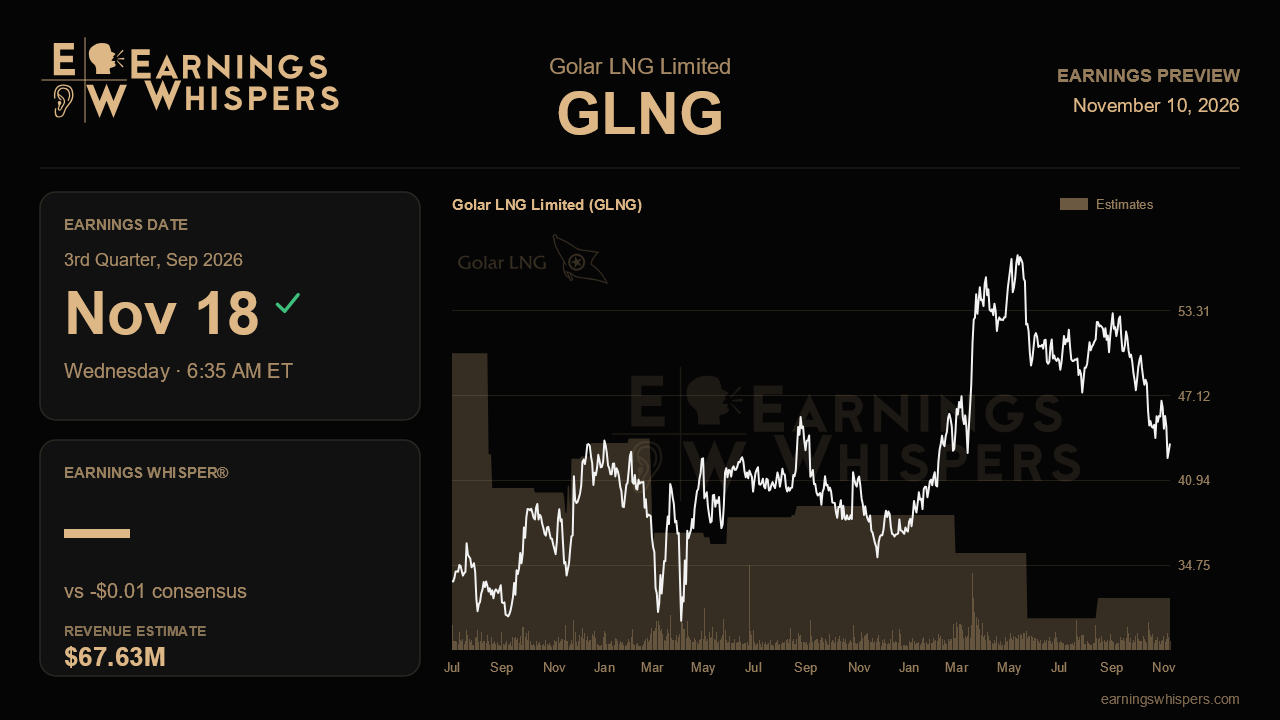
Three months ago Golar LNG gave investors what they had been waiting for. It placed a firm order for a fourth floating liquefaction vessel, laid out a path to more than $1.2 billion of run-rate EBITDA by 2030, and sounded more confident than at any point in the past year. Since then the stock has fallen about 21%, trailing the S&P 500 by roughly 18 percentage points. The third-quarter report, due before the open on November 18, arrives with the company's long-term story at its most ambitious and its near-term numbers at their weakest.
The Street expects a loss of about a penny a share on revenue of roughly $67.6 million. That compares with earnings of $0.43 a share and revenue of $122.5 million a year ago, and with $0.68 and $130.5 million last quarter. Revenue is forecast to fall about 45% from a year earlier. The likely reason is timing rather than a weaker business. Hilli finished its eight-year Cameroon contract with full economic uptime and is in transit to Argentina, where it is expected to generate about $285 million a year in EBITDA. A vessel at sea earns nothing. Last quarter it also contributed $37 million in commodity-linked earnings, so this quarter's gap is large. Management has not issued formal quarterly guidance, so the consensus figure mostly reflects analysts accounting for that idle period. A small loss is not a warning sign in itself. A loss larger than expected, or new costs tied to the relocation, would get more attention.
The operating questions matter more than the bottom line. First is Hilli's schedule. Investors need confirmation that it is on track to arrive and begin producing in Argentina, because that start-up anchors the roughly $800 million base EBITDA target for 2028 that management has repeated on every call. Second is Gimi. Its output above nameplate capacity eased to about 15% in the second quarter from 19% in the first, which management described as seasonal. If performance holds near those levels, that explanation stands up. A further drop would raise the question of whether the earlier gains were a high-water mark.
The biggest test is unit 4. Management said charter talks were advanced, with national oil companies, independents and majors all involved, and with several bidders for the remaining offtake under the commercial agreement. Until a charter is signed, the jump from $800 million to more than $1.2 billion depends on that deal. A signed charter on terms similar to Esperanza's would back up last quarter's optimism. Silence would not break the story, but it would leave a $2.45 billion commitment uncontracted. That budget is already about 10% above Esperanza's because equipment such as turbines and cold boxes has become more expensive amid competition from data centers and shipbuilders. Investors will want any update on cost pressure, the payment schedule, and how the roughly $1.5 billion in available liquidity covers the build. They will also want news on the option for a fifth unit and the shipyard letter of intent, both still early-stage. The strategic review launched late last year also remains unresolved.
Sentiment has cooled noticeably, with bullish readings slipping to 4% from about 19% before the last report. The stock trades below its 200-day moving average near $49.53. At $43.63 it sits within about 3% of its post-earnings low of $42.48, well below the $55.50 high reached after the last report. In other words, the market is paying little for the growth pipeline.
That sets a modest bar for the quarterly figures and a high one for proof of progress. If Golar shows Hilli moving on schedule, Gimi running steadily and real momentum on a unit 4 charter, the gap between its stated earnings capacity and its share price becomes hard to ignore. If the charter remains open and costs keep rising, investors may keep treating the $1.2 billion target as a promise rather than a plan.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Oct-23 | |
| Oct-23 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 | |
| Sep-24 | |
| Sep-21 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 |
