Golar LNG Hits Its Hilli-Gap Earnings Trough While Lining Up $1.6 Billion To Finance An FLNG Build-Out
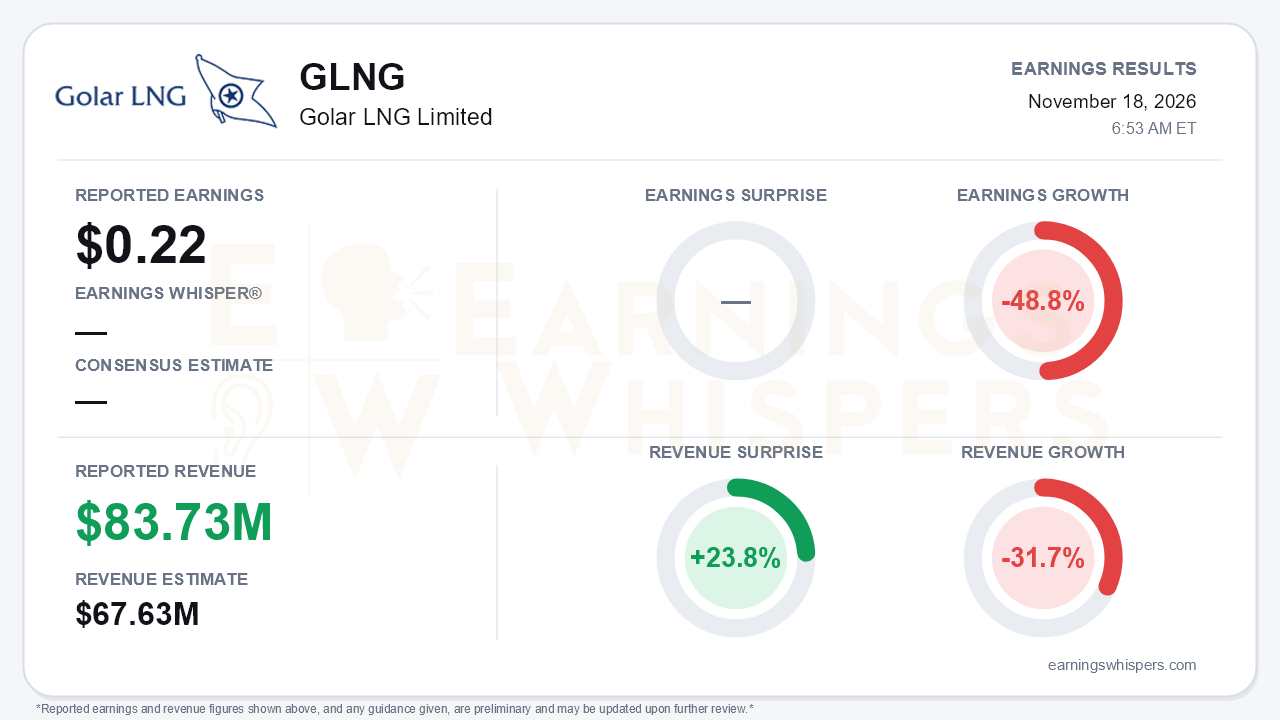
Golar LNG's third quarter was the earnings air pocket investors knew was coming, and it arrived in full. The company reported earnings of $0.22 per share, down 48.8% from a year ago, on revenue of $83.73 million, down 31.7%. Revenue still beat the $67.63 million consensus by 23.8%, but no EPS consensus was available to measure the bottom line against. The more useful comparison is sequential. Revenue fell from roughly $130 million in Q2 and $138 million in Q1. Adjusted EBITDA dropped to $56 million from $127 million. FLNG Hilli offloaded her 156th and final Cameroon cargo in July and will produce nothing until her Argentine contract starts in the second half of 2027. That is the central tension: the income statement has entered a roughly year-long trough, while the balance sheet and project pipeline moved meaningfully forward.
The quality of the reported profit deserves scrutiny. Net income attributable to Golar was $22.6 million, and $12 million of that came from non-cash items. Those items were mainly $20 million of mark-to-market interest rate swap gains, partly offset by the realization of Hilli's remaining oil and gas derivative assets. Hilli's commodity-linked contribution is also gone. Realized derivative gains of $37.4 million in Q2 swung to a small realized loss of $0.3 million. FLNG segment Adjusted EBITDA fell to $64.9 million from $136.3 million, and liquefaction services revenue shrank to $15.7 million from $55.6 million. Meanwhile, Golar's share of adjusted interest expense held near $42 million per quarter, up from $33 million a year ago. That reflects the cost of carrying roughly $1.9 billion of assets under development that do not yet earn anything.
FLNG Gimi was supposed to cushion the gap, but the third quarter was its weakest of the year. Quarterly overproduction slid to about 3%, from 15% in Q2 and 19% in Q1, which management attributed to summer ambient temperatures and scheduled maintenance. The year-to-date invoiced premium over the contractual day rate fell from 17% to 12%. The call nonetheless firmed up the outlook. Management guided to a sustainable 10-15% overproduction run-rate, plus 1-3% of low-capex debottlenecking upside. That is more concrete than the earlier promise of production "meaningfully above" contract, and management expects the premium to rebuild as temperatures cool late in Q4.
The forward story is where the quarter earned its keep. Golar added $1.6 billion of new financing capacity:
- a $600 million revolving credit facility secured on FLNG Esperanza, currently undrawn;
- a $500 million 7.5% senior unsecured bond;
- an amended Hilli sale-leaseback of up to $960 million, extended to 2038 at a lower margin, which should release about $472 million in December.
Together these lift available liquidity to roughly $2.27 billion, up from about $1.5 billion last quarter. Golar also took a final investment decision on FLNG four, bought the donor vessel Grace Dahlia, and reserved long-lead items for a potential fifth unit. Both Hilli's refurbishment and Esperanza's conversion remain on schedule and on budget. Management reiterated its long-term targets: about $800 million of run-rate EBITDA, and more than $1.2 billion including FLNG four. SESA expects to bring total Argentine offtake to around 5 MTPA in the new year, with the call citing more than 25 interested buyers.
Bears still have legitimate ammunition:
- **FLNG four is uncontracted.** It remains without a charter despite "advanced discussions" cited last quarter. The release explicitly warns of potential losses on long-lead items, milestone payments and the donor vessel if no contract materializes.
- **Costs are rising.** FLNG four's $2.45 billion budget sits above Esperanza's roughly $2.2 billion, and management flagged competition with AI data centers for long-lead equipment.
- **Esperanza's long-term debt is pending.** The larger facility to replace the revolver is not expected to close until 2027.
- **The strategic review got no update.** It remains listed among the company's risk factors.
The market had already turned skeptical. Shares opened at $55.27 after the August report, which marked the inter-earnings high, and closed at $41.94 the day before this release. That is a 24.1% decline. The stock sits 15.4% below its $49.60 200-day moving average and just 2.9% above a quarter low set on November 17. Investor sentiment swung from modestly positive (0.19) to modestly negative (-0.17), a meaningful shift in expectations. Price and AVWAP trend readings remain negative. In other words, the stock entered the report near the bottom of its range with expectations reset lower.
The bottom line is that Golar delivered a revenue beat inside an intentionally hollow quarter. Roughly half of attributable earnings were non-cash, and Gimi's seasonal softness exposed how thin the earnings base is until Hilli restarts in 2027. What changed is the funding picture: $2.27 billion of liquidity substantially de-risks the build-out, and management's long-term EBITDA targets are intact. The stock's next leg likely hinges less on near-term EPS than on converting FLNG four's "advanced discussions" into a signed charter.
Read our earnings preview for Golar LNG Limited: https://www.earningswhispers.com/article/GLNG/23124
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-10 | |
| Oct-23 | |
| Oct-23 | |
| Oct-19 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-01 | |
| Sep-24 | |
| Sep-21 | |
| Aug-13 |
