Pony AI's Robotaxi Surge Faces A Skeptical Market As Cash Burn And Uber Europe Come Into Focus
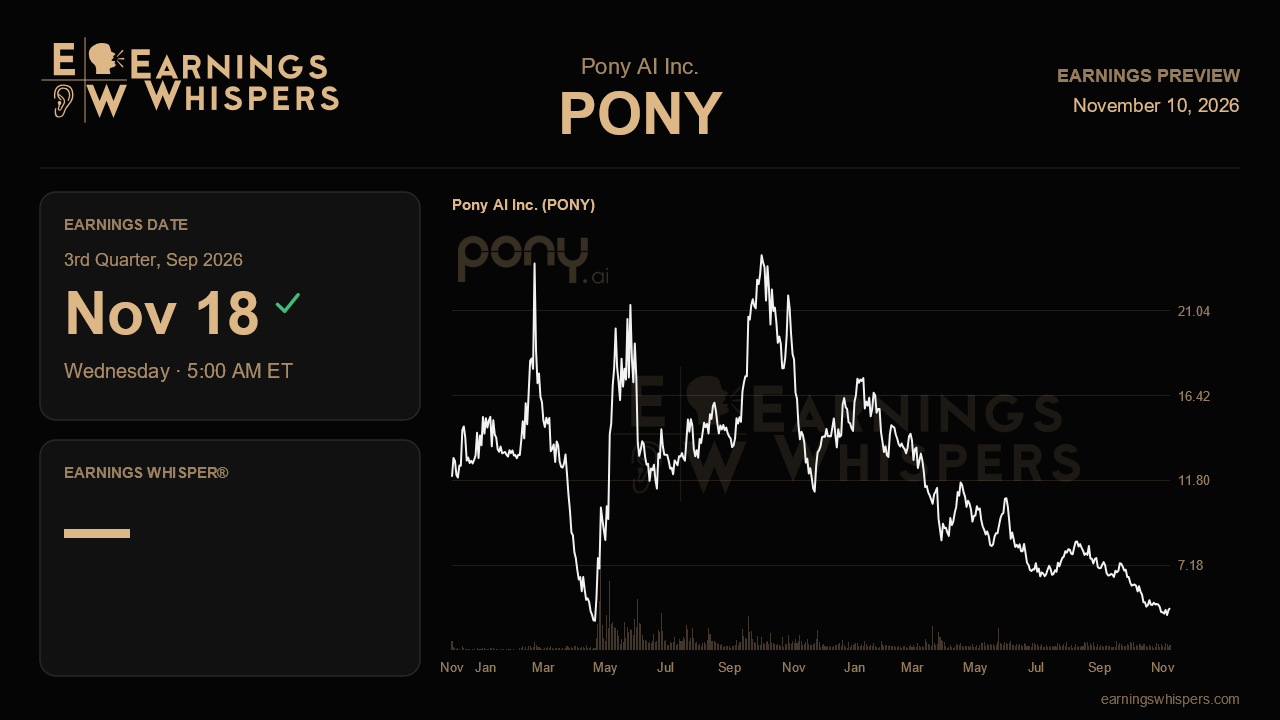
Pony AI heads into its third-quarter report with a striking disconnect. Last quarter management described a business firing on nearly every cylinder: robotaxi revenue up roughly sevenfold, a fleet on its way to 3,500 vehicles, and a marquee European deal with Uber. Since then the stock has fallen about 36%, trailing the S&P 500 by more than 33 percentage points. The November 18 release, due before the open, has to show whether the market priced in a real problem or simply lost patience with a company still burning cash to build scale.
Usable Street forecasts for the quarter are scarce, so the year-ago figures are the most practical yardstick. Pony lost $0.16 a share on $25.4 million of revenue in the September 2025 quarter. Last quarter it reported $36.2 million of revenue and a loss of $0.13 a share. Simply holding revenue near last quarter's level would put year-over-year growth above 40%, but the narrative management has built calls for more than that. The company has steadily raised its full-year robotaxi revenue goal, from a tripling to more than 3.5 times last year's level, and last quarter said it was confident of beating even that. A raise trajectory like this sets a higher bar. Another record robotaxi quarter, ideally with growth still accelerating from the 691% pace in the second quarter, is close to the minimum needed to keep the story credible.
The fleet count is the most concrete check. Pony had 2,000 vehicles on the road at mid-year against a year-end target of more than 3,500, which implies a heavy second-half build. A third-quarter total well above 2,000 would confirm that the inventory buildup and the $32.2 million of second-quarter capital spending are turning into revenue-generating cars. Updates on the Uber agreement covering more than 2,000 robotaxis in five European cities, the public launch in Singapore with ComfortDelGro, and the mix of partner-funded fleets under the joint deployment model will show whether overseas expansion is moving from announcements to operations. Investors should also look closely at how much revenue comes from upfront vehicle deliveries to partners versus recurring fare income, since the recurring stream is what supports the long-term margin argument.
Two soft spots from last quarter deserve attention. Intelligent Solutions growth fell from 246% to just 4% because of uneven domain controller deliveries. A rebound would support management's view that this was a timing issue, while a second weak quarter would suggest the segment's earlier strength was more one-off than structural. Cash consumption is the bigger question. Operating cash outflow nearly doubled year over year to $44 million, and the balance sheet slipped to $1.39 billion. That cushion is ample, but the operating leverage story, with an operating margin that improved more than 100 points to negative 181.5%, needs to keep progressing as the fleet expands. Robotruck momentum, helped by Gen 4 trucks entering mass production and the CATL-built light truck with SF Express and China Post, offers a secondary source of upside.
Sentiment has shifted sharply. Bearish readings have grown from almost none before the last report to a substantial share now, and the stock trades near $4.85, well below its 200-day moving average of $8.95 and only modestly above its post-earnings low of $4.27. The entire trading range has moved lower from last quarter's $6.37 to $11.28 band. That pessimism lowers the bar in one sense, but it also signals that a merely solid report may not change the stock's direction.
The central issue is whether Pony can show that rapid fleet growth translates into robotaxi revenue at a pace that justifies the rising cash burn. If the fleet build, the beat on the robotaxi target and continued margin improvement all hold up, the gap between operations and the share price becomes hard to ignore. If those signals weaken, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Oct-23 | |
| Oct-20 | |
| Sep-25 | |
| Sep-17 | |
| Sep-14 | |
| Sep-10 | |
| Aug-26 | |
| Aug-26 | |
| Aug-21 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 |
