Pony AI's Q3: Revenue Growth Accelerates And Operating Losses Narrow, But GAAP Loss Widens And Stalled Guidance Leaves Shares Near Lows
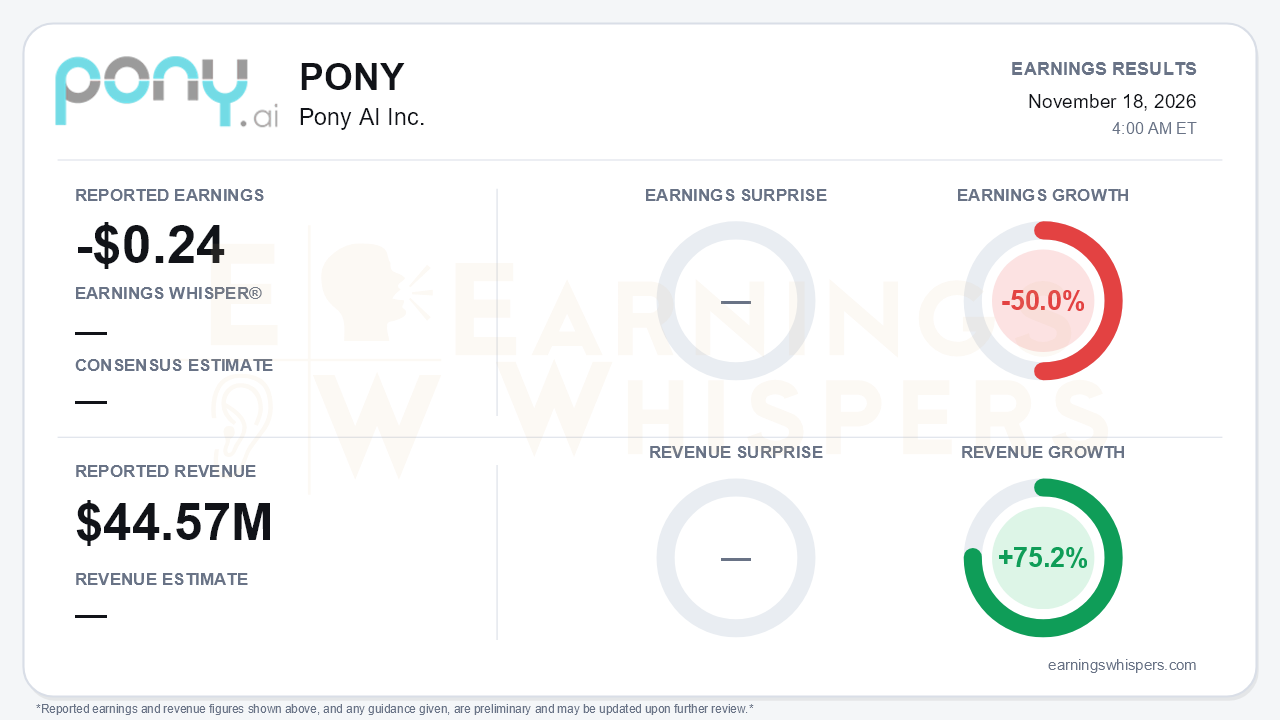
Pony AI delivered the operating quarter its bulls needed, but not the reported earnings they would have wanted. Revenue rose 75.2% year over year to $44.57 million, faster than the 69% pace in the second quarter. The GAAP loss widened to $0.24 per share from $0.16 a year earlier, a 50.0% decline in earnings. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory. That trajectory is mostly improving. The central tension is that better unit economics and accelerating revenue arrived alongside a headline loss inflated by investment marks, a full-year outlook that was only reaffirmed, and a stock that had already been cut nearly in half.
The widening GAAP loss deserves context rather than alarm. Net loss rose to $136.3 million from $61.6 million. Most of that increase came from a $77.0 million fair-value loss on trading securities, not from the core business. Loss from operations actually narrowed slightly to $68.7 million from $69.7 million. The non-GAAP picture is cleaner:
- Non-GAAP loss per share improved to $0.11 from $0.15.
- Non-GAAP net loss narrowed to $48.9 million from $56.8 million.
- Non-GAAP operating expenses fell 2.3% even as revenue nearly doubled.
The operating loss margin compressed to 154.2% from 273.9% a year ago and from roughly 181.5% in the second quarter. Gross margin of 17.8% was slightly below last year's 18.4%, but it has climbed sequentially from 16.2% in Q1 and 17.5% in Q2. Operating leverage is real. Gross margin expansion is still incremental.
Beneath the headline, the revenue mix is shifting in Pony's favor.
- **Robotaxi:** Services revenue hit a record $17.8 million, up 165.4% year over year and about 47% sequentially. It now represents roughly 40% of sales, versus 26% a year ago. Fare-charging revenue grew nearly 400%, which matters more than vehicle deliveries because it reflects recurring ride demand.
- **Robotruck:** This is the quiet standout. Revenue accelerated to 76.3% growth ($18.0 million) from 40% in Q2 and 31% in Q1, helped by Sinotrans freight volumes.
- **Intelligent solutions:** This is the soft spot. Revenue was flat at $8.9 million, down sequentially from $10.8 million in Q2 and $15.5 million in Q1.
Robotaxi's year-over-year growth rate also slowed sharply from 691% in Q2. That reflects tougher comparisons rather than weaker demand, but it removes a headline growth figure that had flattered prior quarters.
The catalyst list grew meaningfully. Guangzhou now operates a contiguous driverless zone exceeding 1,000 square kilometers. Pony also received new Shanghai Pudong permits and began deployments in Hangzhou, Chongqing and Zhuhai. Overseas, Zagreb produced Europe's first fully driverless passenger test rides, road testing is underway in Manchester, and a memorandum of understanding with inDrive and NVIDIA opens a potential Kazakhstan entry. In trucking, the new Gen-4 heavy-duty model with GAC entered the lineup, and management is targeting hundreds of port trucks in 2027. Gen-7 insurance premiums fell to about 40% of human-driven taxi levels from roughly 50%, a tangible signal that the safety record is improving unit economics.
The risks are equally concrete. Guidance momentum has stalled. Management upgraded targets in Q1 and spoke of beating them in Q2, but this quarter's language was only "on track" for:
- 3.5 times 2025 Robotaxi revenue;
- 3,500 vehicles;
- 20 cities.
No quantitative 2027 outlook was offered. The fleet stood at 2,768 vehicles at quarter-end, according to the release, which means hitting the fleet target requires roughly 730 to 800 fourth-quarter additions. Capital expenditures fell to $17.7 million from $32.2 million in Q2. Management framed that as disciplined pacing, but it sits awkwardly beside a steep year-end ramp. Liquidity slipped to $1.15 billion from $1.21 billion on a comparable basis, with free cash outflow of $78.2 million in the quarter. Analysts also raised U.S. chip export restrictions and intensifying European competition, notably in London.
The market setup is harsher than the fundamentals. Shares fell 47.0% from the $7.53 open after the August report to $3.99. That leaves the stock about 53.7% below its 200-day moving average and just 5.6% above a 52-week low of $3.78 set the day before this release. The stock peaked at $8.33 within days of the last report and has bled steadily since. Investor sentiment deteriorated meaningfully, sliding from roughly neutral at -0.02 to -0.29. The Earnings Whispers trend readings lean negative, with only momentum showing a positive tilt. Investors entered this report expecting disappointment, not acceleration.
The bottom line is that Pony AI's third quarter showed a business scaling with improving leverage. Accelerating total and Robotruck growth, a richer Robotaxi mix and a narrowing non-GAAP loss all point the right way. The GAAP loss widened mainly because of investment marks, not operating deterioration. Still, reaffirmed rather than raised targets, a demanding Q4 fleet ramp, flat intelligent solutions and steady cash burn give skeptics legitimate ammunition. With shares near lows and sentiment sour, execution on the year-end targets matters more than any single quarter's growth rate.
Read our earnings preview for Pony AI Inc.: https://www.earningswhispers.com/article/PONY/23128
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| 9 hours | |
| 11 hours | |
| Nov-15 | |
| Nov-10 | |
| Oct-23 | |
| Oct-20 | |
| Sep-25 | |
| Sep-17 | |
| Sep-14 | |
| Sep-10 | |
| Aug-26 | |
| Aug-26 | |
| Aug-21 |
