JOYY's Q3 Test: Can Revenue Acceleration Outrun Margin Dilution And FX Drag?
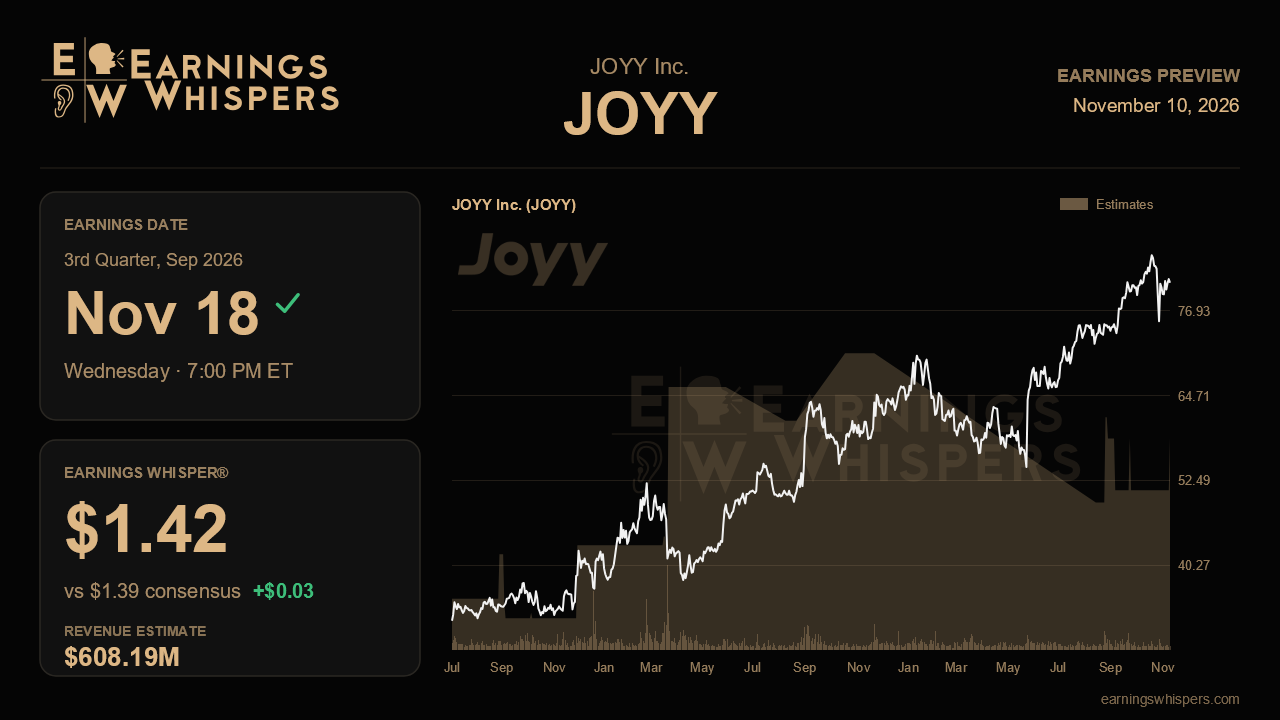
JOYY enters its third-quarter report with a story that finally has momentum behind it. Last quarter, revenue growth sped up for the third straight period, all three businesses accelerated, and management lifted its full-year non-GAAP operating income target to roughly 20% growth from a prior framing in the teens. The question for the November 18 report, due after the close, is whether that upgrade reflects a durable shift in earning power or whether faster growth from lower-margin businesses and a stubborn currency headwind keep profits from keeping pace with sales.
Wall Street expects non-GAAP earnings of $1.39 per share on revenue of $608.2 million, which would be roughly 20% top-line growth from the year-ago $507.8 million. That is a step up from the 16.3% pace delivered in the second quarter, so the Street is effectively betting on another acceleration. The earnings target implies about 13% growth from $1.23 a year ago, a noticeably slower clip than revenue, which tells you analysts are already baking in margin pressure. The Earnings Whisper of $1.42 sits only modestly above consensus, signaling a slightly higher bar but not an aggressive one.
Management's own outlook frames the revenue debate. JOYY guided to $602 million to $622 million, and consensus has drifted up from about $601.7 million when the range was issued to a figure that still sits in the lower half of it. That positioning matters. A company that just raised its profit outlook and saw every segment speed up has room to land near the midpoint or above, and a print in the low $600 millions would look like a stall rather than a beat.
The segment details will decide whether the multi-engine narrative holds. Beagle Ads grew 53% last quarter, but its third-party Audience Network has been decelerating on a big base, from about 83% to 79% to 74% over three quarters. Another gentle step down would be fine; a sharp drop would undercut the ads engine carrying the growth story. ShopLine accelerated to nearly 29% growth and saw its full-year target raised to above 20%, so sustaining something close to that pace would validate the upgrade, while early evidence that AI-channel traffic from integrations with tools like ChatGPT and Claude is converting into merchant revenue would give the new catalyst substance. In live streaming, the return to year-over-year growth of about 7% needs to persist, with voice products and AI-driven virtual gifts helping show the core franchise is stabilizing rather than enjoying a temporary bounce.
Margins are the main swing factor. Gross margin slipped to 34.1% from the mid-35% range as ad network and ShopLine payments and marketing services grew faster than the rest of the business. Further erosion is expected; the issue is whether operating leverage offsets it enough to keep the 20% operating income target credible. Below the operating line, management warned that unrealized foreign exchange losses from a weaker dollar, about $14 million last quarter, would likely continue, which could muddy net income even if operations perform. Capital returns, already $359 million through mid-year under a $1.5 billion program, provide per-share support.
The market has leaned in. Shares are up 6.3% since the last report while the S&P 500 fell 1.9%, and at $80.96 the stock sits well above its 200-day average of $68.68, in the upper part of a post-earnings range of $72.06 to $85.15 that sits wholly above last quarter's band. Sentiment has improved modestly to 10.2% bullish from 7.1%. Expectations are firmer but not euphoric. Ultimately, this report hinges on whether accelerating revenue converts into operating profit growth near 20% despite mix dilution; if it does, the raised outlook looks conservative, and if margins slip faster than sales climb, the rerating could pause.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-06 | |
| Nov-02 | |
| Oct-13 | |
| Sep-02 | |
| Aug-26 | |
| Aug-25 | |
| Aug-25 | |
| Aug-14 | |
| Jul-01 | |
| Jun-30 | |
| Jun-17 | |
| May-25 | |
| May-25 | |
| May-15 |
