JOYY Beats On Revenue But Misses On EPS As Ad Growth Cools And Costs Climb
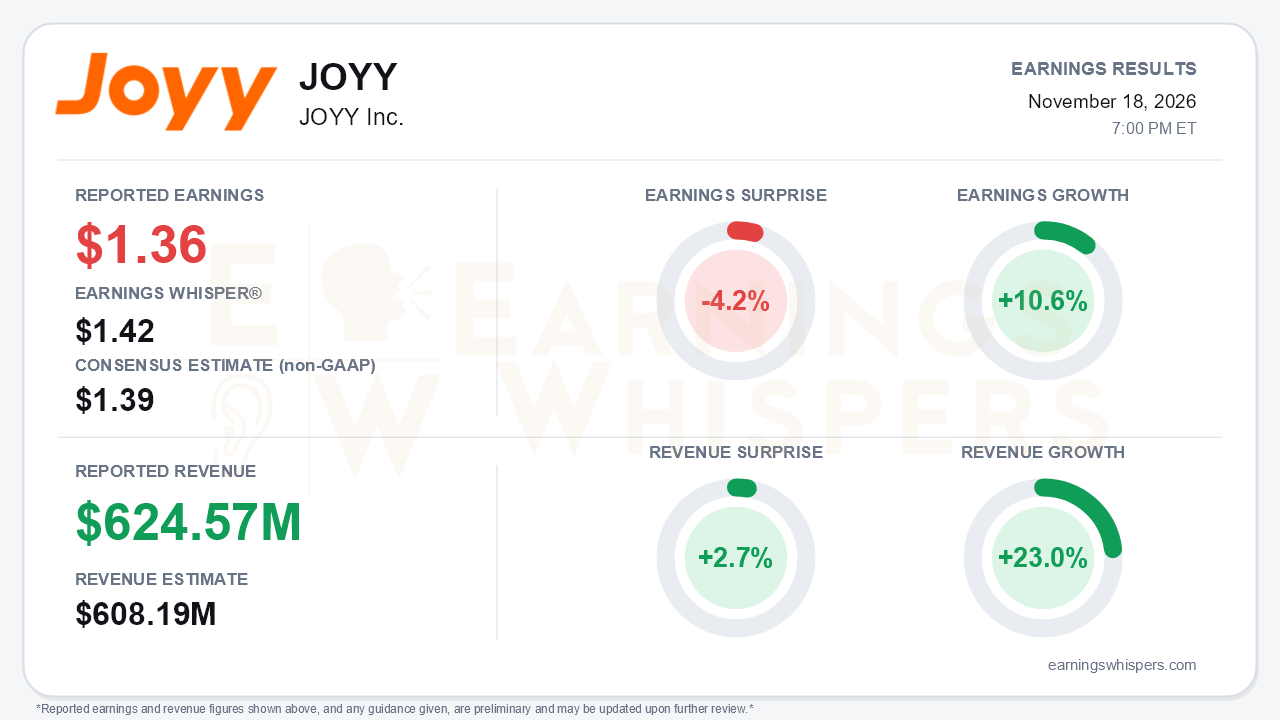
JOYY delivered the split quarter its diversification story has been at risk of producing: the top line outran expectations, but too little of it reached the bottom line. Non-GAAP earnings of $1.36 per ADS missed the $1.39 consensus and the $1.42 Earnings Whisper number by 4.2%. Revenue of $624.57 million beat the $608.19 million consensus by 2.7% and cleared the top of management's own $602–622 million guide. Earnings Whispers' normalized figures show earnings up 10.6% and revenue up 23.0% year over year. The company's own comparisons are less flattering: reported revenue growth of 15.6%, and non-GAAP diluted EPS unchanged from $1.36 a year earlier. The difference reflects the comparison base used, but the company's figures reinforce the central tension: revenue is compounding while per-share profit is barely moving.
The quality of the miss deserves scrutiny. Gross profit rose to $217.2 million and gross margin improved sequentially to 34.8% from 34.1%, so the problem was not at the gross line. Operating expenses rose 17.2% year over year to $204.1 million, with G&A jumping to $58.4 million from $39.1 million. Share-based compensation and impairment charges drove much of that increase. GAAP operating income slipped to $13.5 million from $19.6 million a year ago. Non-GAAP operating margin was flat year over year at 7.5% and down from 8.3% in Q2. Below the line, net foreign-exchange losses of $9.0 million weighed on results again, and non-GAAP net income fell 7.4% year over year. Buybacks shrank the diluted ADS count by roughly 7.5%, and that is effectively what held per-share earnings level. GAAP diluted EPS of $1.20 was flattered by a $19.6 million equity-method contribution that the non-GAAP measure strips out.
The operating trends point in two directions. Social Entertainment, long treated as the ex-growth cash cow, accelerated to 8.8% growth from 7.4% in Q2 and 3.2% in Q1. Core paying users rose 8.1% versus 3.9% in Q2, with live-streaming growth in all four regions. AI-generated gifts reached 35.4% of gift consumption. The growth engines, by contrast, are cooling. BIGO Ads grew 39.6%, down from 53.1% and 55.6% in the prior two quarters. Bigo Audience Network slowed to 52.3% from 74.1% and 78.8%. BIGO Ads' cost of revenues rose 47.9% on higher traffic-acquisition costs, outpacing segment revenue. Shopline eased to 24.7% from 28.6%, and its gross margin compressed as lower-margin payments took a larger share of the mix.
Management's response was to lean on forward catalysts. It raised its full-year third-party advertising growth outlook to nearly 60% from roughly 50%, reaffirmed the $1 billion Bigo Audience Network target for 2028, and reaffirmed the roughly 20% non-GAAP operating income growth target. The October Google AdMob integration completes coverage of all three major mediation platforms, though management conceded its contribution is still early. Web-based ad demand surged about 328% year over year. Management also offered a first qualitative 2027 framing: solid revenue growth with expanding non-GAAP operating profit. The Q4 revenue guide of $650–669 million implies a sequential step-up, but it was characterized as in line. It also embeds slowing segment growth: mid-single digits for Social Entertainment and just over 20% for Shopline, the latter below the 25%-plus expected on the Q2 call. Bears have legitimate ammunition here, along with the absence of any quantitative 2027 targets.
Capital returns remain a real support. JOYY has returned $536 million year to date, $216.2 million in dividends and $319.8 million in buybacks, with $368.2 million left on the repurchase authorization. Operating cash flow jumped to $102.2 million. The pace of returns is drawing down the balance sheet, though: net cash fell to $2.94 billion from $3.26 billion at year-end.
Investor sentiment improved meaningfully into the report, rising from a barely positive 0.07 to 0.25. Expectations were firming even before the print. Shares were up 3.4% from the open following the August report and sat about 14% above the 200-day moving average. The ride was volatile: the stock hit a 52-week high of $85.15 on October 20, then dropped to $72.06 eight days later. Entering the report about 7.5% below that peak, the stock had already given back much of its autumn enthusiasm. The Earnings Whispers trend readings are mixed, with momentum positive but AVWAP negative.
The bottom line is that JOYY sold a credible growth narrative with a less convincing quarter. Re-accelerating live streaming, a raised ad outlook, and heavy buybacks keep the multi-engine story intact. However, the EPS miss, decelerating ad and Shopline growth, rising operating costs, and persistent FX drag show that operating leverage has yet to appear. Management is effectively asking investors to wait for 2027, and that promise now carries the weight of the investment case.
Read our earnings preview for JOYY Inc.: https://www.earningswhispers.com/article/JOYY/23137
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-18 | |
| Nov-18 | |
| Nov-18 | |
| Nov-10 | |
| Nov-06 | |
| Nov-02 | |
| Oct-13 | |
| Sep-02 | |
| Aug-26 | |
| Aug-25 | |
| Aug-25 | |
| Aug-14 | |
| Jul-01 | |
| Jun-30 | |
| Jun-17 |
