Woodward Closes A Record Year As Fading Tailwinds Put Its Fiscal 2027 Outlook On Trial
Woodward has raised its earnings outlook four quarters in a row, yet the stock has slipped since its last report while the broader market edged higher. That disconnect frames the fiscal fourth-quarter release. The company itself flagged the reasons for caution: pricing gains are normalizing, a lucrative China on-highway business has wound down, and a favorable industrial mix is set to reverse. The question is whether underlying aerospace and power-generation demand is strong enough to absorb those losses, both in this quarter and in the outlook for next year.
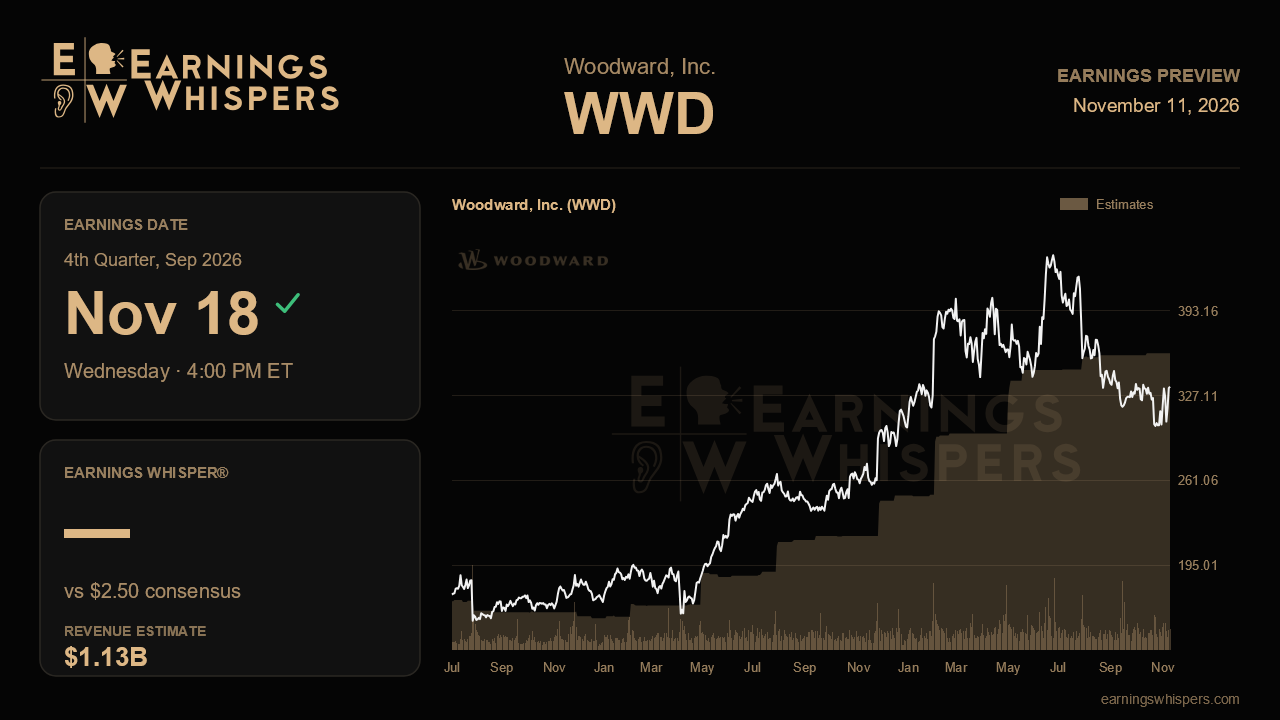
Wall Street expects earnings of $2.50 per share on revenue of about $1.13 billion, up 19.6% and 13.5% from a year ago. Those are healthy gains, but they mark a clear slowdown from the third quarter, when sales rose 21% and adjusted EPS jumped 43% to $2.52. Consensus implies a slight sequential dip in profit despite slightly higher revenue, which is consistent with management's warning about margin headwinds. The full-year consensus of $9.34 per share sits near the bottom of the raised $9.30 to $9.50 guidance range, and the $4.32 billion revenue estimate falls in the lower half of the $4.28 billion to $4.39 billion range. In other words, analysts have not fully trusted the latest raise, which leaves room for upside if the fourth quarter merely holds third-quarter profitability.
The last call offers a checklist. Industrial was the star, with segment margin reaching 22.1%, but roughly 90 basis points came from China on-highway sales that are now essentially gone, and favorable business mix is expected to flip. Management lifted the full-year industrial margin target to about 19%, which implies a meaningful step down in the fourth quarter. A result that lands near or above that level would suggest data center-driven power-generation demand, where several customers have raised forecasts, is filling the gap. In aerospace, margin hit 24% and the full-year target moved to the top of the range at roughly 23.5%. Commercial aftermarket growth has decelerated from 50% to 36% to 24% over three quarters, and spare part sales were guided to ease further. Steady shop demand across LEAP, GTF and legacy engines, plus the new Hayco service partnership in Asia, would validate the story. A sharper aftermarket slide or continued weakness in defense OEM, which fell 6% last quarter, would challenge it.
Cash is the quieter test. Free cash flow guidance stayed at $300 million to $350 million despite repeated EPS increases, held back by higher receivables and inventory, and capital spending must more than double in the fourth quarter to reach the roughly $290 million target. Missing the cash range or reporting further inventory growth would raise questions about earnings quality just as supply constraints in castings, forgings and rare earths are emerging.
Sentiment has cooled noticeably, falling to barely positive from a solidly bullish reading ahead of the last report. The stock, down 6.7% since then and trailing the S&P 500 by 8.6 points, trades near $334, well below its 200-day moving average of about $364 and far from the post-earnings high near $383. The entire trading range has shifted lower from the prior quarter's band of roughly $337 to $451, a sign that the market has been pricing in a peak in growth rates.
That makes the forward view decisive. Last year Woodward opened with a conservative fiscal 2026 range and then raised it repeatedly. If the initial fiscal 2027 outlook shows that price normalization and the loss of China sales can be offset by aerospace volume, power-generation strength and automation-driven efficiency, the recent selloff may look premature. If the guide signals that this year's margins were a high-water mark, the recent skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-28 | |
| Oct-16 | |
| Oct-16 | |
| Oct-07 | |
| Oct-04 | |
| Sep-21 | |
| Sep-16 | |
| Sep-14 | |
| Sep-14 | |
| Sep-14 | |
| Sep-02 | |
| Aug-19 | |
| Aug-10 | |
| Jul-30 |
