Woodward Beats Handily On A Record Year, But A 6%-10% Fiscal 2027 Outlook Signals A Shift From Hypergrowth To Heavy Investment
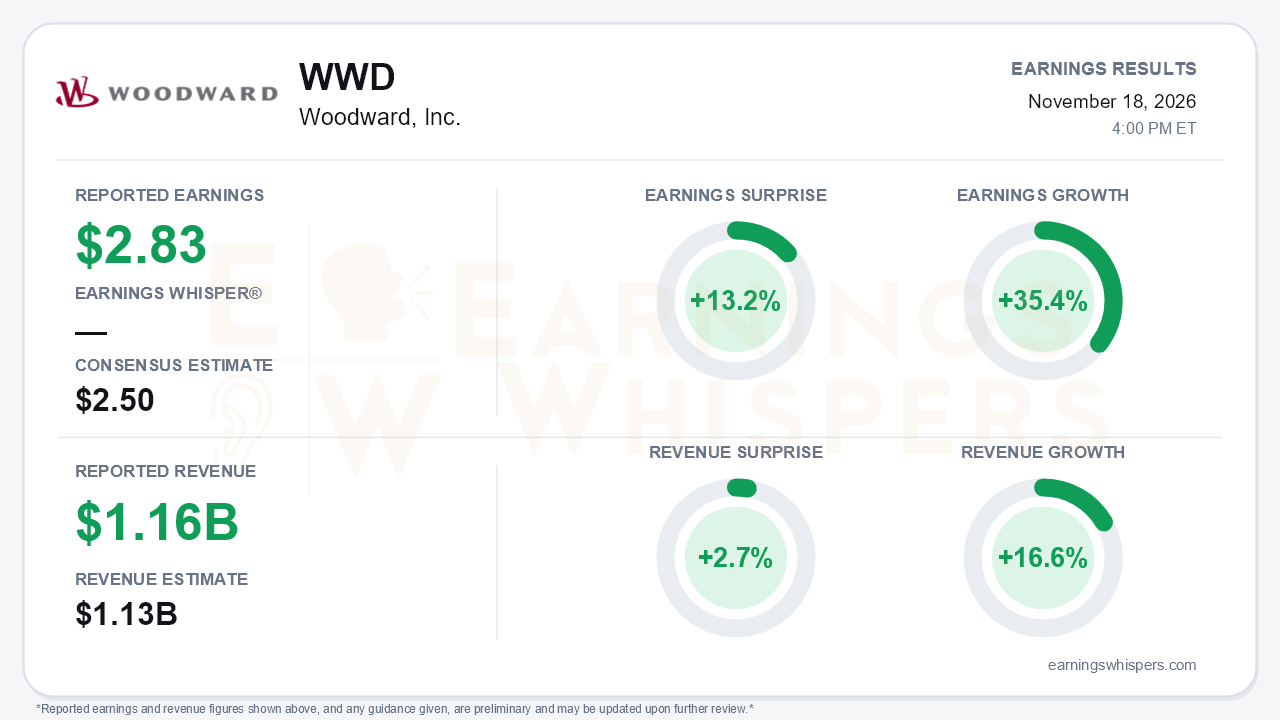
Woodward closed fiscal 2026 with another clear beat. Adjusted earnings of $2.83 per share topped the $2.50 consensus by 13.2% and grew 35.4% year over year. Revenue of $1.16 billion beat expectations by 2.7% and rose 16.6%. For the full year, adjusted EPS of $9.78 came in well above the $9.30-$9.50 range management set after its third quarter, and sales grew 22% to $4.4 billion. That range had already been raised from $8.20-$8.60 at the start of the year. The central tension is that the record year is now in the rearview mirror. Management's fiscal 2027 outlook calls for sales growth of only 6%-10% and adjusted EPS of $10.20-$10.70, which implies roughly 4%-9% earnings growth after a 42% year.
The deceleration did not begin with the guidance. Quarterly sales growth slowed steadily through fiscal 2026, from 29% in the first quarter to 23%, 21%, and finally 17% in the fourth. Beneath the headline beat, the mix of strength shifted. Aerospace grew sales 18%, driven by Commercial OEM (+26%) and Commercial Services (+25%), but segment margin was essentially flat at 24.3% versus 24.4%, and Defense Services fell 12%. Industrial did most of the incremental margin work. Segment earnings jumped 61%, and margin expanded 610 basis points to 20.7%, helped by an 18% gain in power generation tied to data-center demand. On a GAAP basis, EPS rose a more modest 23% to $2.74. The gap reflects $7.4 million of restructuring charges and a GAAP tax rate that rose to 22.5% from 13.9%, since the prior-year quarter benefited from a German tax-rate reduction.
Cash flow deserves scrutiny. Operating cash flow rose 26% in the quarter, but capital spending tripled to $163 million, so free cash flow fell 28% to $131 million. For the year, free cash flow slipped to $327 million from $340 million. Meanwhile, total debt roughly doubled to $1.42 billion, with leverage rising to 1.6x EBITDA, as Woodward repurchased $711 million of stock. The 2027 plan points to some relief. The release guides free cash flow to $400-$450 million on roughly $290 million of capex, although the call analysis noted that figure was not clearly reiterated. Net interest expense, however, is expected to rise to about $75 million from roughly $50 million, and capital return is guided down to about $675 million from $785 million.
The call made clear that fiscal 2027 is an investment year by design. Price realization normalizes to about 4% from roughly 8%. Industrial growth of 1%-5% absorbs a $110 million headwind from the China on-highway wind-down; excluding that, the segment is closer to 11%. Industrial margin is guided to 18.2%-18.7%, below both fiscal 2026's 19.6% and the roughly 21% core run-rate of the second half, reflecting investment spending and an OE-heavy data-center mix. Aerospace margin is still expected to expand to 23.8%-24.3% despite about 150 basis points of drag from footprint transitions. Those transitions include six work-transfer projects, two facility closures including Santa Clarita, and the Spartanburg opening, with a targeted benefit of roughly $50 million a year to aerospace margins starting in fiscal 2028. Spare LRUs and legacy CFM56/V2500 aftermarket demand are guided roughly flat, and management flagged that airlines could defer high-value LRUs if oil prices stay elevated.
The longer-term catalysts are credible. LEAP/GTF services sales surpassed legacy in fiscal 2026, hitting a milestone management had targeted for late 2026 to 2027. Prestwick MRO capacity is doubling, and the licensed elite repair partners, which should eventually lift spare piece-part sales, are about a year from full test capability. Airbus chose Woodward for the folding-wing demonstrator's complete actuation system, and a March 2027 Investor Day should set long-term targets. The execution risk is real, though. Complex work transfers, pending divestitures under HSR/CFIUS review, and NLRB matters at the Niles facility all sit on the critical path.
The market had already been pricing in fatigue. Shares fell 13.5% from the open after the July report to $309.74 ahead of this release, leaving them about 15% below the $364 200-day moving average. They sit roughly 19% below the August 6 inter-earnings high of $382.95 and only about 8% above the October 23 low. Investor sentiment remained positive but weakened sharply, sliding from 0.27 to 0.05, close to neutral. Trend readings are mixed: sequential growth and momentum remain positive, while price and AVWAP trends are negative.
The bottom line is that Woodward delivered a high-quality beat on the year it promised, but the investment setup has changed from a story of compounding margin surprises to one of a deliberate reset. Slower growth, normalizing pricing, and front-loaded footprint costs define 2027, with the payoff deferred to 2028. With shares well off their highs and sentiment cooling, the market appears to have anticipated some of this deceleration. The next leg likely depends on whether execution on the footprint plan and the aftermarket transition can make the fiscal 2028 targets look tangible.
Read our earnings preview for Woodward, Inc.: https://www.earningswhispers.com/article/WWD/23144
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 6 hours | |
| Nov-16 | |
| Nov-11 | |
| Oct-28 | |
| Oct-16 | |
| Oct-16 | |
| Oct-07 | |
| Oct-04 | |
| Sep-21 | |
| Sep-16 | |
| Sep-14 | |
| Sep-14 |
