LiveOne Must Prove Its Partnership Story Can Replace Last Quarter's One-Time EBITDA Boost
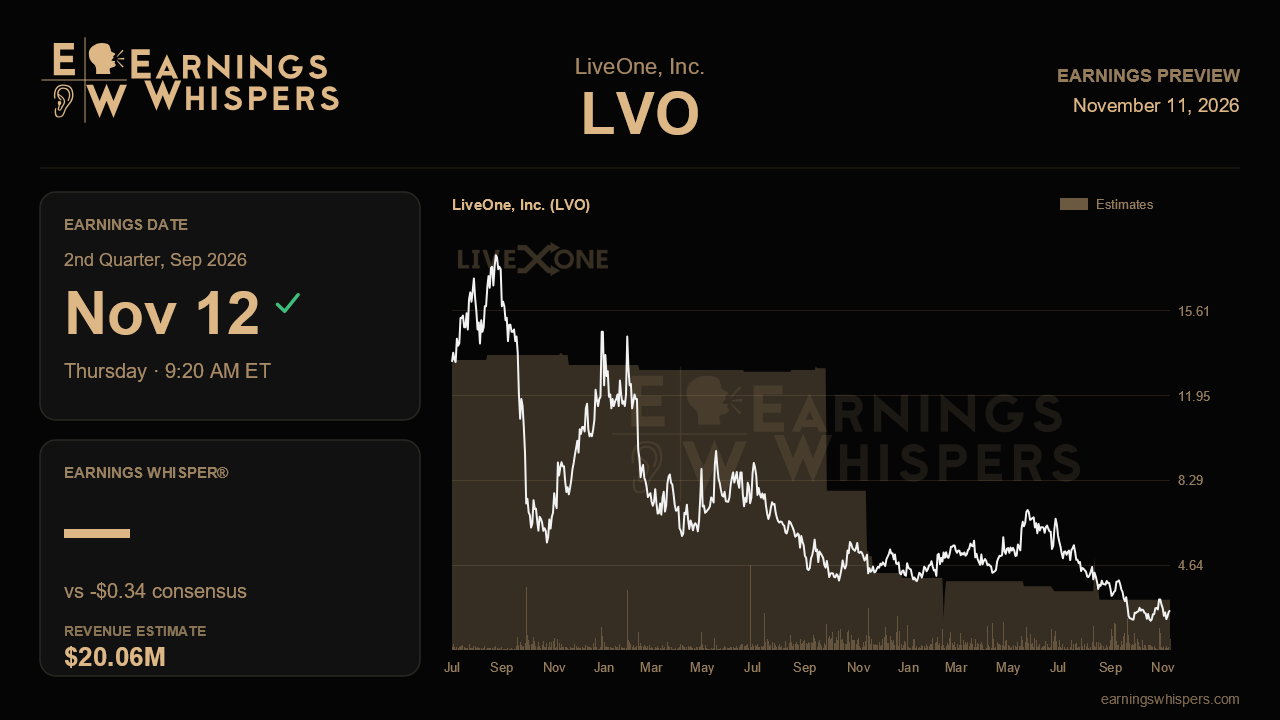
LiveOne heads into its fiscal second-quarter report with a credibility problem that a single quarter can either ease or deepen. Last time, the company posted what looked like record profitability and unveiled a parade of new partners, including Netflix, a major global retailer and a slate of AI companies. Underneath, much of that adjusted EBITDA came from non-recurring stock-for-service deals and a one-time liability write-off, while the specific annual revenue and EBITDA targets that management had repeated for two straight quarters quietly disappeared. The stock has since lost more than a third of its value, and this report is the first real chance to show whether the new catalysts carry weight on their own.
The Street is not asking for much on the top line. Consensus calls for revenue of about $20.1 million, up 6.9% from $18.8 million a year ago and only modestly above the $19.4 million reported last quarter. That is modest growth, not acceleration. On the bottom line, analysts expect a loss of $0.34 per share, which would be a sizable improvement from the $0.52 loss a year earlier but notably worse than last quarter's $0.23 loss. That sequential deterioration tells you the market has already absorbed the CFO's warning that margins revert to normal without more of the one-off deals that flattered the prior quarter. A higher share count from roughly $15 million in stock-for-service conversions also works against per-share results.
With no formal guidance on the table, the comparison investors will naturally make is against the abandoned $85 million to $95 million revenue target. Annualizing the consensus figure lands near $80 million, still short of the bottom of that old range. A revenue print meaningfully above $20 million, paired with commentary tying the gap to new partner revenue, would help restore some confidence. A number at or below consensus, with the conversation shifting again toward the three-year $250 million aspiration, would reinforce the impression that near-term targets are being traded for longer-dated promises.
The operating details matter more than the headline numbers. Management said AI content licensing, with discussions under way at 17 companies, would begin generating revenue this quarter. That is the most testable claim from the last call, and the first disclosed dollars would be meaningful validation after several quarters of the opportunity being described as imminent. Investors should also look for early contribution from the four-year retailer agreement and the Netflix podcast relationship, any update on whether Paramount and Amazon run-rates kept climbing, and evidence that PodcastOne is tracking toward its roughly $60 million run-rate. Slacker is the counterweight: its revenue has slipped every quarter, from $3.1 million to $2.5 million, and another decline would undercut the idea that the audio segment's improved margins are durable. Progress on the acquisition described as well in process would add a further catalyst, though a deal financed with more stock could reignite dilution concerns.
Sentiment has swung from firmly bearish ahead of the last report to mildly bullish now, even as the shares slid to $2.69, well below the 200-day moving average near $4.59 and beneath last quarter's $3.98 low. That combination suggests some investors see the selloff as overdone, but the chart reflects a market that has priced in skepticism. Notably, the recent stock conversions were struck at $7.50, nearly three times the current price.
The central question is simple: once the one-time items are stripped away, can LiveOne show recurring revenue from Netflix, the retailer and AI licensing that begins to fill the hole left by its dropped guidance? Tangible, quantified contributions would keep the turnaround narrative intact. Another quarter of unquantified partnerships and adjusted numbers would leave the story leaning on promises the market has already discounted.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 1 hour | |
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-04 | |
| Oct-12 | |
| Oct-05 | |
| Sep-22 | |
| Sep-17 | |
| Sep-02 | |
| Aug-12 | |
| Aug-12 | |
| Aug-04 | |
| Jun-24 |
