LiveOne Misses And Cuts FY2027 Revenue Guidance By About 20%, Making A Delayed Mega-Partnership The Whole Growth Story
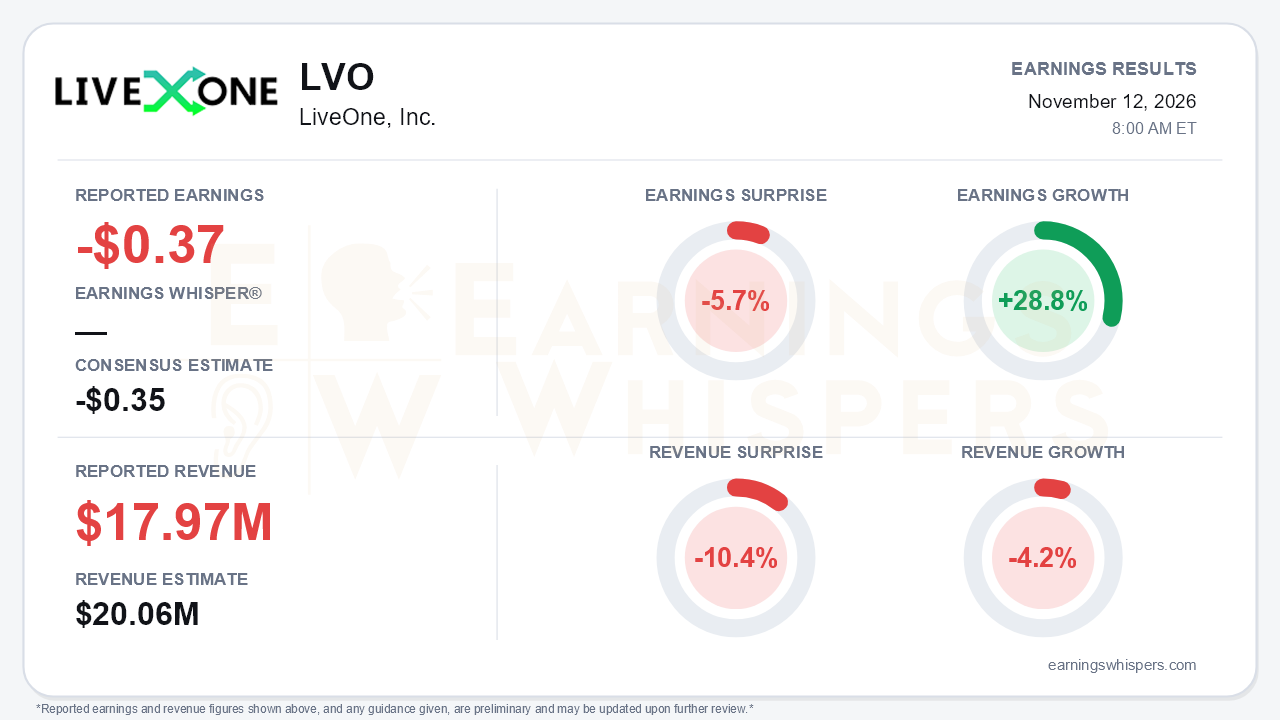
LiveOne (NASDAQ: LVO) reported a fiscal second-quarter loss of $0.37 per share on revenue of $17.97 million. Both figures missed: EPS came in 5.7% below the -$0.35 consensus, and revenue fell 10.4% short of the $20.06 million estimate. Earnings improved 28.8% year over year, but revenue declined 4.2%. The more consequential news was the outlook. Management cut fiscal 2027 revenue guidance to $70-75 million from the $85-95 million range it had repeated for several quarters, roughly a 20% reduction at the midpoint. It attributed the cut to delayed launch timelines at its B2B partners. That is the central tension. The near-term business is shrinking, and management is asking investors to look past it to a first-ever fiscal 2028 target of $100 million-plus that rests largely on a partnership that has not yet launched.
The quality of the quarter deserves scrutiny. The improvement in EPS is less impressive than the 28.8% growth figure suggests:
- **Losses barely moved.** The GAAP net loss was $5.6 million, versus $5.7 million a year ago.
- **Share count did much of the work.** Weighted shares rose to 13.7 million from 11.2 million, which spread a similar loss over more stock.
- **Interest costs rose.** Net interest expense climbed to $1.6 million from $1.0 million.
- **Adjusted EBITDA leans on add-backs.** It improved to a $0.7 million loss from a $1.0 million loss, but that result excluded $2.5 million of third-party stock-based compensation, a category that did not exist a year ago. For the first half, that add-back reached $8.7 million.
- **Gross profit fell.** It dropped to $1.7 million from $2.4 million, even though contribution margin edged up.
The balance sheet also warrants attention. The $13.7 million convertible note is now classified as current. Current liabilities of $49.4 million are well above $20.0 million of current assets, and payables increased to $32.9 million. The company still lists going-concern ability among its risk factors, even as it highlights $25 million of liabilities extinguished since February.
The first-half profitability figures are inconsistent across sources. The release reports first-half adjusted EBITDA of $3.6 million. The call framed it as a record $7.8 million, up 619%. Management raised full-year adjusted EBITDA guidance to $10 million-plus from $8-10 million. Measured against the release's $3.6 million, that implies a sharp second-half step-up from a quarter that was EBITDA-negative. Prior-quarter EBITDA had also been aided by roughly $1.5 million of liability eliminations and stock-for-service arrangements. The revenue guidance itself is telling. Second-half revenue of about $33-38 million looks roughly in line with the current quarterly run-rate, which implies little near-term contribution from the new partnerships. Revenue has also slipped sequentially, from $20.3 million in fiscal Q3 2026 to $19.4 million in Q1 and about $18.0 million now. The release attributes the year-over-year decline mainly to Slacker.
The call kept a growth narrative alive, but it was thin on verifiable detail. The pending partner, described as the largest in company history, is now cited at 50 million-plus paying subscribers and is slated to launch before calendar year-end. Its description has shifted over time, from a 30-million-then-50-million partner in fiscal Q3 2026 to a 15-million-subscriber retailer in Q4. Management declined to disclose the deal's structure, minimums or economics. Other items cited:
- AT&T Mobility and Vizio were presented as live distribution channels, but no subscriber metrics were provided, despite earlier promises of September-November data.
- Content reached Netflix, Disney and Hulu.
- The CEO pledged to buy stock after the launch.
Several themes went unmentioned or unanswered:
- An analyst noted declining PodcastOne downloads, and management sidestepped questions on CPMs and volume. PodcastOne nonetheless posted record first-half revenue of $31.5 million.
- No CFO was on the call.
- The "imminent" acquisition and the AI-licensing revenue promised on earlier calls were not addressed.
Bears have legitimate ammunition here, and the tone was more defensive than on prior calls.
The market had already priced in considerable doubt. Shares closed at $2.78 before the report, down 34.4% from the $4.24 open following the August release and about 39% below the 200-day moving average of $4.58. The Earnings Whispers price and AVWAP trends are both negative. Investor sentiment nonetheless improved meaningfully into the report, rising from -0.42 to roughly neutral at +0.04. That shift suggests expectations had stabilized after a heavy selloff. A revenue miss paired with a guidance cut tests that stabilization directly.
The bottom line is that LiveOne delivered a revenue miss, a smaller-than-expected loss improvement and a fiscal 2027 revenue cut. It offset those with a higher EBITDA target and a fiscal 2028 promise that depends on a partnership investors cannot yet evaluate. The cost discipline is real: headcount has fallen to about 80 from a peak of 350. But adjusted results rely heavily on stock-based add-backs, and the balance sheet remains tight. Until the large partner launches and LiveOne discloses actual subscriber economics, the growth story remains management's expectation rather than demonstrated performance.
Read our earnings preview for LiveOne, Inc.: https://www.earningswhispers.com/article/LVO/23145
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-04 | |
| Oct-12 | |
| Oct-05 | |
| Sep-22 | |
| Sep-17 | |
| Sep-02 | |
| Aug-12 | |
| Aug-12 | |
| Aug-04 |
