Snail Needs Its Delayed July DLC Wave To Deliver A Profitable, Doubled Quarter
Snail spent its last report asking investors for patience. It said the second quarter was light by design, that key ARK content had slipped from June into July, and that roughly $11 million of deferred revenue would land in the third quarter. The report due after the close on November 12 is where that explanation either holds up or falls apart. Wall Street has priced the payoff in. The question is whether Snail can deliver it.
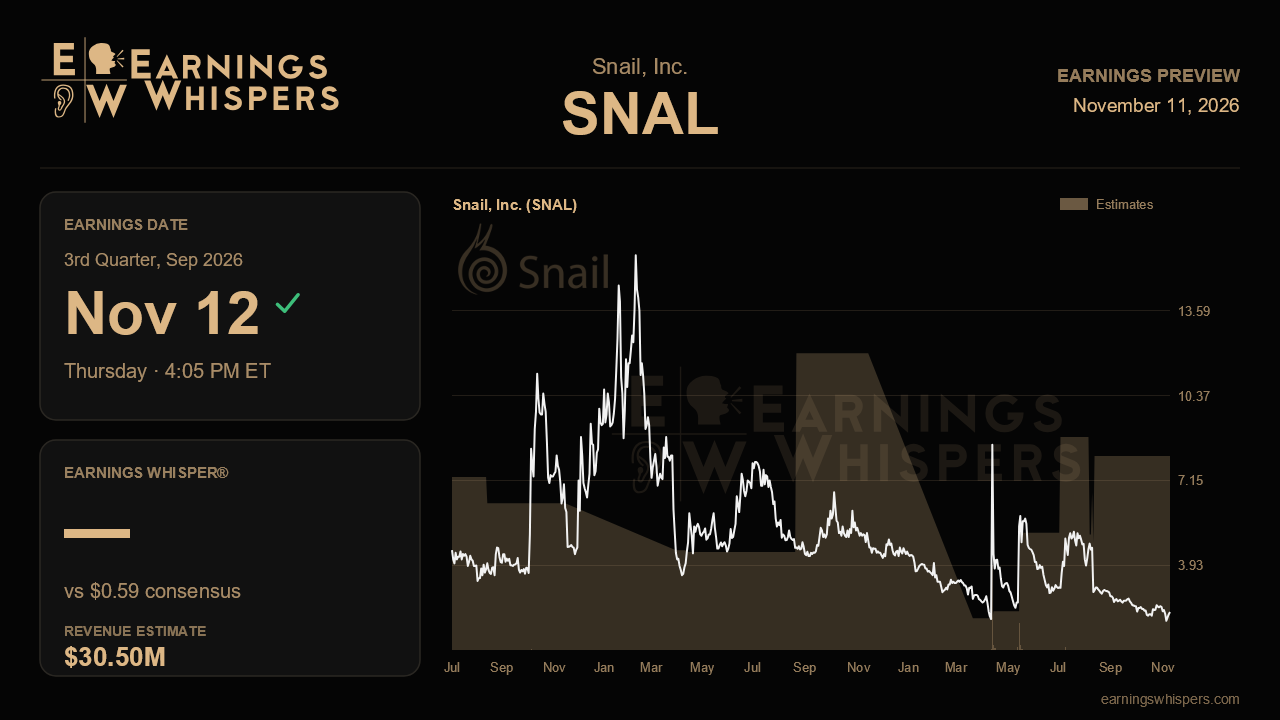
Consensus calls for revenue of about $30.5 million, up roughly 121% from $13.8 million a year ago, and earnings of $0.59 per share. That would be a sharp swing from a $0.21 loss in the year-ago quarter and a $0.36 loss last quarter. The company has not issued formal guidance, so there is no range to check the Street against. A quick sanity check is still useful. Second-quarter revenue of $19.7 million plus the roughly $11 million management said would shift into this period gets you almost exactly to consensus. Analysts are not counting on a demand surge. They are assuming the deferred revenue shows up roughly as described and that the underlying business holds steady around it.
That makes the content slate the core of the report. Genesis Part 1 Ascended, Tides of Fortune and the shadow-dropped Dragontopia all arrived in July. Bookings will show how well that content actually sold. Recognized revenue, by contrast, depends on accounting timing. Because of how Snail books DLC, only a third of the Fantastic Tames pack was recognized in the second quarter, and Dragontopia is being recognized across the third and fourth quarters as content is delivered. Revenue could therefore look solid even if bookings disappoint, or the reverse. Bookings are the cleaner read on demand. They fell about 20% year over year last quarter to $21.8 million. A clear rebound would support management's argument that the weakness was a scheduling quirk rather than franchise fatigue.
That fatigue question is the real risk. ARK: Survival Ascended, ARK: Survival Evolved and ARK Mobile all declined year over year last quarter, and Ascended unit sales fell to about 574,000 from 1.4 million in the first quarter. If unit sales of Ascended, the current flagship, stay soft even with fresh DLC, the bull case gets harder to defend. The margin side looks sturdier. The amended ARK license fee saves roughly $1.5 million a quarter compared with the fixed fee that weighed on results a year ago. Combined with management's pledge to hold G&A and R&D flat, that gives this quarter real operating leverage if revenue arrives.
The smaller growth bets need evidence too. The console launch of Bellwright added about $1.5 million and reached the top five paid titles on Xbox, so a sustained tail would matter. The PixArk TerraCrypt expansion is targeting fall, and any update on its timing will shape fourth-quarter expectations. The AI Ranch companion project and the USDO stablecoin licensing effort are early-stage stories, not near-term earnings drivers. The AAA titles, For the Stars and the Nyan Sutra projects, have been described as in final phases for several quarters without firm dates. Concrete launch timing would help credibility. More vague assurances would not.
The market has not given Snail the benefit of the doubt. Shares are down nearly 34% since the last report, compared with a 3% slip in the S&P 500. At $2.15, the stock trades well below its 200-day moving average of $3.29 and sits in the lower part of its post-earnings range of $1.80 to $3.38. That range is far below the prior quarter's $2.63 to $8.35. Sentiment has also soured, with bearishness rising to 37% from about 23% a quarter ago. The bar is not low on paper, because consensus assumes a near doubling of revenue and a return to profit. But the stock already reflects real skepticism. The deciding issue is whether third-quarter bookings show that ARK demand rebounded with July's content. If they do, the timing story holds. If revenue lands only because of accounting carryover while bookings stay weak, the market will likely treat this quarter as a one-time catch-up.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 5 hours | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-10 | |
| Oct-29 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-01 |
