Snail Beats Handily, But A Deferred-Revenue Release Flatters Q3 As Guidance Softens And ARK Projects Slip
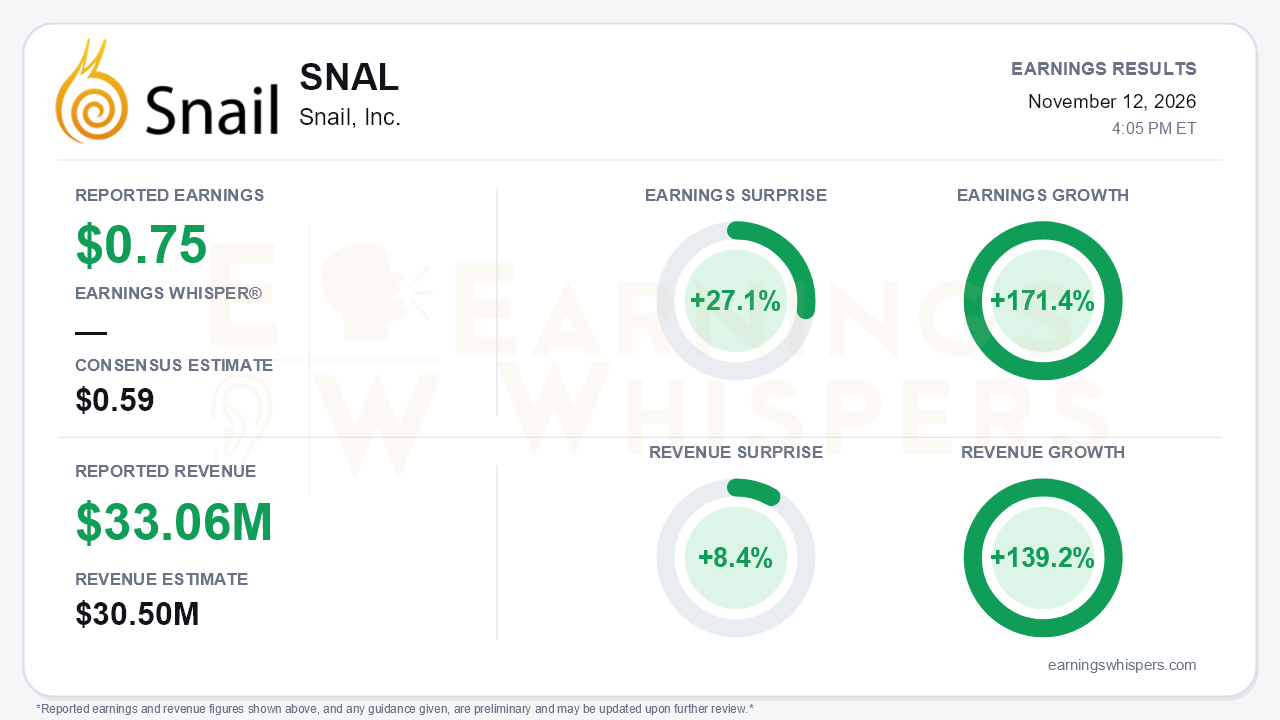
Snail, Inc. delivered its strongest quarter in years. Third-quarter EPS was $0.75, beating the $0.59 consensus by 27.1% and swinging from a $1.05 loss a year earlier, which Earnings Whispers calculates as 171.4% earnings growth. Revenue rose 139.2% to $33.06 million, 8.4% above the $30.5 million consensus. Net income reached $6.7 million against a $7.9 million loss in the prior-year quarter, and EBITDA swung to $7.2 million from a $9.7 million loss. The headline is a clean beat. The quality of that beat, however, deserves scrutiny, and that is the central tension of the report.
The revenue surge relied heavily on accounting timing. Management attributed $13.9 million of the year-over-year revenue increase to a change in deferred revenue. That figure largely reflects the roughly $11 million Genesis-related release the company had flagged on earlier calls. Bookings, which strip out deferrals, were $23.0 million. That is a respectable 30.4% gain from $17.6 million and a clear rebound from Q2's $21.8 million, which was down 20% year over year. Still, bookings were about $10 million below reported revenue. Gross profit jumped to $17.6 million from essentially zero, because revenue recognition outran a much smaller rise in cost of revenue, while operating expenses rose only modestly. The underlying ARK engine did improve. ASA sold about 1.2 million units, and peak DAU climbed to roughly 184,000 from about 155,000 in Q2 after three DLCs landed together in early July. Bellwright's console launch added diversification. The legacy pieces are still shrinking, however. ASE, ARK Mobile and SaltyTV all declined, with ASE revenue down $3.2 million and ARK Mobile down $1.5 million over nine months.
The balance sheet shows the other side of the deferred-revenue tailwind. Total deferred revenue fell from about $32.1 million at year-end to $22.6 million, so less of this cushion remains for future quarters. Unrestricted cash of $12.1 million is up from $8.6 million at December. It has slipped for two straight quarters, though, from $14.3 million in Q1 and $13.3 million in Q2. The company also raised $4.8 million through its at-the-market program, and Class A shares outstanding rose from about 1.8 million to 3.2 million. Stockholders' deficit narrowed to $9.7 million but remains negative.
The conference call tempered the quarter's message. Management's tone was upbeat, framing 2026 as a recovery year after a difficult 2025. The CFO, however, explicitly described the Q4 content slate as more modest than Q3's and asked investors to judge the full year rather than the quarter. That points to a sequential decline. The full-year outlook was softened to "continued growth" versus 2025 and 2024, without reiterating the 20-30% revenue growth target discussed earlier in the year. Nine-month revenue of $80.0 million already nearly matches all of fiscal 2025's $81.2 million, so the new framing sets a low bar. Pipeline timing also slipped:
- ARK: Survival of the Fittest moved from the second half of 2026 to 2027.
- ArkMaker has now slipped from a May 2026 target to 2027.
- The USDO stablecoin initiative, prominent on prior calls, went unmentioned.
- The goal of external testing for For The Stars by year-end was not reaffirmed.
The forward catalysts are real but back-end loaded. Near term, the ARK: Dragontopia skyworld map arrives in December, alongside Fantastic Tames content and the Bellwright traversal update. Further out, the 2027 ARK slate includes Atlantis, Galaxy Wars and Legacy of Santiago DLCs plus a new PixARK Worlds title. Snail is also building awareness for its AAA projects, publicly unveiling both 9 Yin Sutra titles and demoing For The Stars to media. On the platform side, the Noise digital store alpha and Overwolf-driven user-generated content add potential monetization layers. None of these has a firm AAA release date, and the record of slippage gives bears legitimate ammunition.
The market setup is far more pessimistic than the beat implies. Investor sentiment weakened from -0.23 to -0.37 ahead of the report, deepening an already negative stance. Shares fell 33.8% from the $3.25 open after the August report to $2.15. That leaves them roughly 35% below the 200-day moving average and well off the $3.38 inter-earnings high. The stock hit an inter-earnings low of $1.80 on November 5 and sits about 19% above it. Earnings Whispers price and AVWAP trends remain negative, while sequential growth and momentum are neutral.
The bottom line is that Snail's third quarter showed genuine improvement in ARK engagement and bookings, but the headline profit was amplified by a one-time deferred-revenue release that will not repeat in Q4. Softer guidance, slipping 2027 timelines, declining cash and dilution explain why investors entered the report skeptical. Sustained bookings growth and on-time content delivery, not this quarter's EPS beat, will determine whether that skepticism eases.
Read our earnings preview for Snail, Inc.: https://www.earningswhispers.com/article/SNAL/23147
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 4 hours | |
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-10 | |
| Oct-29 | |
| Oct-21 | |
| Oct-21 | |
| Oct-21 | |
| Oct-15 | |
| Oct-15 | |
| Oct-01 |
