PodcastOne Needs Record Revenue To Finally Narrow Losses After A 31% Slide
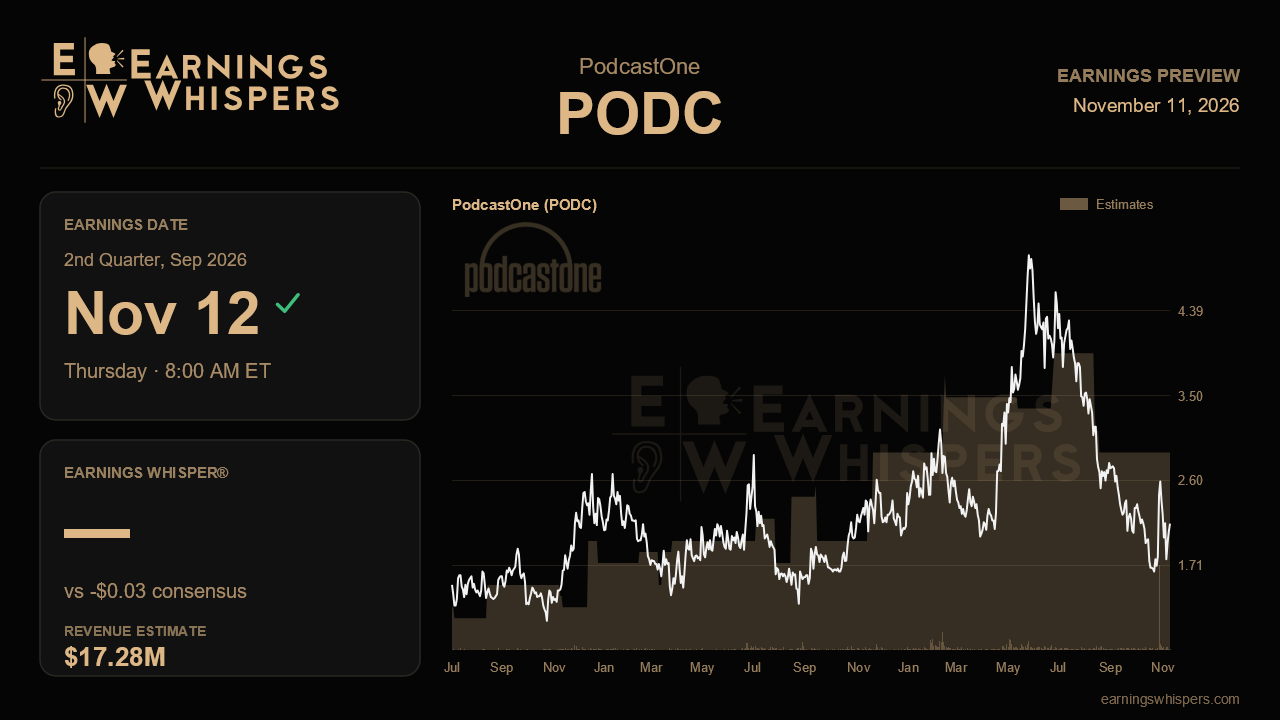
PodcastOne has spent the past year proving it can grow the top line. What it has not yet shown is that growth reaches the bottom line. Last quarter delivered record revenue of $16.1 million and a climb to sixth place in the PodTrack publisher rankings, ahead of Disney. Yet the net loss widened to five cents a share as stock-based compensation inflated general and administrative costs. The stock has fallen roughly 31% since then. The fiscal second-quarter report, due before the open on November 12, is a test of whether scale can start doing the work management says it will.
The Street is asking for a lot on revenue and a little more on costs. Consensus calls for about $17.3 million, up 14% from $15.2 million a year ago. That would be a fresh record and a sequential gain of roughly $1.2 million, which is notable because recent quarters have moved in steps of a few hundred thousand dollars. Analysts also expect the loss to narrow to three cents a share from four cents a year ago and five cents last quarter. Put simply, the forecast assumes revenue accelerates while expense growth cools. Both have to happen for the numbers to land.
Guidance offers little help in judging that bar. A year ago, management laid out a full-year range of $55 million to $60 million in revenue and $4.5 million to $6 million in adjusted EBITDA, then beat the revenue range with $61.7 million. On the most recent call it did not reiterate a comparable fiscal 2027 framework. Combined with sliding profitability, that softer framing helps explain the market's skepticism. Adjusted EBITDA has fallen two quarters in a row, from a record $2.8 million to $1.9 million and then $1.6 million. Restoring a quantified outlook, or showing EBITDA turning back up, would go a long way toward rebuilding credibility.
The operating story points to where the upside could come from. Management described blue-chip advertisers such as Progressive, State Farm, Lowe's and Macy's moving toward higher-value host-read integrations. The Amazon ART19 distribution agreement has stepped up to a $20 million annual run-rate tier. The company also flagged its summer quarter as seasonally soft and calendar fourth quarter as its biggest. That makes this report a bridge period: it should show sequential improvement, but the real seasonal lift comes later. Several new catalysts also deserve early evidence:
the Life Happens acquisition;
the Pave Studios partnership tied to A&E's The First 48;
Stassi's placement on Netflix alongside a Hulu relaunch.
Investors should look for signs these deals are adding audience and ad dollars rather than headlines.
What would validate the narrative is straightforward. That means revenue near or above $17 million, adjusted EBITDA recovering from $1.6 million, and stock compensation stabilizing as a share of costs. Cash also matters. The balance doubled to $7 million last quarter with no debt, and holding that cushion would ease any worry about dilution. What would challenge the story is another record top line paired with a wider operating loss. That outcome would suggest the cost structure is growing as fast as the business.
Expectations have reset meaningfully. The stock trades near $2.15, well below its 200-day average of $2.97 and entirely beneath last quarter's $3.15 to $4.72 range. It sits closer to the bottom than the top of its post-earnings band of $1.41 to $3.43. Sentiment remains bearish, though noticeably less so than heading into the last report, which hints that some of the pessimism has already been absorbed. That combination of improving operating metrics and a punished share price creates room for a positive reaction if margins cooperate. The central question is whether PodcastOne can show operating leverage. Growing revenue is no longer enough on its own; the company needs to show that each additional dollar finally narrows the loss.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-28 | |
| Oct-12 | |
| Oct-05 | |
| Sep-17 | |
| Aug-27 | |
| Aug-12 | |
| Aug-12 | |
| Aug-04 |
