PodcastOne Narrows Its Loss, But A 10.8% Revenue Miss And A Stripped-Down Call Undercut The Beat
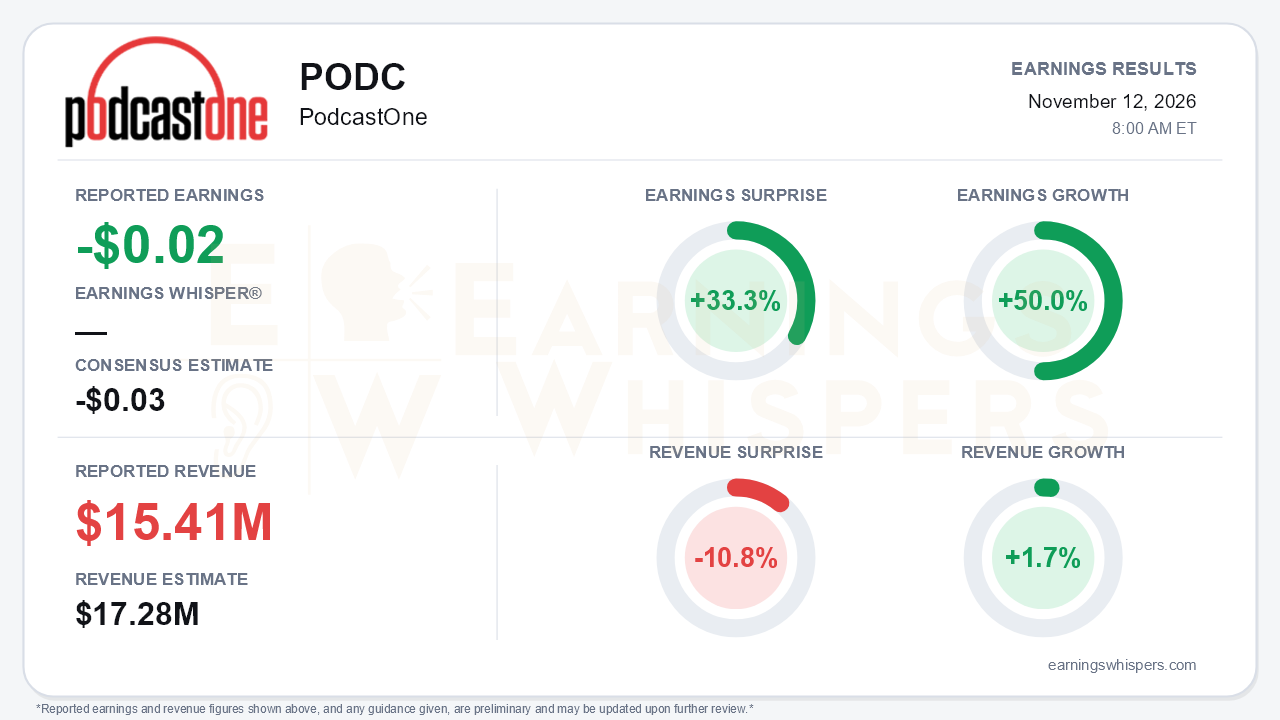
PodcastOne (NASDAQ: PODC) beat on the bottom line and missed badly on the top line. The fiscal second-quarter loss of $0.02 per share topped the -$0.03 consensus by 33.3% and improved 50.0% from a year earlier. Revenue of $15.41 million, however, fell 10.8% short of the $17.28 million consensus and grew just 1.7% year over year. That is the central tension. The loss narrowed because of expense control and lower stock-based compensation, not because the business grew into its cost base. The sales line that was supposed to drive a scaling story went backward from the prior quarter.
The quality of the beat deserves scrutiny. The GAAP operating loss shrank to $479,000 from $975,000 a year ago. Using the six-month totals, it also improved from roughly $1.56 million in the June quarter. Most of that improvement came below gross profit. General and administrative expense fell to $1.33 million from $1.77 million a year ago and from roughly $2.5 million in the prior quarter. Stock-based compensation excluded from adjusted EBITDA dropped to about $1.5 million from roughly $2.8 million in Q1.
The core economics barely moved:
- Cost of sales still consumed about 89% of revenue.
- Gross profit rose only to $1.69 million from $1.61 million.
- Adjusted EBITDA rose 27% year over year to $1.38 million, but that was below the roughly $1.6 million implied for the June quarter and well below the $2.8 million management cited for the December 2025 quarter.
The per-share comparison also benefits from a smaller loss spread over more shares. Weighted shares rose to 30.3 million from 26.5 million, so shareholders are absorbing meaningful dilution.
The call analysis makes the sequential picture harder to dismiss. Revenue of $15.4 million compares with:
- a record $16.1 million in the June quarter;
- $15.7 million in the March quarter;
- $15.9 million in the December quarter.
Management had previously flagged summer as seasonally slow, which explains part of the dip. Still, it is the lowest print in at least four quarters. There is also an unexplained conflict on audience ranking. The release touts a "recent" #6 Podtrac ranking, while the call analysis indicates the September ranking slipped to #8, from #6 last quarter and #7 the quarter before. Investors should weight the more recent figure until management reconciles the two.
What changed most was the call itself. The press release did report adjusted EBITDA, net loss and the balance sheet. The call, however, dropped the financial discussion, CFO commentary, guidance reiteration and analyst Q&A that featured in prior quarters. Management offered no update on the M&A pipeline it had previously described as imminent, or on the path toward $100 million in revenue. The tone moved from exuberant to scripted.
The content pipeline did keep building:
- a multi-year exclusive deal for Brent Spiner and Jonathan Frakes' "Dropping Names";
- the original series "People Pleasers";
- an expanded A&E/Pave Studios slate;
- breakout audience momentum at The Prosecutors.
Those are credible catalysts, but none has yet shown up in revenue.
The balance sheet adds a layer bears have legitimate ammunition on. Cash rose to $7.2 million from $3.5 million in March. Over the same period, the related-party receivable from parent LiveOne jumped to $16.3 million from $5.3 million, and paid-in capital rose by about $10.6 million. The release's risk language still cites going-concern uncertainty and PodcastOne's guarantee of LiveOne's secured debentures. That makes the growing intercompany balance a material exposure, not an accounting footnote.
The market had already priced in plenty of doubt. Shares at $2.15 are down 30.6% since the open after the August report and sit 27.5% below the 200-day moving average of $2.96. The stock fell from an inter-earnings high of $3.43 to a 52-week low of $1.41 on October 19, then rebounded 52.5% off that low heading into the print. Investor sentiment improved notably, from -0.66 to -0.40, but remains firmly negative. Earnings Whispers price and AVWAP trend readings also remain negative.
The bottom line is that PodcastOne delivered a cosmetic earnings beat built on lower compensation and overhead, while revenue missed sharply and slid sequentially. Audience ranking, disclosure and management's confidence all appear to have weakened. The content slate offers a path back to growth. But until revenue reaccelerates and the company explains its growing financial entanglement with LiveOne, the narrower loss is not enough to change a skeptical setup.
Read our earnings preview for PodcastOne: https://www.earningswhispers.com/article/PODC/23146
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-28 | |
| Oct-12 | |
| Oct-05 | |
| Sep-17 | |
| Aug-27 | |
| Aug-12 | |
| Aug-12 |
