Bath & Body Works Faces A Low Q3 Bar As Marketing Push Tests Its Turnaround Story
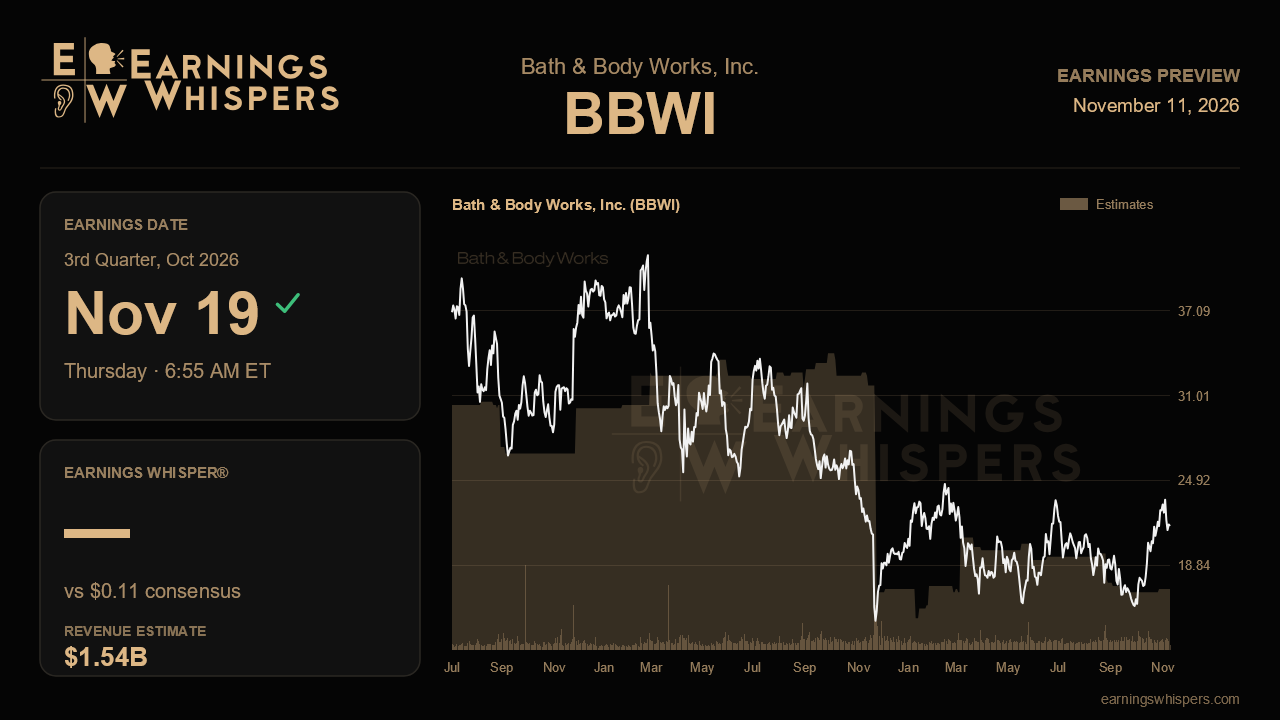
Bath & Body Works enters its third-quarter report with an unusual setup: management has deliberately guided to a weak quarter, yet the stock has rallied as if the turnaround is already working. The company is spending heavily on marketing and absorbing new tariff costs this fall in an effort to restart sales growth by 2027. This report should show whether that spending is beginning to pay off or simply weighing on profits.
Wall Street expects earnings of $0.11 per share on revenue of $1.54 billion, due before the market opens on November 19. That would be a 68.6% drop in earnings from last year's $0.35 and a 3.4% revenue decline, so this is a contraction quarter by any measure. Management's own outlook calls for $0.05 to $0.10 per share on revenue of $1.51 billion to $1.55 billion. The revenue consensus sits in the upper half of that range, but the EPS estimate is slightly above the top of guidance. That matters. The company comfortably beat its own targets last quarter, and analysts are now assuming at least a modest repeat. A result at the midpoint of guidance would technically be in line with what management promised, yet it would still miss the Street.
The second-quarter results explain both the optimism and the caution. Sales fell 2.3%, better than guidance and better than the first quarter. Digital sales grew for the first time since 2021. Amazon sales more than tripled from the prior quarter, and the brand launched in roughly 600 Ulta Beauty doors. Fruit Fusion, a body care line backed by Hilary Duff, beat sales expectations at higher prices than the core assortment. The underlying business was less impressive, however. The headline EPS of $0.62 included an $80 million tariff refund, and without it adjusted EPS was $0.31, with gross margin down 90 basis points. Store sales in the U.S. and Canada fell 5.4% on weak traffic, and body care was still declining at a mid-single-digit rate.
That leaves a clear test for the third quarter. The guidance implies no improvement from the second quarter's sales trend, while about $35 million of extra marketing and roughly $30 million of second-half tariff and input costs pressure earnings. The narrative would be confirmed by several signs together: sales at or above the high end of the range, continued digital growth, rising contributions from Amazon and Ulta, and any slowdown in the store traffic decline. Evidence that Fruit Fusion and the restaged Everyday Luxuries line are lifting the broader body care category, rather than just winning share within it, would be especially meaningful. Signs that the marketing spend produced little more than impressions would weaken the story, particularly with an interim CFO in place.
The full-year outlook may matter as much as the quarter. Management raised fiscal EPS guidance to $2.60 to $2.80, lifted free cash flow guidance to about $650 million, and now expects about $200 million of cost savings. Because the third quarter contributes so little to annual profit, holding or tightening that range would effectively tell investors that management is confident about the holiday season.
Expectations have clearly shifted. Sentiment remains bearish but has improved meaningfully from a quarter ago, and the shares have gained 18.6% since the last report while the S&P 500 slipped 1.9%. At $21.65, the stock sits above its 200-day moving average of $19.81 but about 10% below its post-earnings high of $23.96. That still leaves room to move up, but it also means investors have already priced in some of the progress. The central question is whether the new channels and product launches can offset weak mall traffic quickly enough to justify the fall spending. If they can, the 2027 growth target starts to look credible. If not, the second-quarter beat may look more like the effect of a tariff refund than a genuine turnaround.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-06 | |
| Nov-05 | |
| Nov-02 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 | |
| Sep-28 | |
| Sep-10 | |
| Sep-02 | |
| Aug-27 | |
| Aug-27 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 |
