Bath & Body Works Doubles The Q3 Consensus, But A Tariff-Squeezed Holiday Outlook Keeps The Beat From Reaching Full-Year EPS
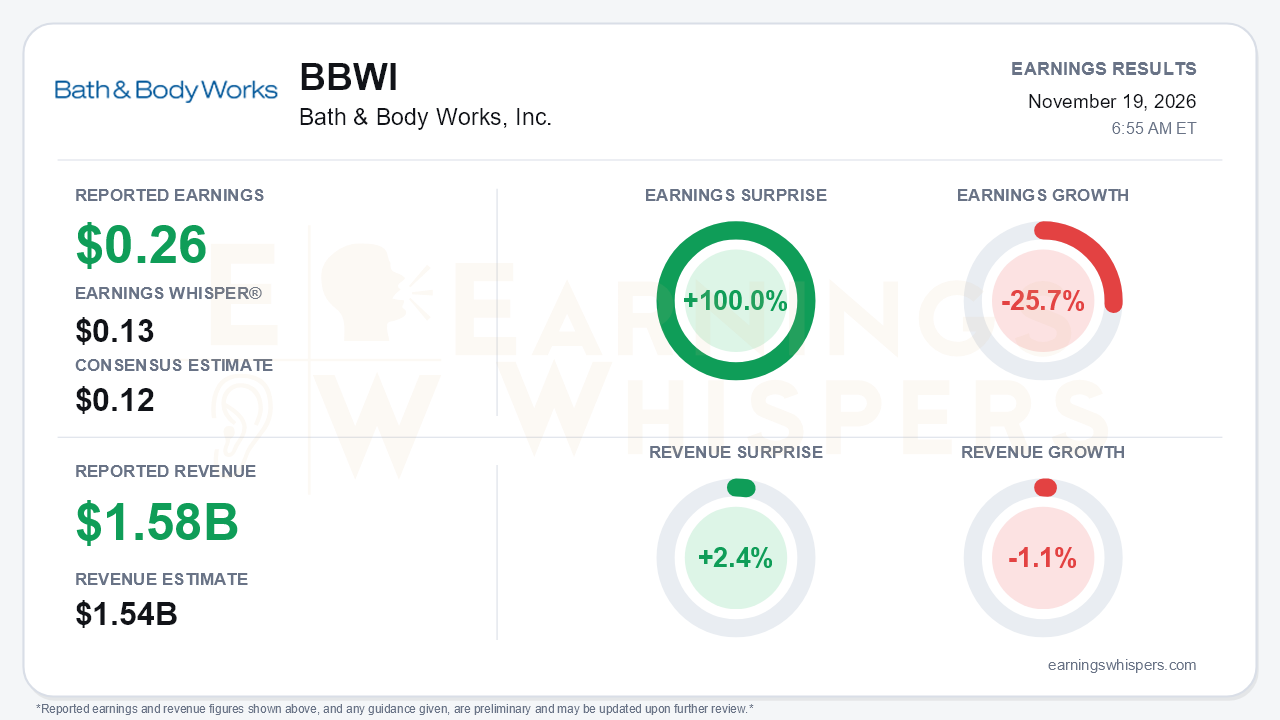
Bath & Body Works delivered a decisive third-quarter beat. Adjusted earnings of $0.26 per share were more than double the $0.12 consensus and the $0.13 Earnings Whisper number, a 100.0% surprise. Revenue of $1.577 billion topped the $1.54 billion consensus by 2.4%. Management's own guide had called for $0.07 to $0.12 and a 2.5% to 5% sales decline, so the company cleared its own bar by a wide margin. Yet earnings still fell 25.7% year over year, revenue slipped 1.1%, and full-year adjusted EPS guidance was held at $2.60 to $2.80 rather than raised. That is the central tension: the top line is visibly healing, but higher costs are absorbing the improvement before it reaches the bottom line.
The beat was real at the sales line. Its earnings quality deserves more scrutiny.
- **Operating income:** Adjusted operating income fell to $121 million from $161 million.
- **Gross margin:** Gross profit declined despite roughly flat sales. Adjusted gross margin of 40.8% edged past the roughly 40% guide but remained below last year's level.
- **Expenses:** General, administrative and store operating expenses rose to $530 million from $497 million.
- **Below the operating line:** Lower interest expense ($58 million versus $68 million, following $542 million of year-to-date debt repayment) and a lighter tax provision cushioned the decline.
- **GAAP results:** Reported EPS was $0.19 versus $0.37, weighed down by $13 million of transformation costs and a $5 million debt-extinguishment loss.
In other words, the beat came from sales outperforming a deliberately low bar, not from margin expansion.
The call made a credible case that the Consumer First Formula is gaining traction. The sales decline narrowed for a third straight quarter, from 3.2% in Q1 to 2.3% in Q2 and about 1% in Q3. The improvement came from several channels:
- **International and Other:** Sales jumped 39% to $101 million, accelerating from roughly 25% in Q2 and 9% in Q1.
- **Direct:** Digital grew about 3%, its second consecutive quarter of growth.
- **Ulta:** The partnership expanded from roughly 600 to about 1,500 doors for the holiday season.
- **New franchises:** Essentials, Reserve, Fruit Fusion and the reimagined Everyday Luxuries now account for a mid-single-digit share of sales at premium price points. Essentials is showing a 30-day repurchase rate above 50%.
- **Cost savings:** The Fuel for Growth program is tracking near $200 million against a $175 million target.
The weak spot is the core store base. U.S. and Canada stores were still down about 4%, only modestly better than Q2's 5.4% decline. Management also acknowledged that body care remains well below expectations and the Halloween collection underperformed.
The outlook is where bears have legitimate ammunition.
- **Q4 sales:** The guide of a 2% to 5.5% decline implies a sequential slowdown from Q3. Management cited wholesale timing and weaker external traffic late in the quarter.
- **Q4 earnings:** EPS guidance of $1.41 to $1.61 compares with $2.05 adjusted a year ago and sits below Street estimates.
- **Q4 gross margin:** Guided to about 42.4%, with more than 200 basis points of headwind from Canadian tariffs and crude-oil-driven input inflation.
- **Full-year cuts:** Gross margin guidance fell to about 42.8% from 43.3%. Free cash flow guidance dropped to about $600 million from $650 million as inventory builds. Capex was trimmed to about $215 million.
Full-year sales guidance did rise to a 2.1% to 3.4% decline, the third consecutive upward revision. Competition adopting the company's seasonal, fragrance-led playbook, supply constraints on new products and a still-interim CFO add to the list of open questions.
Capital returns provide some offset. Buybacks resumed at roughly $60 million in Q3, and the board authorized a new $500 million program, which was not contemplated in the original 2026 plan.
Investor sentiment remained negative but improved slightly, moving from -0.23 to -0.19. That is a modest thaw, not a re-rating of expectations. The price action shows how unsettled the market has been:
- Shares entered the report at $18.66, only 2.2% above the opening price after the August release.
- The stock had rallied from a $15.75 low in late September to $23.96 on November 5, then gave back most of that move.
- It sat 22.1% below that high and 5.6% below its 200-day moving average of $19.76.
The Earnings Whispers trend signals are mixed, with sequential growth and momentum positive while AVWAP remains negative. That is consistent with a stock whose fundamentals are stabilizing while its price structure has not repaired.
The bottom line is that Bath & Body Works produced its strongest evidence yet that the turnaround is broadening, with digital, wholesale, international and new product franchises all contributing. Investors, however, are being asked to accept a holiday quarter in which tariffs and inflation offset that progress, free cash flow guidance moves lower, and the core store fleet keeps shrinking in sales. The sales story is improving, but the earnings story is still waiting. Management's 2027 return-to-growth target now carries the weight of the investment case.
Read our earnings preview for Bath & Body Works, Inc.: https://www.earningswhispers.com/article/BBWI/23159
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 32 min | |
| 2 hours | |
| 2 hours | |
| 4 hours | |
| 4 hours |
Bath & Body Works CEO Says Turnaround Progressing But Incomplete
BBWI +3.79%
The Wall Street Journal
|
| 4 hours | |
| 7 hours | |
| 8 hours | |
| Nov-11 | |
| Nov-06 | |
| Nov-05 | |
| Nov-02 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 |
