Liquidity Services Needs A Clean Q4 As Stock Tests Highs And CAG Timing Lingers
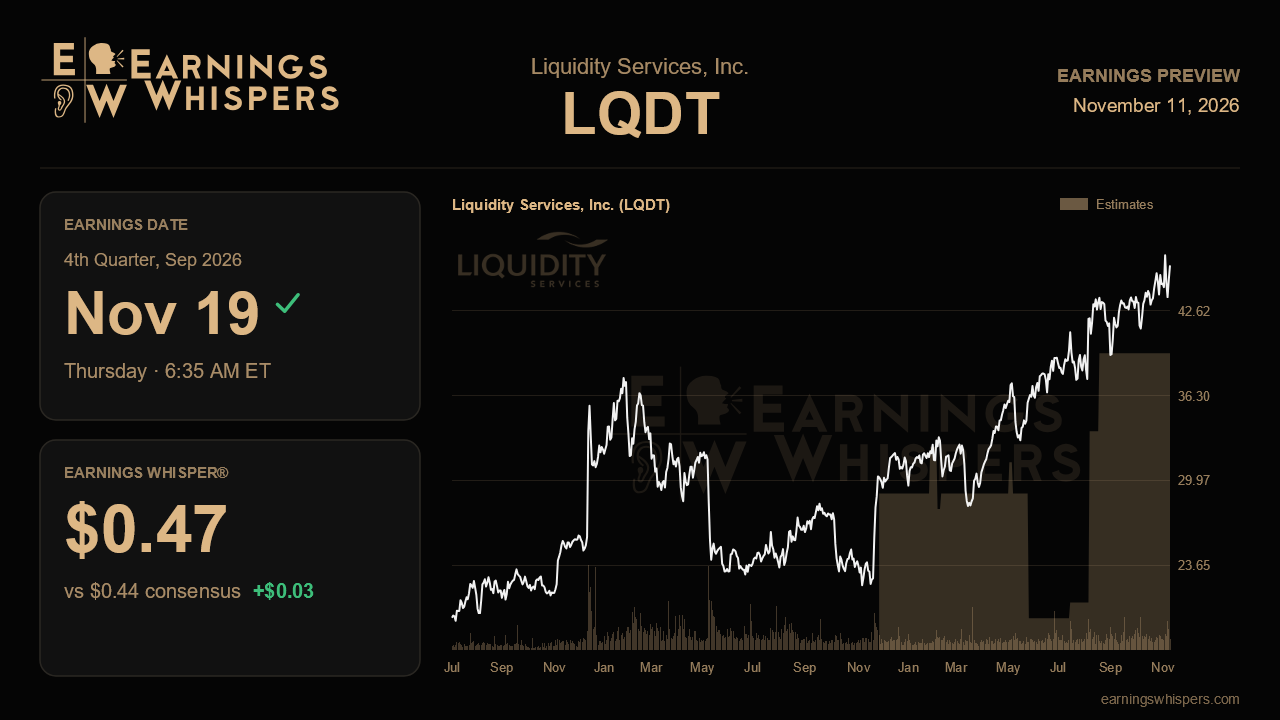
Liquidity Services enters its fiscal fourth-quarter report with momentum, a stock near its highs and an outlook that management has already raised. That combination raises the bar. Last quarter the surplus-asset marketplace posted record gross merchandise volume and a tenth straight quarter of year-over-year adjusted EBITDA growth. It also guided to its best annual EBITDA in 13 years. The question now is whether the September quarter confirms that the business has moved to a higher level, or whether the one weak spot, lumpy timing in its Capital Assets Group, becomes harder to dismiss.
The Street expects earnings of $0.44 a share, up about 19% from the $0.37 earned a year ago and well above the $0.32 posted last quarter. Management guided to non-GAAP EPS of $0.41 to $0.50, so consensus sits just below the midpoint. The whisper number of $0.47 sits above the midpoint, which suggests the informal bar is somewhat higher than published estimates, though not dramatically so. The company also guided to GMV of $450 million to $455 million and adjusted EBITDA of $22 million to $25 million. The GMV range roughly matches the record $453 million from the third quarter, so the guide assumes the company holds its new level rather than breaking well above it. One detail matters for per-share results. Management flagged a higher effective tax rate, in the low-to-mid 30s, so solid EBITDA could translate into less impressive EPS. An EBITDA print near the top of the range will matter more than a penny or two on the bottom line.
The narrative rests on two engines. Retail, through the RSCG segment, accelerated from 3% GMV growth in the first quarter to 10% and then 19%, with direct profit up 30%. The RetailRush direct-to-consumer platform grew GMV 50% sequentially. Holding growth in the high teens would show the acceleration is structural and not a one-quarter surge. GovDeals rebounded to a record $274 million after a weather-hit second quarter, supported by seller growth, a 23% jump in buyer registrations and a 42% increase in new bidders. This quarter should also include the closing of the Miami-Dade County downtown courthouse sale, a showcase for GovDeals' push into high-value real estate. A strong result there would make the case that the platform can win larger, more lucrative mandates.
CAG is the real test. Its GMV slipped 1% last quarter as large projects slid out and volumes softened in EMEA, Asia-Pacific and parts of North American industrial markets. Management called the shortfall deferred rather than lost and said the pipeline had strengthened. A return to growth, or proof that delayed projects have closed, would support that view. Another flat or down quarter would weaken it. Even then, the 270-basis-point improvement in take rate that lifted CAG direct profit 13% shows management can protect profit while volume is uneven. Watch also the Machinio software business, where ARR growth sped up to 26% and the marine vertical nearly doubled, and the 5% drop in auction participants, which the company tied to a shift toward higher-value lots.
The market has priced in much of this progress. Shares are up 15% since the last report while the S&P 500 fell 2.6%, and at $46 the stock sits well above its 200-day average of $37.41 and within about 3% of its post-earnings high of $47.31. Sentiment has cooled, however, from clearly bullish before last quarter to roughly neutral now. That points to a crowd that respects the momentum but is less willing to chase it.
With $231 million in cash and no debt, balance-sheet risk is not the issue. The issue is breadth. If retail and GovDeals keep compounding and CAG shows that deferred projects are coming back, the steady climb toward $2 billion in annual GMV looks credible and the stock has room to break out. If CAG stays soft and the tax rate eats into EPS, a stock trading near its highs may struggle even on a respectable quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-05 | |
| Oct-22 | |
| Oct-01 | |
| Sep-10 | |
| Aug-21 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-22 | |
| Jul-07 | |
| Jul-06 | |
| Jun-04 | |
| May-26 | |
| May-07 |
