Liquidity Services Misses The Whisper As Margin Gains Mask Stalling GMV; Invaluable Deal Carries An Organically Cooler Outlook
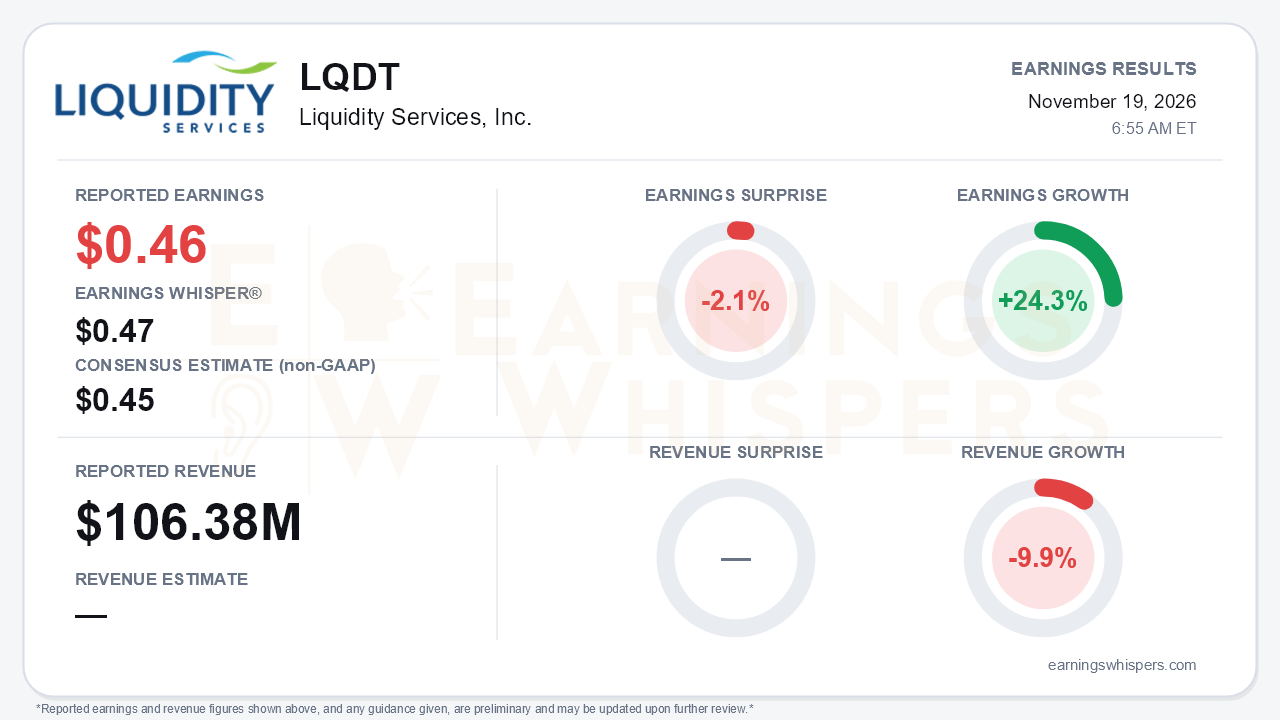
Liquidity Services delivered fiscal fourth-quarter non-GAAP earnings of $0.46 per share. That was a penny above the $0.45 consensus but short of the $0.47 Earnings Whisper number, a 2.1% miss against the higher bar. Earnings grew 24.3% year over year while revenue fell 9.9% to $106.38 million. The divergence is deliberate: the shift toward consignment and higher-margin inventory continues to trade revenue for profit. The more important problem is that the top line stalled at the wrong moment. Revenue swung from 8% growth in the third quarter to a 10% decline. Gross merchandise volume was flat at $404.0 million, well below the $450-$455 million management had pointed to on the prior call. That is the central tension: record full-year profitability arrived alongside a fourth quarter that undershot its own volume roadmap and a first-quarter outlook that leans on an acquisition.
The quality of the beat deserves scrutiny. GAAP net income jumped 52% to $11.9 million, or $0.36 per share. Part of that outperformance reflects a $2.1 million drop in stock compensation against a year-ago quarter burdened by accelerated performance-award expense. Adjusted EBITDA rose 20% to $22.3 million, landing at the low end of the $22-$25 million guide. That is a notable comedown from the third quarter, which cleared its range. It also marks a deceleration from the 30%-38% EBITDA growth posted in the first three quarters. The genuine operating improvement sits in segment mix. Retail (RSCG) direct profit margin expanded 910 basis points to 35.0% even as revenue fell 18%. CAG revenue climbed 18% with direct profit up 16%, its best quarter in roughly a decade. GovDeals direct profit margin reached 95.9%.
Beneath those margins, several growth engines cooled. GovDeals GMV growth slowed to 1%, down from 9% in the third quarter, as used-vehicle values softened. Machinio & Software revenue was flat after rising 27% in the first quarter, with advertising declining. The biggest wrinkle came from retail. A top-10 client delivered a surge of inventory that exceeded near-term buyer demand. Management paced sales to protect margins, which depressed recovery rates and added storage and transportation costs that are expected to linger for roughly two quarters. Inventory climbed to $22.2 million from $14.2 million a year earlier, and full-year operating cash flow slipped to $58.0 million from $66.8 million. Buyer engagement offers a real counterweight. Auction participants rose 24% to about 1.25 million, reversing a decline flagged on the prior call, and completed transactions increased 36%.
The forward narrative now belongs to Invaluable, acquired October 1 for $80 million in cash. The deal extends the platform into fine art, antiques and collectibles, lifts the combined buyer base to roughly 10 million, and brings AuctionZip as a potential transactional and SMB-software opportunity. Management raised its ambition from $2 billion to $2.5 billion in annual GMV and outlined a path toward roughly $100 million in EBITDA run rate. First-quarter guidance calls for $580-$640 million in GMV and adjusted EPS of $0.36-$0.45, versus $0.39 a year ago. Adjusted EBITDA is guided to $19-$22 million against $18.1 million last year. Earnings Whispers characterizes the guide as in line with expectations, yet the EBITDA range sits below the prior quarter's guide even with an accretive acquisition included. Retail GMV and revenue are expected to decline year over year. The CEO asserted double-digit organic growth, but no organic breakdown was provided, and bears have legitimate ammunition in that gap. CAG offers a credible offset, with slipped EMEA projects scheduled for completion and management calling for the segment's best year ever. Bid4Assets real estate wins and Machinio surpassing 1,000 subscribers add smaller tailwinds.
Investor expectations had already cooled heading into the print. Earnings Whispers sentiment remained positive but weakened meaningfully, falling from 0.27 to 0.07. The stock has held up better than sentiment. Shares closed at $43.97 before the report, up 9.9% from the $40.00 open following the August release and 16.4% above the 200-day moving average. They had, however, slipped 7% from the 52-week high of $47.31 set on November 5, after rebounding from a September 1 low of $38.49. Momentum and AVWAP trend readings remain positive, while price and sequential growth are neutral. That mix suggests a stock still being treated constructively, even as enthusiasm thins.
The bottom line is that Liquidity Services is executing well on profitability, but the growth story has become harder to read. Mix-driven margins and record buyer participation are real strengths. Against them, the quarter brought a GMV miss, a retail inventory overhang, decelerating GovDeals and Machinio trends, and a first-quarter outlook in which Invaluable obscures organic momentum. Until management shows organic growth separately from the acquisition, investors are being asked to take more of the forward story on faith than the trailing numbers alone would justify.
Read our earnings preview for Liquidity Services, Inc.: https://www.earningswhispers.com/article/LQDT/23163
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 8 hours | |
| 9 hours | |
| Nov-11 | |
| Nov-05 | |
| Oct-22 | |
| Oct-01 | |
| Sep-10 | |
| Aug-21 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Jul-22 | |
| Jul-07 |
