Futu Faces Its First Real Test Of Post-Regulation Momentum As Revenue Is Expected To Slip
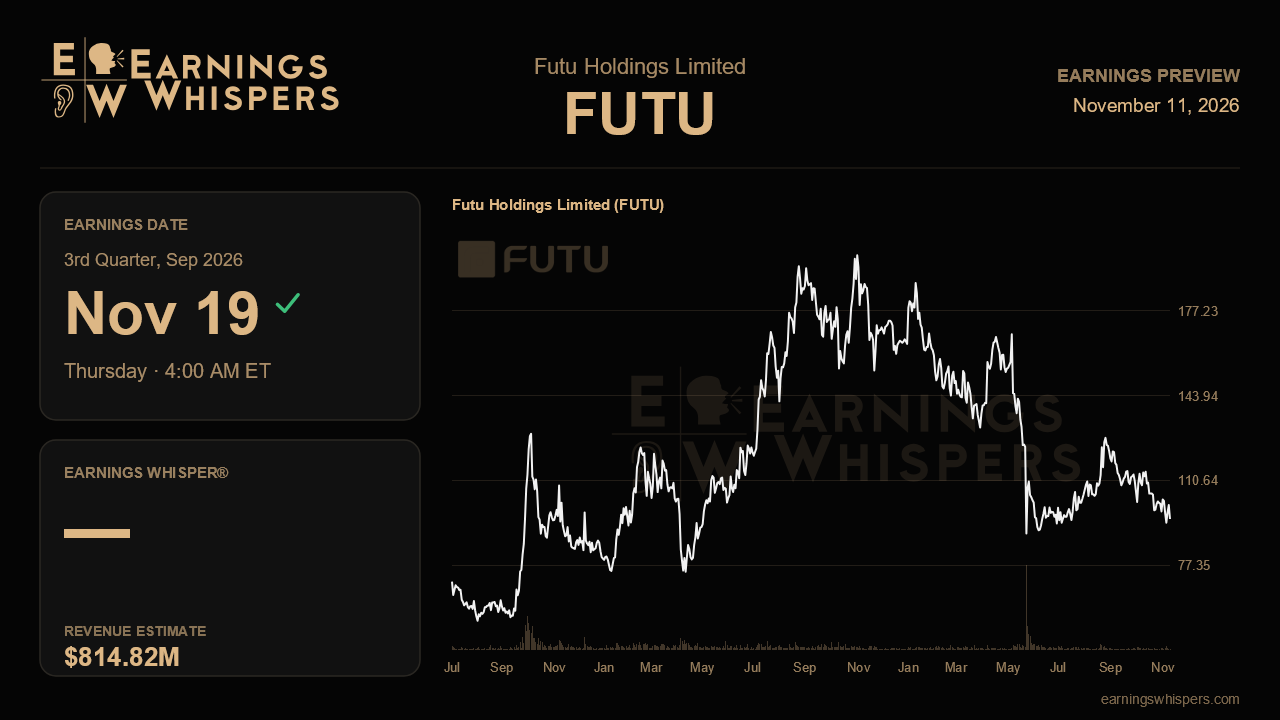
Three months ago Futu posted a record quarter and then told investors the next one would be softer. That candor is now the whole setup. The online broker heads into its September-quarter report with the Street expecting revenue of roughly $814.8 million, about 1% below the year-ago figure and more than 11% below the $918.2 million it delivered last quarter. After a run of double-digit growth, a flat-to-down top line would be a meaningful change in character, and the question is whether it looks like a temporary pause in retail enthusiasm or the start of a lower plateau shaped by regulation and competition.
The comparison is harsh by design. The year-ago quarter was Futu's peak, when revenue grew 86%, so even a respectable result will look stagnant on paper. A cleaner read comes from the operating metrics management flagged on its last call. In the second quarter, trading volume hit a record HK$6.42 trillion, driven by heavy US turnover in AI-linked names, client assets rebounded to HK$1.4 trillion, and margin financing balances jumped to HK$95.1 billion. Management then cautioned that quarter-to-date trading volume was down sequentially, new funded accounts were moderating, and net asset inflows had returned to normal as retail sentiment cooled. Consensus has essentially taken management at its word. A revenue figure meaningfully above consensus would suggest the slowdown was shallower than feared; anything well below would imply cooling turned into something sharper.
The biggest swing factor is the fallout from the May 22 cross-border rules issued by mainland and Hong Kong regulators. Management put the damage at a mid-single-digit percentage of total client assets, with mainland attrition concentrated in June and July and easing by August. This report should show whether that moderation held. Stable or rising client assets despite the outflows would validate the view that the hit was a one-time adjustment. A further decline, especially paired with softer margin balances, would raise concern that the affected client base is still leaking. Interest income, which rebounded to HK$3.1 billion last quarter, depends heavily on those margin balances and offers a useful cushion if trading cools.
Unit economics deserve equal attention. The blended commission rate slipped last quarter as trading shifted toward higher-priced tech shares, and customer acquisition cost rose to about HK$2,600 per account, trending higher into July. Management has reaffirmed, not raised, its target of 800,000 net new funded accounts for the year. With growth slowing, investors need evidence Futu can keep adding accounts without paying ever more for each one, particularly against intensifying Hong Kong competition. The newer initiatives, including securities-backed margin lending for virtual assets, the Thailand license, US prediction markets that traded more than 200 million contracts in their first month, and Malaysia's move to operating break-even, are the pieces that could support that acquisition story. Early signs of contribution would help.
The market has already priced in plenty of doubt. Shares have fallen almost 19% since the last report, trailing the S&P 500 by nearly 17 points, and at about $95 they sit well below the 200-day moving average near $123 and close to the bottom of the post-earnings range that ran from roughly $87 to $128. Sentiment has improved modestly from the prior quarter but remains only mildly positive, suggesting investors are cautious rather than capitulating.
That leaves a clear test. Futu's narrative after last quarter was resilience: a business absorbing a regulatory shock while new markets and products mature. If client assets held, acquisition costs stabilized and the full-year account target still looks achievable, a depressed stock could find footing even on a flat revenue quarter. If outflows persisted and the softer run rate deepened, the market will likely conclude the record second quarter was the high-water mark.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-11 | |
| Nov-05 | |
| Oct-19 | |
| Oct-10 | |
| Oct-08 | |
| Sep-15 | |
| Sep-06 | |
| Sep-01 | |
| Aug-27 | |
| Aug-26 | |
| Aug-20 | |
| Aug-20 | |
| Aug-20 | |
| Aug-17 |
