Futu Beats On Revenue, But Q3 Shows A Sharp Post-Record Slowdown That Wealth Management Only Partly Offsets
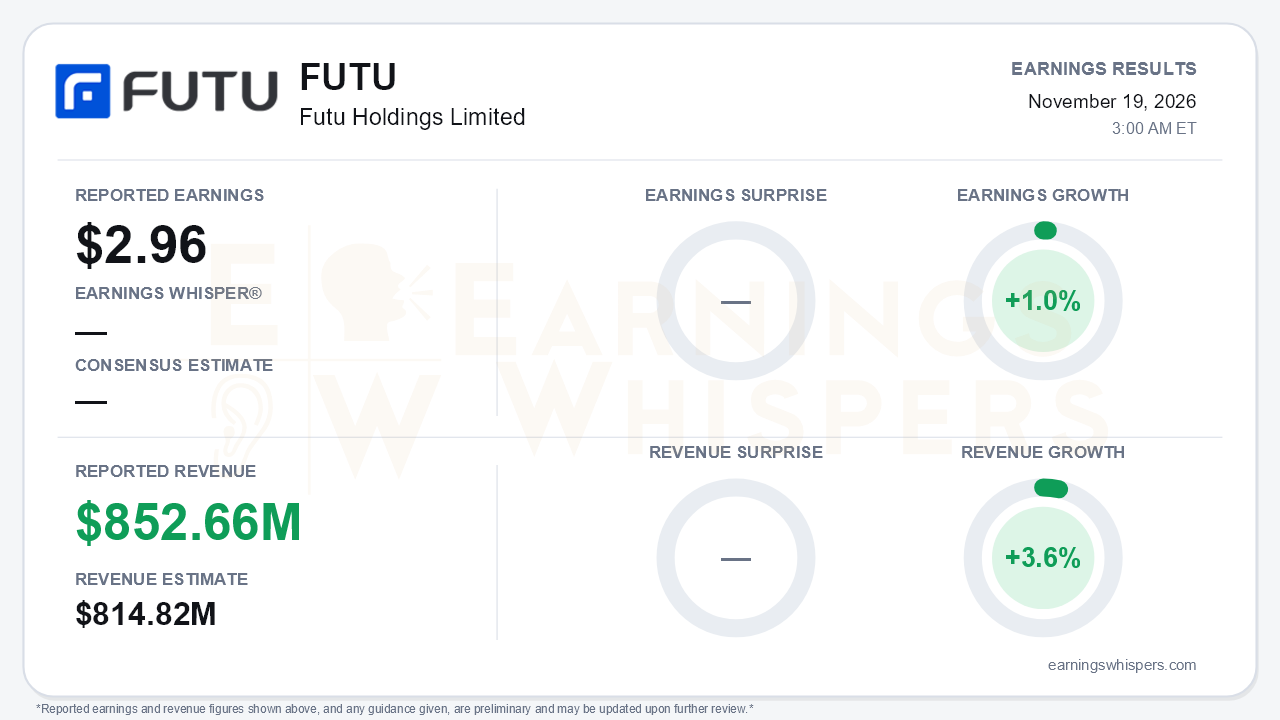
Futu Holdings beat revenue expectations in the third quarter, but the more important story is how much its growth slowed after a record second quarter. The online broker reported earnings of $2.96 per ADS, up 1.0% from a year earlier, on revenue of $852.66 million. Revenue topped the $814.82 million consensus by 4.6% and grew 3.6% year over year. There was no consensus EPS estimate available to measure an earnings surprise. In Hong Kong dollar terms, the company reported revenue growth of 4.5%; the gap with the dollar-based figure reflects currency translation. Either way, the deceleration is stark. According to the call analysis, year-over-year revenue growth had been 45% in Q4 FY25, 25% in Q1 and 36% in Q2. Sequentially, revenue fell 7.1%, and non-GAAP adjusted net income dropped 12.2%. The revenue beat says expectations had already been reset lower. It does not say the growth engine is intact.
The quality of the quarter deserves scrutiny. Brokerage commission income fell 4.1% year over year to HK$2.79 billion, and the call put the sequential decline at 17%. Trading volume still rose 28.4% from a year earlier, but the blended commission rate dropped from 7.5bp to 5.6bp. Costs rose 33.6% while revenue grew mid-single digits:
- cloud-driven processing costs climbed 48%;
- brokerage expenses increased 48.7%;
- interest expense rose 23.6%.
As a result, gross margin compressed to 84.2% from 87.6% a year ago and 86.3% in Q2. Cost cuts did much of the work underneath the flat earnings line. Operating expenses fell 6.7% year over year, including a 15.7% reduction in R&D. That held operating margin at 60.4%, versus 61.0% a year earlier and roughly 62% in Q2. Below the operating line, "others, net" was a HK$233 million drag, up from HK$35 million a year ago. GAAP net income slipped to HK$3.19 billion. Diluted EPS edged higher mainly because the diluted share count fell about 2.6%. The loan-loss allowance also rose to HK$863 million from HK$375 million at year-end, a detail worth watching given the swings in margin balances.
The operating metrics tell the same story of slowing momentum. Trading volume fell 22% sequentially from a record HK$6.42 trillion as semiconductor and AI names pulled back. Margin and securities lending balances dropped 22.3% to HK$73.8 billion, and client assets declined 4.6% to HK$1.33 trillion. Net new funded accounts slowed to 163,000, from 252,000 in Q2 and 225,000 in Q1. That leaves roughly 640,000 year to date against an 800,000 full-year target, which management did not explicitly reaffirm. Management's tone also changed. The celebratory framing of Q2 gave way to repeated emphasis on "resilience" and long-term confidence.
The call did preserve a credible diversification narrative:
- Wealth management client assets rose 9.0% sequentially to HK$196.4 billion, a clear acceleration from about 1% growth in Q2.
- Wealth management penetration reached 28.2%, or 1.13 million clients.
- Futu disclosed net asset inflows for the first time: HK$34.5 billion, with more than 60% coming from existing clients.
- Other income jumped 65.5% on currency exchange and fund distribution fees.
- Management said low-beta revenue, now over 20% of the total, grew double digits.
- Moomoo Japan resumed normal account opening on September 24.
- Prediction markets reached roughly 500 million contracts and were the top revenue driver among new client cohorts.
- Extended-hours trading already exceeds 20% of U.S. volume, which positions Futu to benefit from Nasdaq's 23x5 framework.
Bears have legitimate ammunition. Mainland China's share of revenue has fallen from 20% in Q1 to the low teens. Management expects it to drop below high single digits within two to three quarters, with continued outflows. Japan also remains under regulatory rectification, with no large-scale marketing yet. The call analysis cited a year-ago net margin of 58.2%, but the release puts the prior-year figure at 50.2%. On the release's numbers, the decline to 47.6% is real but more modest than the call figure implies.
The market had already priced in much of this. Shares fell 29.3% from the opening price after the August report to $83.18. They now sit about 31% below the 200-day moving average and less than 1% above the inter-earnings low, which was set the day before the release. The stock has erased an entire post-Q2 run that peaked at $128.43 in late August. Investor sentiment slipped from mildly positive to essentially neutral, a meaningful cooling but not capitulation. Price and AVWAP trend readings remain negative.
The bottom line is that Futu delivered a revenue beat and flat earnings in a quarter that exposed how dependent the franchise still is on trading activity and pricing. Wealth management inflows, cost discipline and new products cushioned the downturn without offsetting it. With shares near their lows, the next test is whether Q4 account growth and asset inflows can show the slowdown was cyclical rather than structural.
Read our earnings preview for Futu Holdings Limited: https://www.earningswhispers.com/article/FUTU/23162
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 27 min | |
| 4 hours | |
| 5 hours | |
| 11 hours | |
| Nov-11 | |
| Nov-11 | |
| Nov-05 | |
| Oct-19 | |
| Oct-10 | |
| Oct-08 | |
| Sep-15 | |
| Sep-06 | |
| Sep-01 | |
| Aug-27 | |
| Aug-26 |
