Maximus Faces VA Incentive Pause Test After Cutting Profit Outlook As Shares Rally
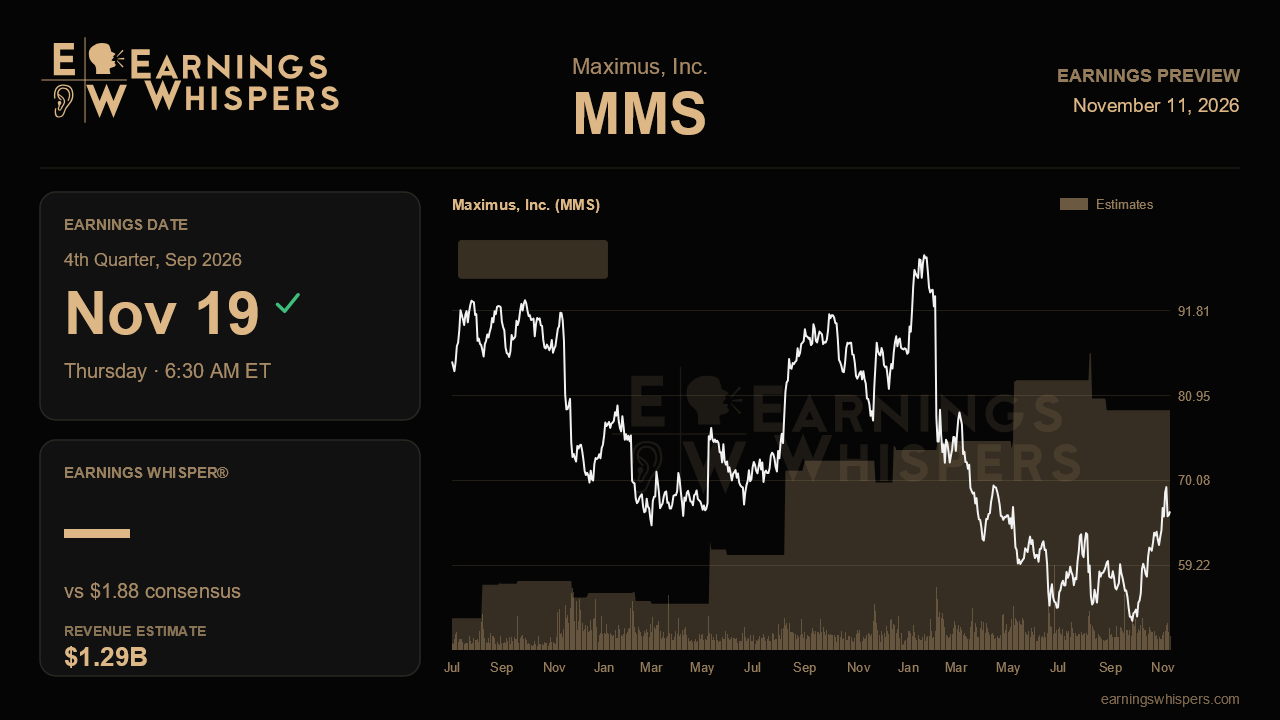
Maximus heads into its fiscal fourth-quarter report with an unusual combination of a lowered profit outlook and a stock that has climbed sharply anyway. Management trimmed its fiscal 2026 earnings forecast to $7.90 to $8.20 per share from $8.25 to $8.55 while holding revenue guidance at $5.20 billion to $5.35 billion. That cut ended a streak of two consecutive raises earlier in the year. The market has looked past it: shares are up about 14% since the last report while the S&P 500 slipped roughly 3%. The question now is whether the earnings hit is as contained as investors seem to believe.
For the September quarter, Wall Street expects earnings of $1.88 per share on revenue of about $1.29 billion. That works out to EPS growth of roughly 16% from $1.62 a year ago, even as revenue is expected to shrink about 2%. Profit growth on falling sales means margins are doing the heavy lifting. The quarterly estimate also marks a clear step down from the $2.22 Maximus earned last quarter on similar revenue. That decline is the clearest sign that analysts have priced in the margin hit management flagged. One caution: the full-year consensus of $8.43 still sits above the top of the reduced guidance range. That suggests some annual estimates have not caught up, so headline comparisons may look messier than the quarterly bar implies.
The main swing factor is the paused incentive payments on the Veterans Affairs disability examination work. Those incentives had grown into a meaningful contributor this year. Management said their absence implies a fourth-quarter run rate near 13% adjusted EBITDA margin, compared with 14.4% in the fiscal second quarter. A margin at or modestly above 13% would confirm the damage is roughly what the company described. A noticeably weaker figure would suggest other pressures are at work. Just as important is any update on how long the pause lasts. Management originally framed it as about 180 days but conceded it could run longer, and an extended pause would weigh on fiscal 2027. Progress on the new VA performance work statement, a draft of which covered all six regions, would help clarify the longer-term economics of this franchise.
The second test is Medicaid community engagement, the work-requirement programs due to go live January 1, 2027. Last quarter, management admitted that state customer discussions were moving more slowly than hoped. It cited complexity in the federal interim rule and lingering litigation from state attorneys general. With the deadline now only weeks away, the company needs to show signed state contracts or firm commitments. Vague pipeline commentary will be harder to accept at this stage. SNAP payment accuracy work, which management said was moving faster than Medicaid, could serve as a partial offset if demos and meetings are turning into awards.
There are offsetting positives to verify. Management expected days sales outstanding to fall below 70 by the end of September, down from 78 earlier in the year, helped by a large catch-up in federal collections. Hitting that target would point to strong cash flow. The company also highlighted AI as a growing factor in its bids and margins, and defense and national security as an expanding market, citing recent Air Force and TSA wins. Investors will want evidence that these themes are producing contract awards, despite civilian procurement delays and bid protests. Management also said U.S. Services was firming toward mid-single-digit organic growth heading into next year, which gives the outlook another checkpoint.
Sentiment has improved from last quarter but remains bearish on balance. The shares trade above their 200-day moving average, near the upper part of their post-earnings range, though still about 7% below the recent high. Ultimately, the report hinges on whether the VA pause looks like a temporary dent or the start of a lower margin baseline heading into fiscal 2027.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Oct-19 | |
| Oct-08 | |
| Oct-05 | |
| Aug-06 | |
| Aug-06 | |
| Jul-09 | |
| Jul-06 | |
| May-07 | |
| May-07 | |
| May-07 | |
| May-07 | |
| Apr-24 | |
| Apr-11 | |
| Apr-09 |
