Post Holdings Faces FY27 Reckoning As Egg Windfall Fades And Deleveraging Takes Priority
Post Holdings has largely told investors how fiscal 2026 will end. The more consequential question for its fourth-quarter report is what comes next. Last quarter, management rebased the business to a comparable EBITDA figure of roughly $1.48 billion and said fiscal 2027 should be generally flat from there. That was a quieter way of saying the earnings power of the past year was flattered by temporary factors. This release is the first chance to see whether that rebased floor looks solid or already shaky.
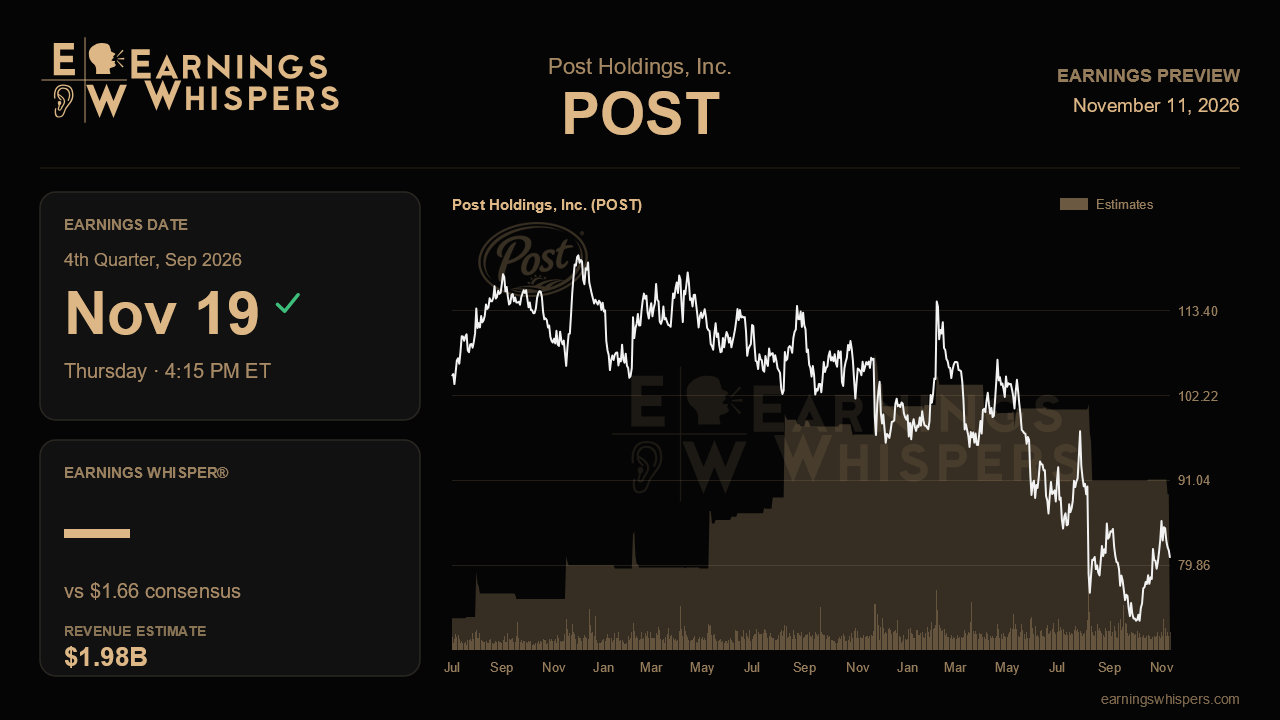
The Street expects earnings of $1.66 per share on revenue of about $1.98 billion. That would be a decline of roughly 21% in profit and 12% in sales from the year-ago quarter's $2.09 and $2.25 billion. Sequentially, the picture is closer to flat, since revenue came in at $1.95 billion last quarter with EPS of $1.78. Management narrowed its full-year adjusted EBITDA outlook to $1.56 billion to $1.57 billion, essentially the midpoint of the prior range. The fiscal 2026 guide began at $1.50 billion to $1.54 billion, so the year has drifted upward. With so little room left in the range, a fourth-quarter result in line with consensus would mostly confirm what management already signaled. The real surprise potential sits in the fiscal 2027 commentary.
Food service is the hinge. It was the reason last quarter landed a bit ahead of plan, but management cautioned that earnings there are normalizing toward a run rate of about $500 million as avian flu-driven egg conditions unwind. Yesterday's tailwind becomes next year's headwind. Investors should look for evidence that value-added egg conversions are sticking with customers, which would support the run rate. Faster erosion would put pressure on the flat outlook before fiscal 2027 even begins. The refrigerated retail business also slipped more than expected last quarter on higher fuel and freight costs and an unfavorable gap between market-priced and grain-based egg costs. Signs that this imbalance is easing would be welcome.
On the retail side, the narrative is about stabilization rather than growth. Cereal is improving slowly toward its long-run decline of 1% to 2%, compared with recent declines of about 2.5%. In pet food, share has steadied near 30%, and Nutrish began gaining share at the largest retailer. Still, the Nutrish relaunch has been messier than hoped, falling short of the flat-to-growth goal management set for this quarter. Nine Lives has also shown more price sensitivity than expected under competitive promotion. Management is now pursuing pet cost savings in earnest and closing two peanut butter plants, with those benefits arriving in fiscal 2028. Inflation is tracking toward the higher end of prior expectations, and pricing to offset it is weighted to the back half of fiscal 2027. That leaves a margin timing gap that a flat outlook has to absorb.
Capital allocation shifted as well. After three calls emphasizing aggressive buybacks, including a roughly 17% reduction in share count year to date, Post pivoted toward paying down debt as refinancing rates rose. Slower buybacks remove a lever that had supported per-share growth. The market has noticed. Shares are down 5.4% since the last report, trailing the S&P 500 by four points. At about $81, the stock sits well below its 200-day moving average near $91.48 and in the lower half of a post-earnings range of $71.45 to $87.33. That entire range sits beneath the prior quarter's trading band. Sentiment has tilted slightly more bearish than before the last report.
That skepticism lowers the bar, but it does not remove the central test. If Post can reaffirm a flat fiscal 2027 off the $1.48 billion base, show food service landing gently, and point to pet and cereal volumes at least holding steady, the rebasing will look like prudent conservatism. If the outlook slips again, the case for a stable staple compounder gets much harder to make.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Oct-22 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Aug-01 | |
| Jul-16 | |
| May-11 | |
| May-08 | |
| May-08 | |
| May-07 | |
| May-07 | |
| May-07 | |
| Apr-16 | |
| Mar-05 |
