Post Holdings Beats On Earnings, But Buybacks Masked An Erosion That FY27's Back-Half Bet Must Reverse
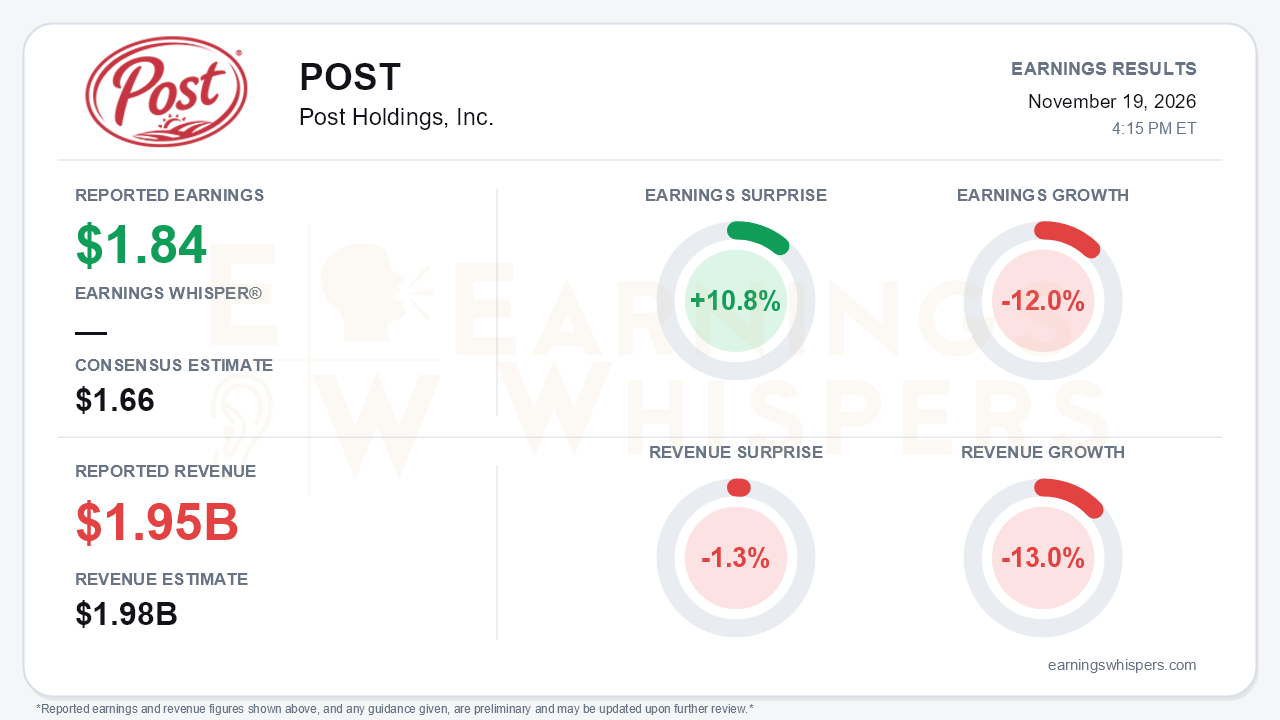
Post Holdings delivered a clean beat on the line investors watch most. Adjusted earnings of $1.84 per share topped the $1.66 consensus by 10.8%. Everything beneath it was softer. Earnings still fell 12.0% year over year. Revenue of $1.955 billion missed consensus by 1.3% and dropped 13.0%, about $138.5 million of it from divested pasta and Crystal Farms sales in the prior-year quarter. Management reaffirmed a flat fiscal 2027, guiding adjusted EBITDA to $1.45-$1.50 billion. That is the central tension: Post beat a lowered bar, but it is entering fiscal 2027 with more inflation, a weaker Foodservice run rate, a slower pet recovery and an unexpected leadership disruption than it carried a few quarters ago.
The quality of the beat deserves scrutiny. Adjusted net earnings fell to $92.6 million from $134.5 million. Per-share results held up better only because diluted shares shrank to 50.3 million from 61.2 million after Post spent $1.0 billion repurchasing 10.3 million shares in fiscal 2026 at an average of $98.37, well above today's price. GAAP EPS jumped to $1.68 from $0.99, but that largely reflects lapping a $29.8 million goodwill impairment and benefiting from $14.0 million of swap income. Adjusted EBITDA fell 11.0% to $378.4 million, though margin edged up to 19.4% from 18.9% as gross margin improved to 29.0%. Rising interest costs also weigh: net interest expense climbed to $424.7 million for the year, and net leverage stands at 4.7x.
The segment picture is uneven. Foodservice adjusted EBITDA dropped 24.5% to $121.6 million as the business lapped avian-influenza-driven pricing. That figure fell below the roughly $125 million quarterly run rate management cited earlier in the year, and the first quarter of fiscal 2027 is guided similar. On the call, management blamed freight and packaging costs and the loss of egg-market arbitrage. It added that record-low shell egg prices are pulling some customers away from value-added egg products. Post Consumer Brands was the bright spot on profit, with adjusted EBITDA up 3.6% on strong mix and premium cereal share gains. But that came despite a 9.9% volume decline excluding pasta, with pet food down 12.7% and cereal and granola down 4.4%. Refrigerated Retail EBITDA fell 35.5%, burdened by a $6.0 million litigation accrual and a 12.7% drop in sausage volume. Weetabix grew EBITDA 8.6%.
The call preserved a credible but increasingly back-loaded plan. The 8th Avenue integration synergies, which come from Post's acquisition of 8th Avenue Food & Provisions, exited fiscal 2026 at roughly a $20 million run rate, ahead of plan. Separate savings from closing two peanut butter plants come on top, with about a quarter landing in fiscal 2027 and most in fiscal 2028. Foodservice pricing arrives in the second fiscal quarter, and the cost-out pipeline at Post Consumer Brands is weighted to the second half. Nutrish base volumes improved from about -20% to high-single-digit declines. Still, management called pet stabilization more challenging than anticipated. That contrasts with earlier hopes for flat or slightly growing Nutrish volumes by the fourth quarter, as distribution losses continued and category promotional volume rose to about 25%. Inflation is running a little higher than management's prior view, with more commodity pressure expected mid-year, and pricing lags it.
The guidance carries its own wrinkle. The $1.45-$1.50 billion range sits below fiscal 2026's $1.569 billion, which reads like a decline. Management frames it as flat against a comparable base of about $1.48 billion after divestitures. Investors should accept that framing while recognizing that the phasing has shifted later, which raises execution risk. Capital allocation is also pivoting from buybacks to debt paydown because refinancing rates are higher. That removes the lever that propped up per-share results this year, even with free cash flow improving to $563.2 million. Layered on top, Chairman Rob Vitale is on leave and Jeff Fowler is interim chairman, shortly after Nicolas Catoggio's transition to CEO.
Investor sentiment remains negative but improved modestly, rising to -0.39 from -0.47 ahead of the report. The stock has not rewarded the company. Shares at $79.28 are down 7.2% since the open following the August report and sit 12.8% below the 200-day moving average of $90.89. Post repurchased stock as recently as November at $79.06, but the slower buyback pace removes a source of demand for the shares.
The bottom line is that Post beat on earnings per share but not on the trajectory of the business. Shrinking volumes, a reset Foodservice run rate, a stalled pet recovery and a leveraged balance sheet leave bears with legitimate ammunition. A flat fiscal 2027 now depends on second-half pricing and cost savings arriving on schedule, under interim board leadership and without aggressive buybacks to support per-share results.
Read our earnings preview for Post Holdings, Inc.: https://www.earningswhispers.com/article/POST/23184
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 9 hours | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-11 | |
| Oct-22 | |
| Aug-13 | |
| Aug-06 | |
| Aug-06 | |
| Aug-01 | |
| Jul-16 | |
| May-11 | |
| May-08 | |
| May-08 |
