Alvotech Misses On Revenue And Earnings As Supply Recovers But Full-Year Guidance Now Rides On A Record Q4
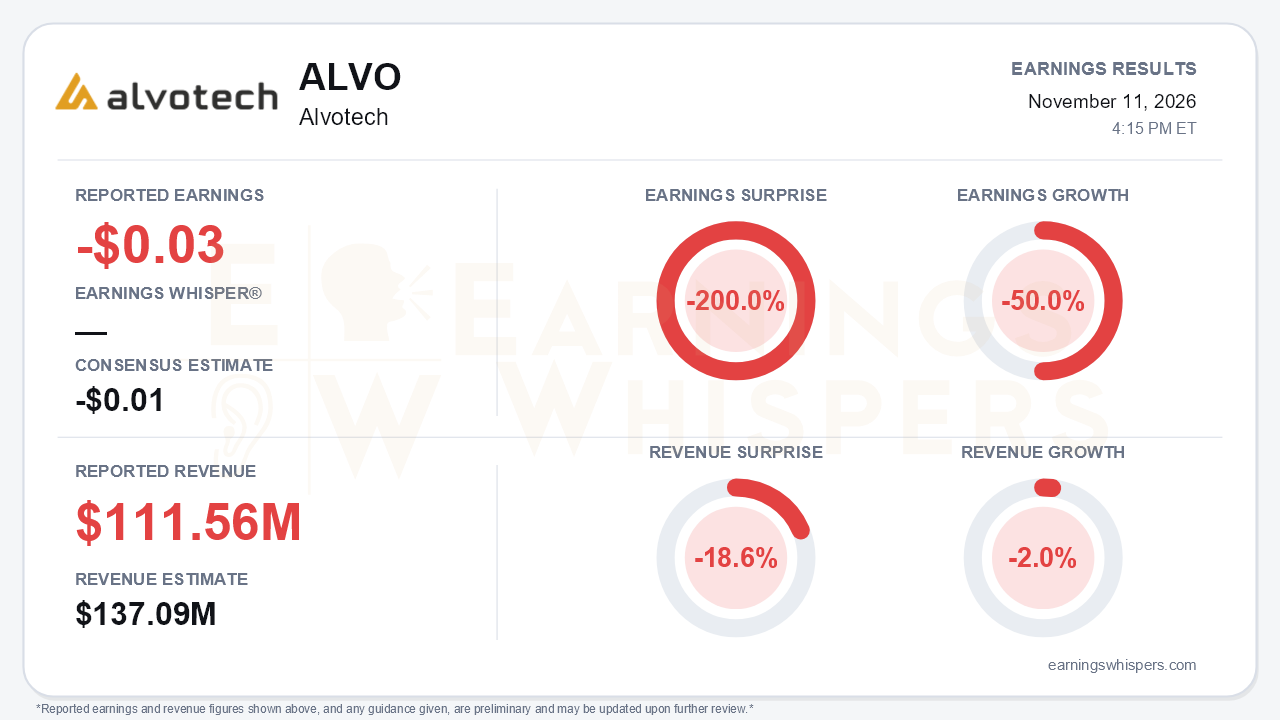
Alvotech (NASDAQ: ALVO) reported a third-quarter loss of $0.03 per share on revenue of $111.56 million, missing the consensus loss estimate of $0.01 by 200.0% and falling 18.6% short of the $137.09 million revenue consensus. Earnings fell 50.0% year over year and revenue slipped 2.0%. The company reaffirmed full-year 2026 guidance of $650-$700 million in revenue and $180-$220 million in EBITDA, but now expects results toward the lower end of both ranges. That is the central tension. The operational recovery from the first-half manufacturing problems is real and visible. But the year's financial targets now depend on a fourth quarter that would need to roughly equal everything the company has booked in the first nine months.
The revenue mix explains both the miss and the recovery. Product and service revenue rose 78% year over year to $58.2 million and 6% sequentially, extending the rebound from $51 million in Q1. That is evidence that supply is finally reaching customers. Licensing and other revenue, however, fell 34% to $53.2 million and offset nearly all of that gain. Gross margin improved to 54% from 51% in Q2 but remained far below the 69% of a year ago, and management said product margins will stay compressed through 2026. Adjusted EBITDA more than doubled to $31.5 million from $14.4 million, and reported EBITDA rose to $24.2 million. The quality of that improvement deserves scrutiny. Reported R&D expense fell to $17.2 million from $51.6 million a year earlier, so lower spending, rather than gross profit, drove much of the EBITDA gain.
The balance sheet is where bears have the most legitimate ammunition. Cash fell to $61.5 million from $143 million at the end of Q2 and $172.4 million at year-end. The decline came despite $164.6 million of gross equity proceeds and $113.7 million of new borrowings during the nine months. Q3 operating cash outflow was about $89 million, driven by a roughly $116 million working-capital build. Interest costs remain around $37 million per quarter, and management does not expect meaningful deleveraging until the second half of 2027. Nine-month interest paid was $109.1 million. Total equity remains negative at $267 million. Management reiterated its target of positive cash flow in Q4, but the CFO acknowledged capital would be secured if needed. A $20 million commercial provision also weighed on the period.
The call preserved a credible longer-term growth story. The company said:
- October FDA approvals for a second Simlandi drug-substance suite and an enhanced process have roughly doubled US drug-substance capacity and more than doubled output per batch.
- It expects its share of the US Humira biosimilar market to rise toward about 65% by year-end from above 60% in Q2.
- The Lotus deal for proposed biosimilars to Imfinzi and Hemlibra carries up to roughly $150 million in upfront and milestone payments and gives Alvotech its first direct US commercialization rights.
- The LOTTE Biologics partnership in Syracuse, New York, adds US manufacturing capacity alongside Fujifilm, which remains on track for 2H27.
Management called Q4 the strongest quarter in company history, cited a strong 2027 order book, and said 2027 EBITDA will improve substantially.
The near-term catalyst calendar is crowded and binary. AVT05, AVT06 and AVT03 have December FDA biosimilar user-fee goal dates. However, the US launch of AVT05 faces a pending J&J preliminary-injunction motion, and analysts questioned whether Teva will launch at risk, noting a 2027 framing from the partner. The US path for AVT29, the proposed biosimilar to Eylea HD, depends on a post-grant review challenge to a Regeneron patent, with a hearing on December 4. Hitting the low end of guidance requires roughly $327 million of Q4 revenue and about $102 million of EBITDA. That leaves little room for delivery timing to slip again.
Market positioning had improved heading into the print. Shares closed at $4.92, up 26.5% from the $3.89 open after the August report and about 17.2% above the 200-day moving average of $4.20. That snapshot reflects the stock before the market reacted to these results. Investor sentiment remained negative but improved modestly, rising to -0.41 from -0.45. Investors were warming to the turnaround but remained far from convinced. The Earnings Whispers trend readings are mixed, with price trend positive while AVWAP remains negative.
The bottom line is that Alvotech delivered a quarter in which operations improved while the financial setup became more fragile. Product revenue, gross margin and capacity all moved in the right direction. However, the revenue miss, the shift to the low end of guidance, and a sharp drop in cash leave the investment case resting on a few events in the next several weeks: a record fourth quarter, December regulatory decisions, and litigation outcomes on AVT05 and AVT29. The stock's run since August suggests investors had begun to price in the recovery. The quarter shows that the recovery still has to be converted into cash.
Read our earnings preview for Alvotech: https://www.earningswhispers.com/article/ALVO/22821
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-11 | |
| Nov-03 | |
| Nov-02 | |
| Oct-28 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Sep-16 | |
| Sep-16 | |
| Aug-31 |
