Alvotech Must Show Its Factory Is Back To Speed Before A Heavy Fourth Quarter
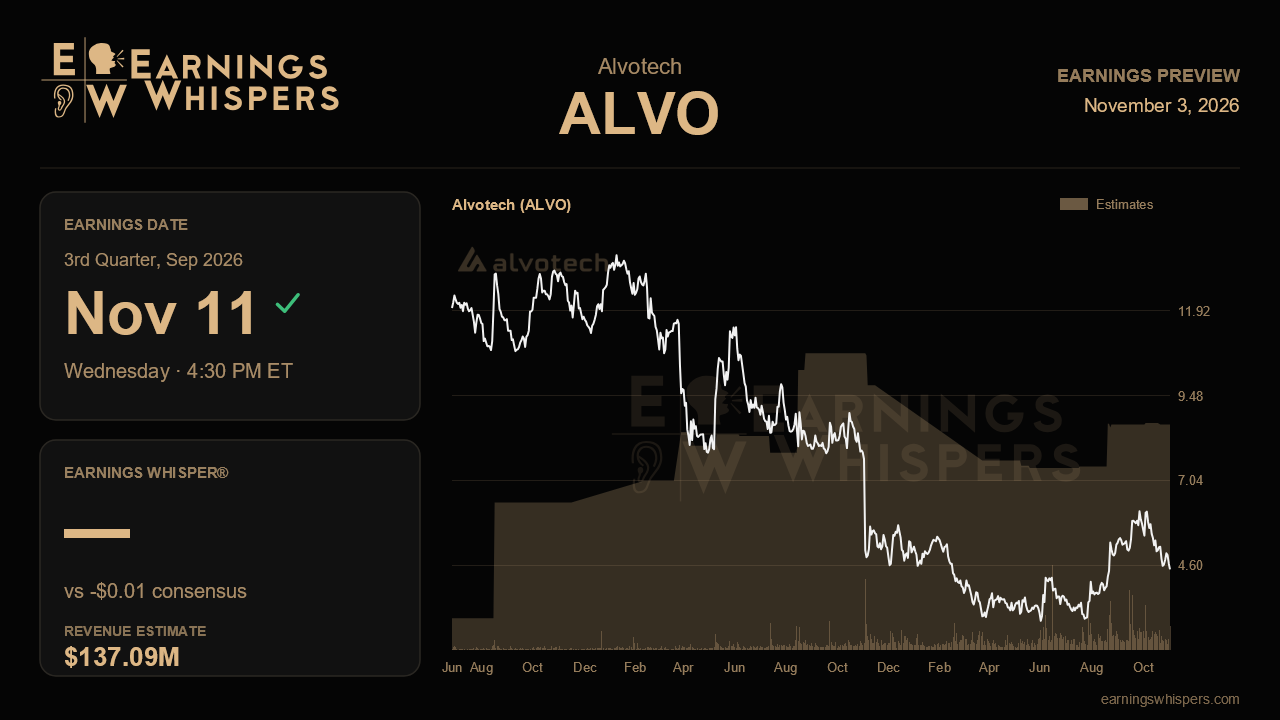
Alvotech enters its third-quarter report with its biggest regulatory cloud largely lifted and its financial statements still showing the bruises. Last quarter, management resubmitted four US applications, saw the FDA close its Reykjavik inspection with a manageable classification, and spoke with a confidence missing a year ago. The stock has rewarded that shift. The question now is narrower and more practical: did manufacturing throughput, which management deliberately slowed during the first half for facility improvements, actually recover once that work ended in June?
The Street expects a loss of about a penny per share on revenue of $137.1 million. That would be roughly 20% growth from the $113.9 million reported a year ago, and a jump of nearly 30% from the second quarter's depressed $105.9 million. It would also be a sharp improvement from last quarter's loss of 11 cents. Those figures already assume the factory is shipping again. A quarter that resembles the first half would undercut the idea that the weakness was self-inflicted and temporary.
The arithmetic of the full-year outlook is what makes this report matter. Alvotech has held its 2026 revenue forecast at $650 million to $700 million for three straight updates, without raising it. First-half revenue was about $212 million. Add the third-quarter consensus and the company would need roughly $300 million to $350 million in the fourth quarter to land inside its range. The full-year consensus of $663.8 million sits in the lower half of that band, implying a fourth quarter above $310 million. That is an extraordinary step-up, dependent on product shipments and on milestone payments that management has described as lumpy. A solid third quarter shrinks the leap; a soft one makes it look like a cliff, and any hesitation in reaffirming the range would be telling.
Margins are the clearest proof point. Gross margin slid to 51% in the second quarter from 57% in the first, and product margin fell to roughly 6%, both blamed on lower throughput. If the improvement program is truly behind the company, those figures should rebound meaningfully. Demand does not appear to be the constraint: US biosimilar penetration for adalimumab topped 60% and ustekinumab reached about 60% last quarter, while five products now contribute to sales. Evidence that higher output translated into shipments, particularly for the US Humira and Stellara biosimilars where supply limited share gains, would validate the story. Investors should also look for clarity on the undisclosed commercial provision booked last quarter and whether it recurs, along with the effect of roughly $37 million in quarterly cash interest on a cash balance of $143 million.
The forward catalysts remain mostly beyond this quarter. Decisions on the resubmitted US applications for the Simponi, Eylea and Prolia/Xgeva biosimilars fall around year end, as does a ruling in the US golimumab litigation. Updates on the Japanese golimumab launch, competitive pressure from a rival golimumab entrant, the first-mover Entivio program and the plan to sell selected products directly in the US will shape how much credit the market extends for 2027.
Sentiment has eased only modestly, to 42.4% bearish from 45.2%, even as shares rose 15.2% since the last report while the S&P 500 slipped 1.8%. At $4.48, the stock sits above its 200-day average of $4.21 but well below its post-earnings high of $6.53, suggesting enthusiasm has already cooled from its peak. Ultimately, this report must show that the manufacturing slowdown is truly over. If revenue and margins rebound on schedule, the back-loaded guidance looks ambitious but credible. If they do not, the recovery narrative starts to depend almost entirely on December approvals.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-02 | |
| Oct-28 | |
| Oct-20 | |
| Oct-20 | |
| Oct-14 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 | |
| Oct-05 | |
| Sep-16 | |
| Sep-16 | |
| Aug-31 | |
| Aug-27 | |
| Aug-24 |
