Pelagos Beats Handily On A War-Driven Premium Surge, But Slowing Growth And Pricing Pressure Complicate The Recovery
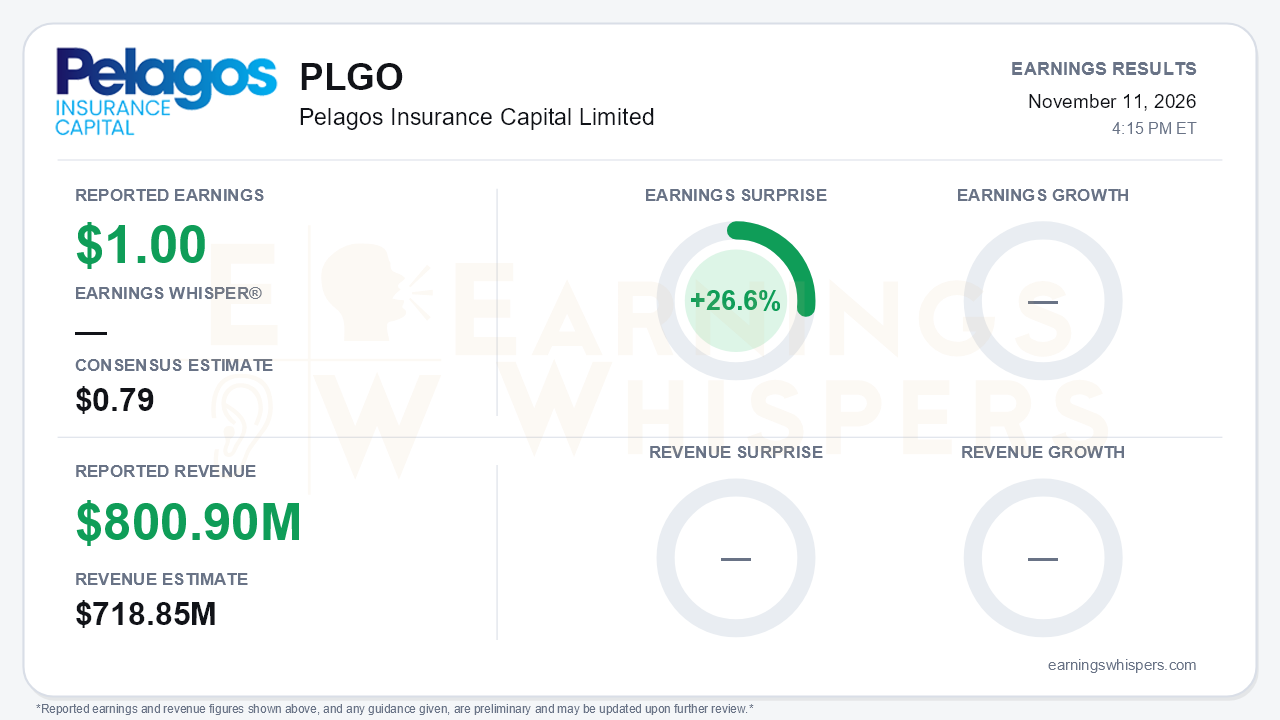
Pelagos Insurance Capital (NYSE: PLGO) delivered a clear beat in its first quarter under the new name. Operating EPS of $1.00 topped the $0.79 consensus by 26.6%, and revenue of $800.9 million exceeded the $718.85 million estimate by 11.4%. The bigger story is the sequential rebound. Annualized operating ROAE recovered to 15.3% from 5.1% in the loss-heavy second quarter, and the combined ratio improved to 91.5% from 99.5%. The year-over-year comparison is less flattering. Operating EPS fell from $1.21, GAAP EPS dropped to $0.74 from $1.24, and the combined ratio was 12.5 points worse than the unusually clean 79.0% of a year ago. That is the central tension: a strong recovery quarter that still sits below last year's earnings power, delivered while headline growth is cooling.
The quality of the beat deserves scrutiny. Much of the upside came from net premiums earned, which jumped to $783.7 million from $599.8 million. Insurance segment NPE of $634 million far exceeded guidance that had pointed to roughly Q2's $515 million. Management credited marine war breach business written after the Black Sea and Middle East conflicts, which is running below a 20% loss ratio. Those same conflicts also drove $115.9 million of catastrophe and large losses, and management acknowledged the full war book is running around a mid-40s loss ratio. In other words, the business is performing roughly to plan rather than adding meaningfully to profitability. Beneath the headline, several items softened:
- The Insurance segment's attritional loss ratio rose 6 points to 32.6%, which the company attributed to a benign prior-year comparison.
- Reserve development swung to $4.7 million adverse, driven by a political risk, violence and terror loss.
- GAAP results absorbed $27.4 million of investment losses, including a $15.7 million credit-loss provision and rate-driven mark-downs.
Growth is the other soft spot. Gross premiums written rose 5.3% to $839.8 million, extending a deceleration from 7% in Q1 and 6% in Q2. Insurance GPW grew roughly 13%. Reinsurance GPW fell to $153.7 million from $191.7 million after a single client restructured its program; management says reinsurance would otherwise have been flat and expects that premium to return in early 2027. Even so, management nudged full-year GPW guidance to the high end of mid-single digits and called Q4 the strongest growth quarter. It also pointed to similar or better growth in 2027, citing these supports:
- An expanding partner network, now 16 partners.
- Non-TFP partners contributing about 10% of year-to-date GPW, with a long-term target of 20-30%.
- A renewed Travelers whole-account quota share.
- A new U.S. quota share effective July 1.
The forward risks are real, and bears have legitimate ammunition. Management expects rate pressure in marine and political risk after a sizable market loss, and in property catastrophe after a benign natural-catastrophe year. That pressure would hit the lines that have powered recent returns. Q4 NPE guidance of $550-600 million for insurance and $85-105 million for reinsurance sits well below Q3 levels, partly for seasonal reasons. Net investment income also slipped to $44.6 million because buybacks have shrunk investable assets. Partly offsetting that, new money yields rose to 5.4% from 4.7%.
Capital management is the most tangible shareholder lever:
- The quarterly dividend rises to $0.22 from $0.15.
- The buyback authorization was replenished to $400 million.
- Year-to-date repurchases total $362.5 million, cutting shares outstanding to 79.3 million from 96.7 million at year-end. Management said the buybacks added $0.99 to book value per share.
Book value per diluted share ex-AOCI rose 11.9% to $27.11. GAAP book value of $26.60 was dented by rate-driven AOCI losses.
The market had already moved ahead of the print. Shares at $27.97 are up 14.4% since the open following the August report and sit about 14.5% above the 200-day moving average of $24.42. The stock now trades only modestly above ex-AOCI book value, and Q3 repurchases averaged $24.55 per share. Investor sentiment stayed negative and edged lower, from -0.117 to -0.158, a modest shift. That suggests the rally has not been matched by rising conviction, and investors remain wary of growth deceleration and softening rates.
The bottom line is that Pelagos produced a convincing sequential recovery and a decisive beat, backed by higher growth guidance and aggressive capital returns. However, the beat leaned on conflict-related marine premium that is not especially profitable on a full-book basis. Year-over-year earnings remain lower, premium growth keeps slowing, and management itself flagged pricing pressure in key lines. Execution on the partner network and the 2027 growth outlook will determine whether 15% operating ROAE is sustainable or a high-water mark.
Read our earnings preview for Pelagos Insurance Capital Limited: https://www.earningswhispers.com/article/PLGO/22836
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-11 | |
| Nov-03 | |
| Nov-03 | |
| Oct-06 | |
| Sep-14 | |
| Aug-25 | |
| Aug-17 | |
| Aug-12 | |
| Aug-03 | |
| Jul-09 | |
| Jun-05 |
Fidelis Partnership forms new Lloyds consortium to boost war cover
PLGO
Life Insurance International
|
| May-18 | |
| May-18 | |
| May-14 |
