Andersen Misses On GAAP Optics But Raises 2026 Guidance And Sets A 30% Growth Target For 2027 As Deal Activity Accelerates
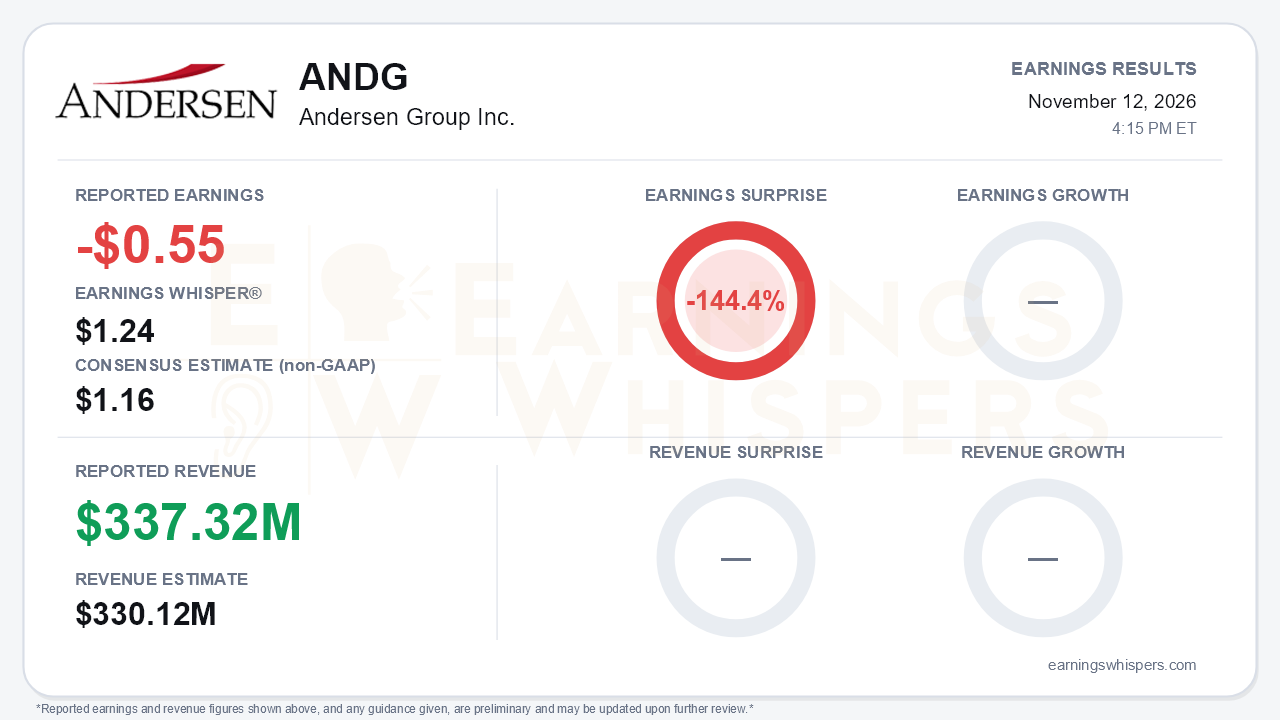
Andersen Group's third quarter produced one of the starkest gaps this season between the headline and the business. The company reported a GAAP loss of $0.55 per Class A share against a non-GAAP consensus of $1.16 and an Earnings Whisper of $1.24, a 144.4% shortfall. Revenue of $337.3 million beat the $330.1 million consensus by 2.2%. The miss reflects a mismatch in basis as much as a performance problem. Before allocations to noncontrolling interests, consolidated net income was $68.0 million. The per-share loss came from the post-IPO ownership structure, which assigns most earnings to noncontrolling interests, and from $47.5 million of equity-based compensation, including $40.4 million tied to Class X Aggregator Unit vesting. Investors who look past that structure saw a quarter in which guidance went up across the board.
The quality of the quarter still deserves scrutiny, because not every adjusted figure improved.
- **What held up:** Adjusted EBITDA rose 18.8% to $154.5 million, and the 45.8% margin was essentially flat with last year. Every service line and region grew. Business Services rose to $120.1 million from $93.9 million, and international contributed $10.7 million after contributing nothing a year ago.
- **What weakened:** Adjusted net income fell 8.3% to $115.7 million. Income tax expense rose to $31.6 million from $7.9 million, and interest expense rose to $5.7 million from essentially zero.
The operating engine is intact, but the public-company capital structure now takes a much larger share of profit before it reaches shareholders. Alternative Investment Funds was the laggard, growing only modestly to $27.9 million.
Growth decelerated on the headline. Third-quarter revenue growth of 18.7% followed 23.7% in the second quarter, although Q3 is the company's seasonally largest quarter and the comparisons differ. Underneath, the call described healthy demand:
- Organic growth was roughly 15%.
- Revenue per person rose 14.6% and revenue per hour rose 8.6%.
- Year-to-date client groups were up 24% and engagements up 21%.
The softer points came from management itself. The CEO flagged productivity growth of only about 4%. The 3% technology surcharge is now in the base, so pricing in 2027 must hold up without that one-time lift.
Guidance was the bigger story. This was the third raise to the 2026 outlook:
- **2026 revenue:** now $990 million to $1.01 billion, up from $980 million to $1 billion.
- **2026 adjusted EBITDA:** now $255 million to $275 million, up from $225 million to $250 million, a sizable step.
- **2027 initial outlook:** revenue of $1.275 billion to $1.325 billion, about 30% growth at the midpoint, and adjusted EBITDA of $320 million to $340 million. Management called these targets conservative.
The swing in M&A tone was the most important change from last quarter. In Q2, management said deals were slipping and cut its 2026 inorganic revenue estimate to $25 million to $30 million. This quarter:
- Management cited 24 deals signed since March, with 16 closed and the rest expected by the end of Q1 2027.
- The CFO called the $25 million to $30 million estimate "on the low side."
- The expansion team was converted into an integration team, and the CEO met with 41 firms in October.
The eight deals closed through September cost about 0.67 times acquired revenue.
That acceleration also carries the main risks. Management said acquired firms run at 15% to 25% margins, well below the organic business, so a growing M&A mix will dilute margins. The planned expansion of the 2027 EBITDA margin depends on the organic business offsetting that drag. Private equity buyers are bidding up multiples, with one offer cited at 16 times EBITDA against Andersen's 10 to 12 times. Integrating firms across many new countries will strain deal-team capacity. On the balance sheet:
- Cash fell to $193.6 million from $250 million at year-end.
- $287.7 million of related-party notes remain outstanding.
- A $74.4 million tax receivable agreement liability was recorded.
- Partner selling through secondary offerings adds to share supply.
The market had largely priced in the improvement before the report. Shares rose 45.1% from the open after the August report to $65.84. That leaves the stock about 61% above its 200-day moving average and less than 4% below the $68.41 52-week high set on November 5. Management noted that the rally, from about $23 to about $65, has strengthened the stock as an acquisition currency. Investor sentiment moved from -0.17 to roughly neutral at -0.01. That is a meaningful improvement, but skepticism has faded rather than turned into enthusiasm. Momentum and AVWAP trend readings are positive, consistent with the strength in the share price.
The bottom line is that Andersen's GAAP miss says more about its post-IPO accounting than about its business. Revenue beat, adjusted EBITDA margins held, 2026 guidance rose again, and the 2027 outlook implies about 30% growth. The tension lies elsewhere: growth is slowing on the headline, adjusted net income fell, and the plan increasingly depends on acquisitions that carry lower margins and real integration risk. With the stock near its high and well extended above long-term trend, the market now expects Andersen to deliver on a much more acquisition-heavy plan.
Read our earnings preview for Andersen Group Inc.: https://www.earningswhispers.com/article/ANDG/22908
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-04 | |
| Nov-04 | |
| Nov-02 | |
| Oct-26 | |
| Oct-19 |
Andersen Group expands global footprint with four consulting buyouts
ANDG
International Accounting Bulletin
|
| Oct-15 | |
| Oct-13 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Sep-01 |
