CMCT's Bay Area Rent Rebound Faces Its Proof Point As Revenue Forecasts Slide
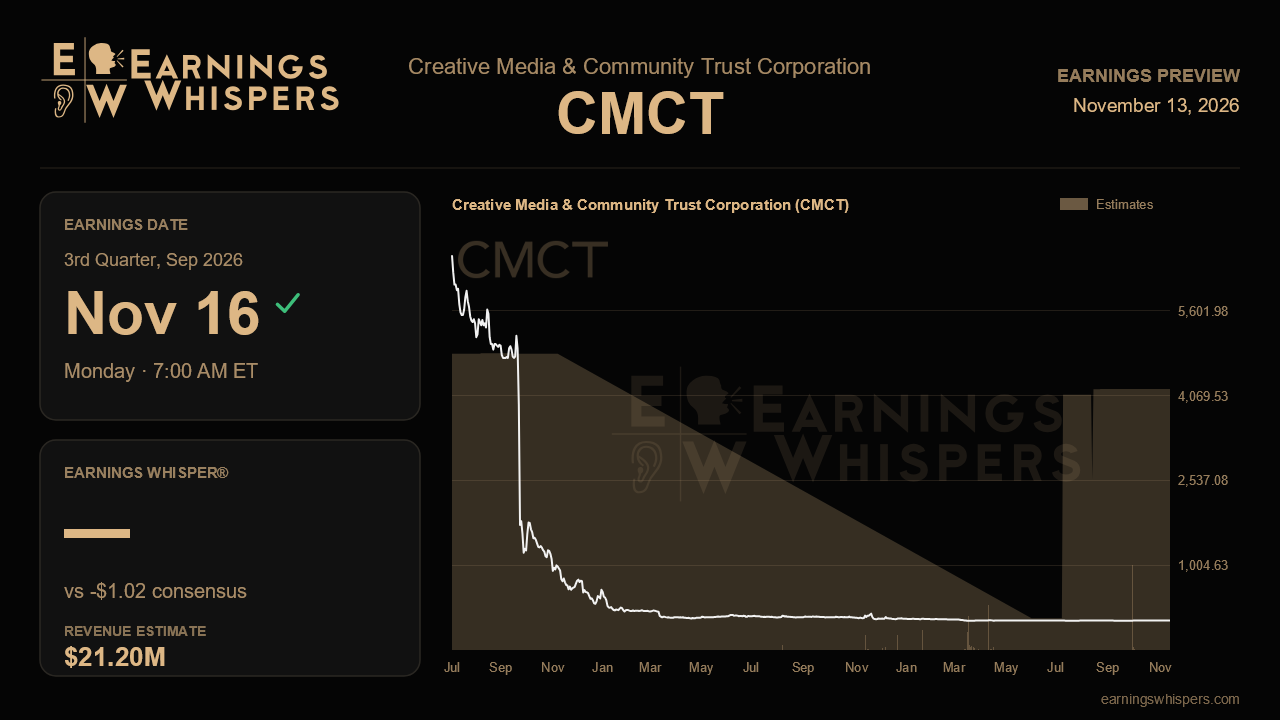
Creative Media & Community Trust spent its last conference call sounding like a company that had finally stopped repairing its balance sheet and started growing again. Multifamily occupancy surged, San Francisco rents were climbing at their fastest pace in a generation, and the redemption of $243 million in preferred stock was beginning to show up in funds from operations. The upcoming third-quarter report, due before the open on November 16, has to show that this turn is durable, and it has to do so against a revenue forecast that points sharply lower.
Wall Street expects a loss of $1.02 per share, an improvement from the $1.25 loss last quarter and a dramatic narrowing from the $13.96 loss a year ago. That 92.7% year-over-year improvement mostly reflects how deep the hole was during the period of heavy preferred dividends and hotel renovations. The revenue picture is less flattering. Consensus calls for $21.2 million, down 19.2% from a year ago and well below the $29.7 million reported last quarter. The company does not issue formal guidance, so there is no management range to measure that against. The size of the sequential drop is the first question to resolve. Investors will want to know whether it reflects an asset disposition, a change in how properties are consolidated, or something weaker in the operating base. An explained structural change would be digestible. An unexplained decline would undercut the growth story management has been building.
The heart of that story is Bay Area multifamily. Same-store occupancy climbed to roughly 95% to 96% last quarter from below 90% a quarter earlier. 701 South Hudson reached 94.1% and 1915 Park reached 58.3%. With in-place rents running about 12% below asking, the next leg should come from pricing rather than filling empty units. Validation would look like stable occupancy alongside visible rent roll-up and continued lease-up at 1915 Park. Occupancy that slips back, or rent growth that fails to show up in multifamily NOI, would suggest the easy gains are already banked.
The hotel and the FFO bridge are the other supports. Hotel NOI recovered to $4.6 million after renovations, and management is pursuing a Sheraton Grand refinancing that could raise the loan balance and lower the spread. Core FFO improved to a $3.4 million loss from $5.9 million as preferred dividends fell. This quarter should carry the full benefit of the redemption, so another step toward breakeven is the minimum expectation. Progress on the refinancing, the potential asset sales aimed at closing the gap to net asset value, and the 50-unit development at 701 Hudson would all add credibility.
The risks are concentrated in office. Ex-JV office occupancy has drifted down for three straight quarters to 84.4%, and leasing volume was thin. The Oakland office non-recourse mortgage that matured in early July was unresolved at last report. A clean resolution, even a handback, would remove an overhang, while a lingering default would keep it in view. Non-cash fair-value markdowns at joint ventures also dragged reported segment NOI last quarter and could again obscure underlying progress.
Sentiment has softened from extreme pessimism. Readings were 93.2% bearish heading into last quarter and are now 46.2% bearish. The stock has not followed, though. Shares are down 5.9% since the last report, trailing the S&P 500 by about 3 points. At $4.99 they sit well below the 200-day average of $7.29. They trade in the upper part of a volatile $1.78 to $5.76 post-earnings range but are not pressing that high. The market has heard the turnaround pitch and is waiting for numbers.
Ultimately, this report hinges on whether multifamily and hotel gains can keep pushing core FFO toward breakeven while the revenue decline and the Oakland maturity prove to be explainable, contained issues rather than signs of a weaker foundation.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Sep-29 | |
| Aug-14 | |
| Aug-14 | |
| Aug-14 | |
| Aug-12 | |
| Jun-24 | |
| Jun-01 | |
| May-08 | |
| May-08 | |
| May-06 | |
| Apr-15 | |
| Mar-27 | |
| Mar-23 |
