CMCT Misses On Core FFO As Hotel And Bay Area Multifamily Gains Collide With The Oakland Office Default
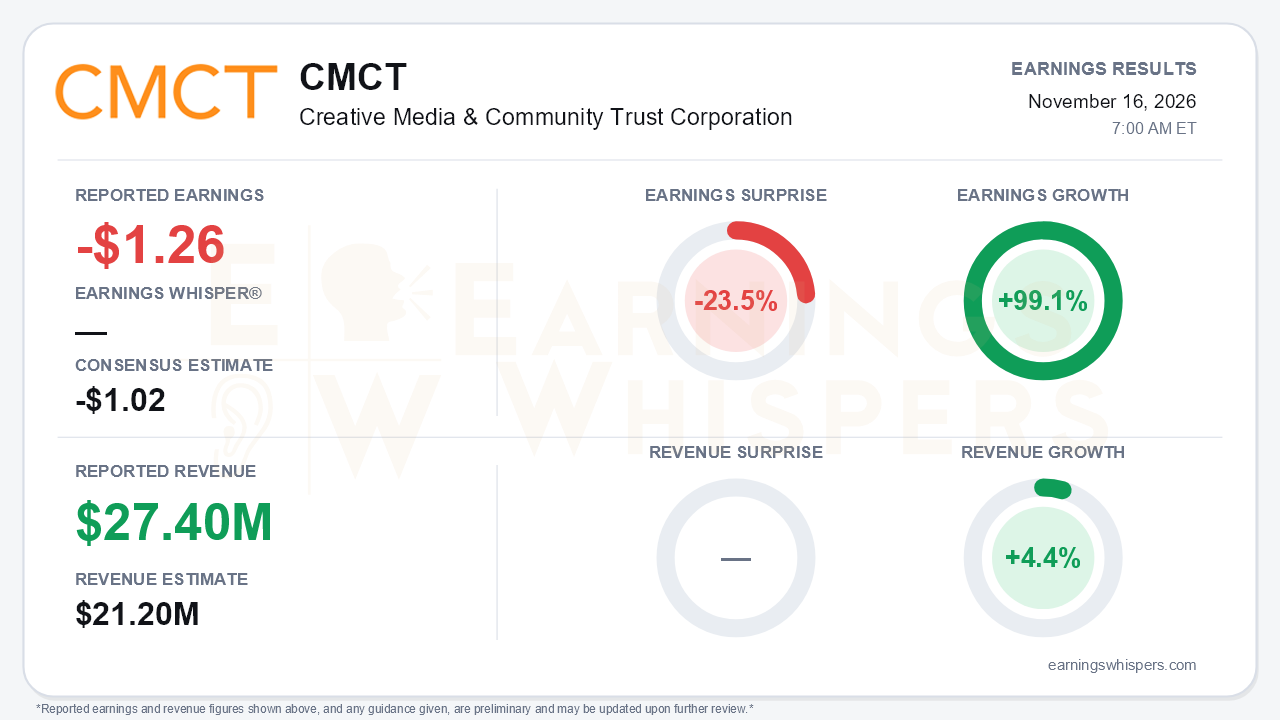
Creative Media & Community Trust (NASDAQ: CMCT) delivered a quarter in which property operations improved sharply but per-share results did not. The REIT reported a Core FFO loss of $1.26 per share, missing the -$1.02 consensus by 23.5%. Revenue of $27.4 million beat the $21.2 million consensus by 29.2% and grew 4.4% year over year. The 99.1% year-over-year earnings improvement is real in dollar terms. The Core FFO loss narrowed from $10.5 million to $3.8 million. However, the per-share comparison is heavily distorted by two 1-for-10 reverse splits and the issuance of millions of common shares to redeem preferred stock. The central tension is that segment NOI posted its strongest growth of the year, yet Core FFO actually slipped from Q2's $3.4 million loss. Defaulted Oakland office debt and the cost of the recapitalization absorbed the operating gains.
The quality of the improvement deserves scrutiny. Most of the $6.7 million year-over-year Core FFO gain came from a $4.3 million drop in preferred dividends rather than from the properties. Segment NOI contributed $3.8 million. The revenue line is also less clean than the surprise implies. Hotel income rose 36% to $9.9 million and rental income edged up 4%. Interest and other income, by contrast, fell from $2.8 million to $0.7 million after the sale of the lending business. On a GAAP basis, the net loss attributable to common stockholders widened to $19.1 million, or $6.29 per share, from $17.7 million. That deterioration was driven by $8.0 million of impairments on Austin and San Francisco office assets and a higher tax provision. The single most damaging item was Oakland. The $97.1 million non-recourse mortgage on that office building matured in July without a refinancing, and the stepped-up default interest rate cut Core FFO by $1.6 million. Without that drag, the sequential trend would have looked meaningfully better.
Beneath the noise, the operating story genuinely strengthened. Segment NOI reached $10.8 million, up from $7.0 million a year ago and $9.3 million in Q2. The renovated Sheraton hotel drove hotel NOI to $2.8 million from $850,000. RevPAR rose to $153.13 from $133.92 on higher occupancy and rates, and 2027 group bookings are running more than 20% ahead of last year. Multifamily NOI reached $2.1 million versus $792,000 a year earlier and $638,000 in Q2. Bay Area market rents are accelerating: San Francisco is up about 13% and Oakland about 10.8%, both described as 25-year highs. As a result, the gap between CMCT's in-place Bay Area rents and asking rents widened to roughly 17% from about 12% in Q2. That gap gives the company a multi-year runway to raise rents as leases roll, though it will take a couple of years to capture. In Los Angeles, lease-up also progressed, with 1915 Park at 66.7% leased versus 58.3% in Q2.
Office remains the weak flank. Office leasing volume improved to 59,400 square feet from roughly 16,000 in Q2, including an extension of the second-largest tenant to 2034. Even so, the leased rate excluding Oakland fell 140 basis points year over year to 85.2%, down from 88.5% at year-end 2025. Rent per occupied square foot also slipped to $58.35 from $60.22. Multifamily occupancy has plateaued around 95-96%, and the 50-unit Hudson project start slipped to next year.
The forward agenda is about balance-sheet execution. Positives include $27.1 million of corporate debt not due until 2035 and planned refinancings of the hotel and both Bay Area multifamily assets, with the hotel loan expected to be upsized at a lower rate. Several office and residential assets are being marketed for sale. Bears have legitimate ammunition, however. Cash fell to $9.3 million from $15.4 million at year-end. Management also flagged a need to raise liquidity to handle preferred redemption requests, while rising Treasury yields and a wide office bid-ask spread could complicate sales. The company no longer intends to force further preferred conversions, which should slow dilution. Common shares outstanding nonetheless rose to 3.26 million from about 27,000 at year-end.
Investor sentiment improved substantially, moving from deeply negative at -0.93 to -0.42, though it remains firmly in negative territory. The stock has been extraordinarily volatile. It plunged to $1.78 in late September, rebounded to $5.76 in October, and ended at $4.99, down 5.8% from the open after the prior report and roughly 30% below its 200-day moving average. Momentum and AVWAP trend readings have turned positive, consistent with the sharp rebound off the lows.
The bottom line is that CMCT's properties are finally producing the NOI growth the repositioning promised, led by the hotel and Bay Area apartments. That progress is not yet translating into common-shareholder earnings, which remain burdened by Oakland's default interest, office softness, impairments, and the liquidity demands of the remaining preferred stock. The coming refinancings and asset sales will determine whether operating gains reach the bottom line.
Read our earnings preview for Creative Media & Community Trust Corporation: https://www.earningswhispers.com/article/CMCT/23186
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-16 | |
| Nov-13 | |
| Nov-12 | |
| Sep-29 | |
| Aug-14 | |
| Aug-14 | |
| Aug-14 | |
| Aug-12 | |
| Jun-24 | |
| Jun-01 | |
| May-08 | |
| May-08 | |
| May-06 |
