OptimumBank Beats Again And Raises Its Earnings Run-Rate, But Dilution And Pricier Funding Weigh On Sentiment
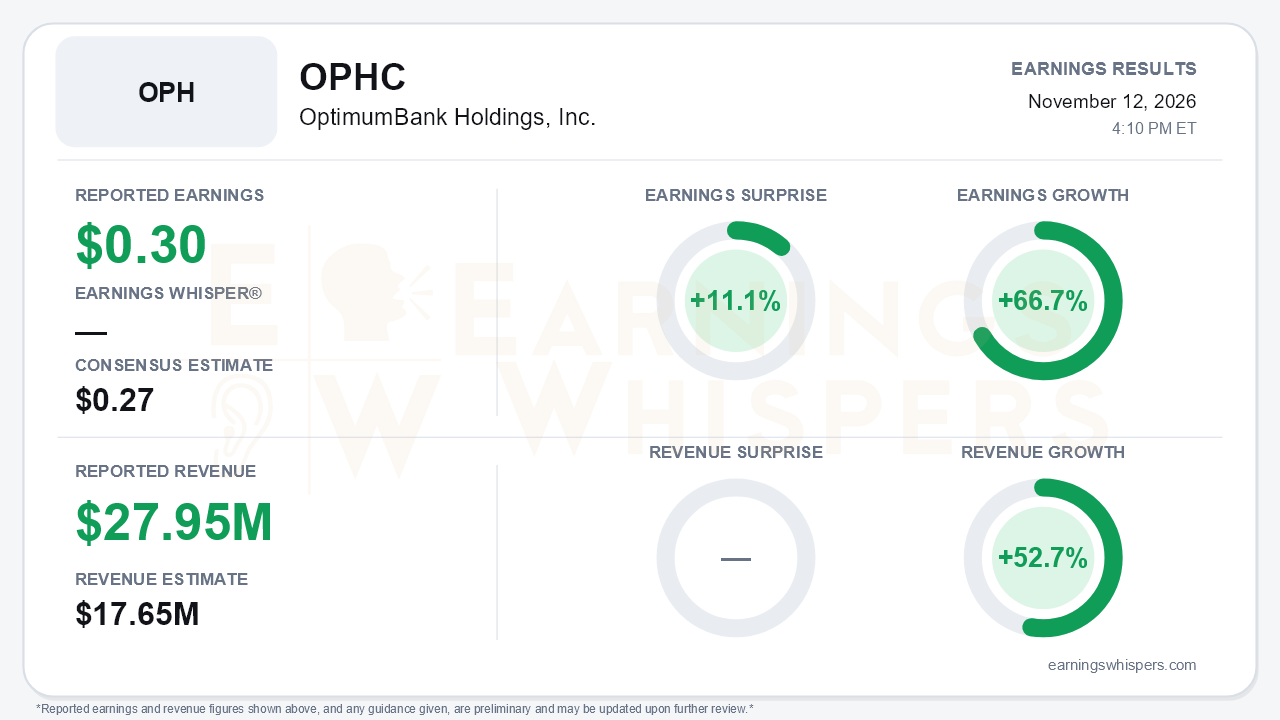
OptimumBank Holdings delivered its third consecutive record quarter, earning $0.30 per share against a $0.27 consensus, an 11.1% surprise, and growing earnings 66.7% from a year ago. Revenue of $27.95 million topped the $17.65 million consensus by 58.3% and rose 52.7% year over year. Net income reached $7.2 million, up from $6.7 million in the second quarter and $4.3 million a year earlier. On the call, management framed its forward run-rate as $10 million to $12 million of quarterly pre-tax, pre-provision earnings, or roughly $48 million to $50 million a year. That continues a pattern of raising the earnings bar each quarter. The central tension is that the bank is growing faster than it can fund internally. Each step up in earnings power now comes with more expensive non-deposit funding and steady dilution, and investors appear to have noticed.
The quality of the quarter is better than average for a fast-growing small bank, but it is not pristine. Pre-tax, pre-provision earnings jumped to $10.6 million from $8.8 million, and net interest income rose $2.1 million sequentially to $16.8 million on $150.2 million of loan growth. The efficiency ratio improved to 45.86% from 48.78%. Two factors flattered the headline, however:
- Noninterest income included $0.9 million of late fees from the payoff of a nonaccrual loan, which should not be expected to recur.
- Credit loss expense of $1.1 million replaced a small reversal last quarter, so the bottom line absorbed a real provision this time.
On a GAAP basis, profitability actually slipped slightly. ROAA was 1.95% versus 2.04%, and ROAE was 19.99% versus 20.34%. Management's 29.6% "core" ROAE on the call is a different measure from the reported GAAP returns, and investors should keep the two separate. Sequential EPS growth also slowed to about 7%, after the jump from $0.20 to $0.28 last quarter.
Beneath the headline, the margin story is more nuanced than the 6-basis-point NIM expansion to 4.63% suggests. Asset yields rose 17 basis points, helped by loans yielding 7.40%. But the cost of interest-bearing liabilities jumped 19 basis points to 3.49%, and the net interest spread narrowed to 3.43% from 3.45%. The increase came mainly from OptimumFinance's 10% notes and the new 7.50% subordinated debt. Excluding those, funding costs rose only four basis points. Deposit growth itself was strong: noninterest-bearing deposits rose 19.5% in the quarter. Even so, the loan-to-deposit ratio crept above 100%, and tangible common equity to tangible assets has drifted down to 9.48% from 10.79% a year ago.
The forward catalysts are substantial:
- **Loan growth:** The pipeline sits near $700 million, and the 2027 budget assumes $500 million to $600 million of loan growth.
- **Healthcare lending:** OptimumFunding's healthcare unit has $41 million closed and $80 million of approved term sheets expected to close next quarter, with a HUD license targeted for 2027.
- **Cheaper funding:** OptimumFinance, now about $27 million at roughly 19% yields, is lining up warehouse funding at SOFR plus 250-275 basis points, which would be cheaper than its 10% notes.
- **Cost savings:** New CEO Moishe Gubin identified $0.6 million to $1.0 million of annual savings and expects technology-driven headcount reductions in 2027. Noninterest expense still rose to $9.0 million from $8.4 million.
Bears have legitimate ammunition. A $25.4 million private placement closed after quarter end, roughly $50 million more equity is expected in 2027, and no dividend is planned. Commercial real estate is up about 50% year to date and now approaches $1 billion of the $1.37 billion book. Management also expects the allowance, currently 0.89% of loans, to rise.
That backdrop helps explain one of the sharpest sentiment reversals one could see. Investor sentiment collapsed from a strongly positive 0.78 to -0.21, despite a beat and a higher run-rate. The likely culprit is positioning rather than fundamentals. Shares have climbed 48.1% from the $6.05 open after the July report to $8.96 and sit 31.8% above the 200-day moving average. They remain 16.1% below the $10.68 52-week high set on August 17, days before the subordinated debt deal. The stock has already given back a meaningful part of that spike. The Earnings Whispers trend readings remain mostly constructive, with sequential growth and AVWAP positive while the price trend has cooled to neutral.
The bottom line is that OptimumBank's operating engine keeps improving. Loans, deposits, net interest income and pre-provision earnings all moved higher, credit stayed clean, and management again raised its earnings framework. What has changed is the cost of that growth: higher-cost borrowings, rising provisions, heavy CRE exposure and a steady stream of new shares. After a near-50% run, the debate has shifted from whether the bank can grow to how much per-share value survives the capital needed to finance it.
Read our earnings preview for OptimumBank Holdings, Inc.: https://www.earningswhispers.com/article/OPHC/23034
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 8 hours | |
| Nov-12 | |
| Nov-08 | |
| Nov-05 | |
| Aug-13 | |
| Aug-06 | |
| Jul-24 | |
| May-19 | |
| May-18 | |
| May-05 | |
| Apr-27 | |
| Apr-24 | |
| Apr-20 | |
| Apr-10 |
