Inter&Co's Record Profit Comes With A Slower Growth Reset As Shares Sit Far Below Trend
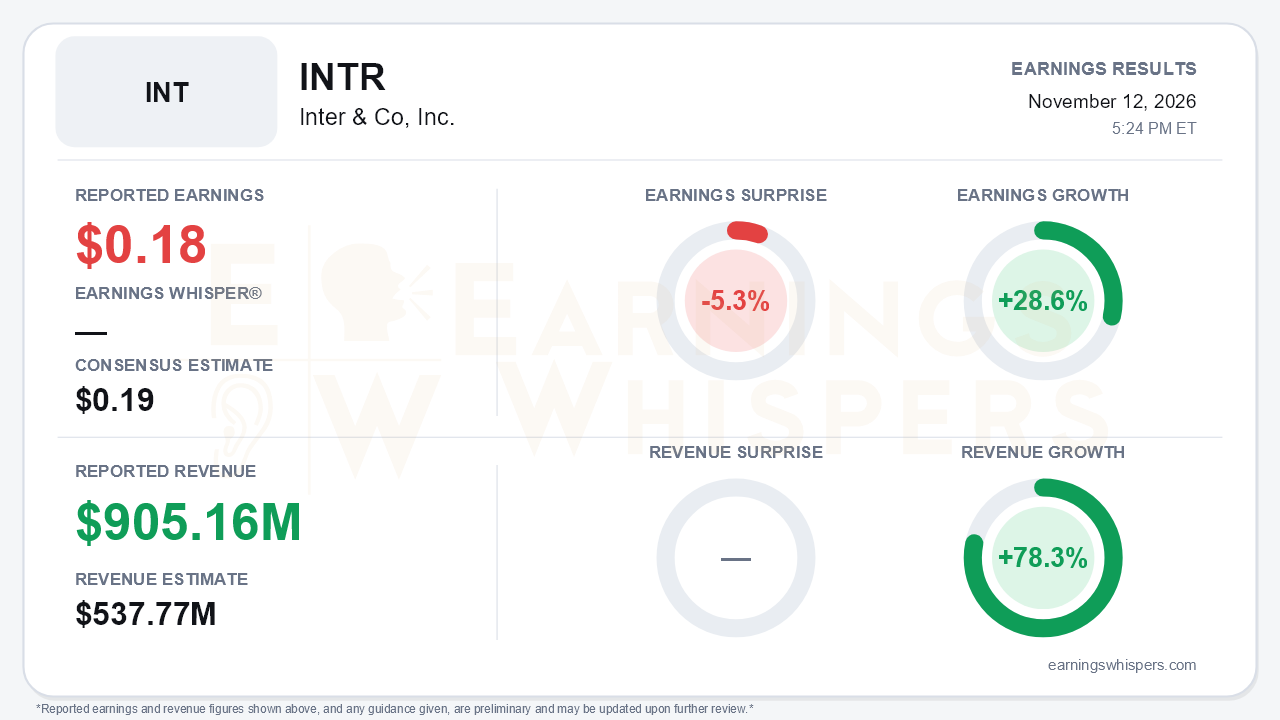
Inter&Co delivered its 14th consecutive quarter of net income growth, but the third quarter was less about the record and more about the reset that came with it. The Brazilian digital bank reported earnings of $0.18 per share, 5.3% below the $0.19 consensus, even as EPS grew 28.6% year over year. Net income reached a record R$425 million (US$76.1 million), up 26% from a year ago. On the call, however, management stepped forward loan growth down to 20-25%, below the roughly 30% pace it emphasized earlier in 2026. That is the central tension. Inter is becoming more profitable and more efficient, but it is doing so on a slower growth trajectory and against a higher credit-cost baseline than investors were promised at the start of the year.
The revenue picture needs careful reading. Earnings Whispers' normalized revenue of $905.16 million beat the $537.77 million consensus by 68.3% and grew 78.3% year over year. The company's own release, however, puts net revenue at US$483 million (R$2.7 billion), up 26%. The gap points to different revenue definitions, gross versus net, rather than a blowout quarter. Investors should anchor on the 26% net revenue growth as the operating trend. By that measure, the quarter was solid but not exceptional, and the EPS shortfall is the more telling comparison.
Beneath the headline, the profitability metrics genuinely improved:
- **Net interest margin:** NIM reached 9.96%, up from 9.54% in the first quarter and about 70 basis points above a year ago. It held up even though lower inflation (IPCA of 2.3% versus 5.8% in 2Q26) reduced income on inflation-linked real estate assets.
- **Efficiency:** The efficiency ratio improved to 41.9% from 45.2% a year earlier, as expenses grew 17% against 26% revenue growth.
- **Returns and client metrics:** ROE climbed to 15.8% from 14.2%. Net ARPAC hit a record R$35.6, and margin per active client reached a record R$22.3.
- **Capital:** CET1 at Banco Inter rose 70 basis points sequentially to 12.2%, showing the bank is generating capital while it grows.
The weaker side of the ledger is just as concrete:
- **Momentum:** Net income grew only about 1% sequentially, and margin per active client was roughly flat quarter over quarter.
- **Loan growth:** It decelerated to 25% from 33% in the first quarter.
- **Fees and cards:** Fee income growth slowed to 13% from 18%. Card growth fell to 18% from 27% in 1Q and 30% a year ago, as management deliberately pulled back on unsecured cards, BNPL and overdraft.
- **Funding:** Cost of funding rose to 70% of CDI from 64% in 1Q, reflecting a shift toward higher-yielding deposits at elevated SELIC rates.
- **Credit costs:** Management now frames steady-state cost of risk at about 6%, versus the 5-5.5% expected at the start of 2026. NPL 90+ rose to 5.3%.
The release describes cost of risk as "stable" at 5.9%. That is accurate quarter over quarter, but it is stable at a level higher than earlier targets.
There are credible offsets. Leading asset-quality indicators improved: 15-90 day NPLs eased to 4.2% from 4.5%, and NPL formation slipped to 1.74% from 1.83%. Private payroll lending, a source of earlier concern, showed real operational progress. Automatic relinkage now covers about 30% of the delinquent balance and credit insurance penetration is near 40%, which cut that product's NPL formation to 3.2% from 4.9%. CFO Santiago Stel said he expects continued improvement there as the product matures.
Management also pointed to several forward catalysts:
- operating leverage gains in 2027;
- a possible re-acceleration in credit cards early in 2027;
- a reorganized leadership team, including a new Chief Growth Officer and Alexandre Riccio moving to COO focused on underwriting;
- an AI vendor partnership with SpaceX AI/xAI, which carries no revenue share.
The risks are mostly macro. Brazilian household leverage is deteriorating, and lower inflation dampens NII on the real estate book. Fourth-quarter expenses are seasonally higher, and D&A is up 38% year over year.
The market had already priced in plenty of doubt. Shares have fallen 27.5% from the $5.47 open after the August report to $3.97, roughly 39.7% below the 200-day moving average of $6.58. The Earnings Whispers price and AVWAP trend readings both remain negative. Investor sentiment remains negative but improved meaningfully, rising from -0.39 to -0.28. That suggests expectations had become depressed enough that a lower growth framework was partly anticipated.
The bottom line is that Inter delivered a higher-quality, more profitable franchise in a quarter that also formally lowered its growth ceiling. Bears have legitimate ammunition in the EPS miss, flat sequential earnings, a 6% cost-of-risk anchor and rising funding costs. Bulls can point to record margins, improving efficiency, stronger capital and better leading credit indicators. With the stock deeply below its long-term trend, the debate now hinges on whether 20-25% loan growth with expanding returns is enough to rebuild confidence.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Aug-26 | |
| Aug-18 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-23 | |
| Jul-13 | |
| Jul-02 | |
| Jun-08 | |
| May-11 | |
| May-07 | |
| Apr-07 | |
| Mar-30 |
