After A 32% Slide, Dycom Must Prove Its Communications Margin Dip Was Temporary
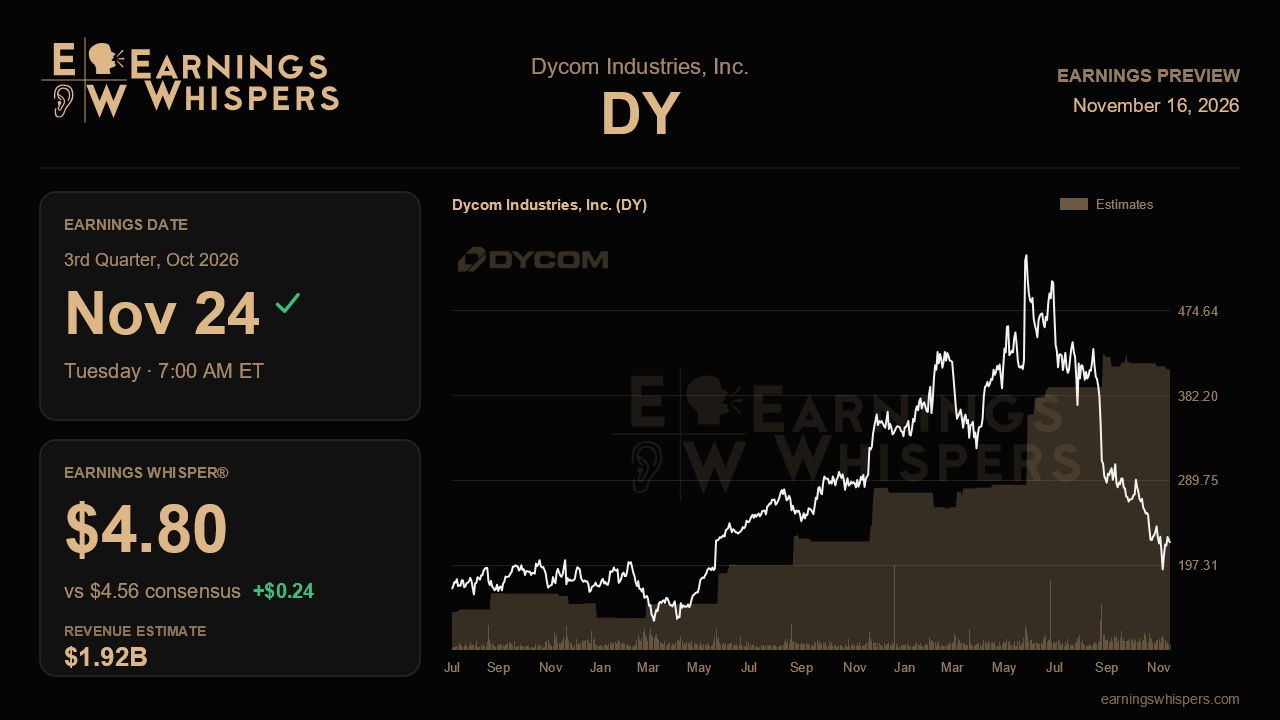
Dycom Industries heads into its fiscal third-quarter report with an awkward split between its operations and its stock. Last quarter the company posted record revenue, record backlog and a net increase to full-year guidance. Since then, shares have dropped about 32% while the S&P 500 slipped only 1.4%. That leaves the stock near $222, well below its 200-day moving average of roughly $371 and much closer to the post-earnings low of $186 than the high of $332. The market has clearly discounted something, and the November 24 report should show whether that skepticism was justified.
The Street expects non-GAAP earnings of $4.56 a share on revenue of $1.92 billion. Revenue at that level would be up about 32% from $1.45 billion a year ago. Earnings would be up roughly 26% from $3.63. That is strong growth, but much of it comes from acquisitions. Management's full-year outlook implies about 36.5% total growth but only 11.3% organic. The EPS consensus sits exactly at the midpoint of the company's $4.33 to $4.79 guidance, and it has drifted down from $4.67 when that range was issued. Revenue expectations sit in the lower half of the $1.90 billion to $1.98 billion range. So analysts have trimmed their numbers rather than chased them. The Earnings Whisper of $4.80 is a different story. It lands just above the top of management's range, which suggests the investors who remain engaged expect Dycom to clear its own guidance comfortably.
The central question is the communications segment. Last quarter management pushed about $150 million of wireless revenue out of the second half of fiscal 2027 and into fiscal 2028. It cut the segment's full-year revenue outlook to $5.90 billion to $6.01 billion as a result. Segment margin fell to 13.6%, down 134 basis points from a year earlier and a sharp turn from a small gain in the first quarter. Management blamed lost operating leverage from the wireless delay, deliberate spending on its workforce and benefits, and about 35 basis points of fuel costs. It described these as timing and investment issues, not lost demand. This quarter is the first full period to absorb the deferral. A margin that stabilizes or improves from 13.6% would support that explanation. Another step down would suggest the pressure goes deeper than a calendar shift. Commentary on whether the wireless scope is still intact for fiscal 2028 matters just as much.
Building Systems is the other side of the story. Its 24.5% segment margin last quarter beat the mid-teens level management laid out when it acquired Power Solutions. Management then raised its outlook for the segment to a high-teens to low-20s range. Even a margin in that new range would be a solid outcome. It would also show whether the second-quarter figure was a high-water mark or a new baseline. National Technology Integrators adds a fuller quarter of revenue after its partial-quarter debut beat expectations.
Backlog will be read closely. It has climbed from $8.2 billion to a record $12.2 billion over three quarters. Long-haul, middle-mile and inside-the-fence data center work recently passed $1 billion in contracted awards. Further growth here would back management's confident talk of faster long-haul activity in calendar 2027. Any change in tone around the newly flagged risk of local data center moratoriums and community opposition would draw scrutiny given the stock's slide. Capital allocation is also worth watching. The company authorized a new $150 million buyback, net leverage stood at 2.3 times, and trailing free cash flow had roughly tripled. Buying back stock at these prices would signal management's conviction.
Sentiment has cooled noticeably. It is barely positive now, compared with clearly bullish readings before the last report. That lowers the bar in one sense. Still, the market seems to doubt the durability of the growth story more than this quarter's numbers. A result near the Whisper, with stable communications margins and backlog still growing, would argue that the selloff mistook a timing delay for a lasting problem. Without margin stabilization, even a beat may not be enough to restore confidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-13 | |
| Sep-10 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 | |
| Aug-26 | |
| Aug-17 | |
| Aug-14 | |
| Aug-04 | |
| Jun-02 |
