Weibo Misses Badly As Ad Slump Deepens, Margins Collapse And Management Pushes Recovery Hopes Past 2027
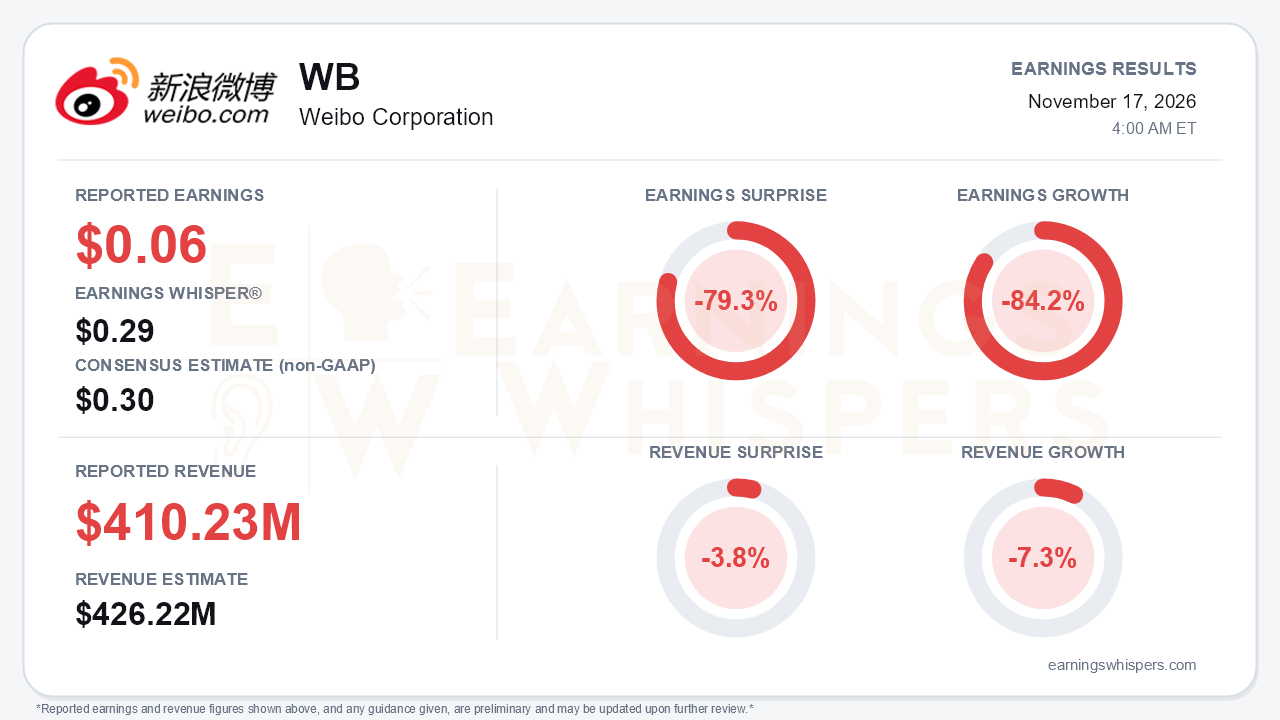
Weibo delivered a decisive miss for the September quarter. Non-GAAP earnings were $0.06 per share, against a $0.30 consensus and a $0.29 Earnings Whisper number, a 79.3% shortfall. Earnings fell 84.2% from a year earlier. Revenue declined 7.3% to $410.23 million, 3.8% below the $426.22 million consensus. The central takeaway is not a single soft quarter. Revenue growth has now decelerated for three straight quarters, from +6% in Q1 to +2% in Q2 to -7% in Q3. On a constant-currency basis the decline was 13%, so the stronger renminbi flattered the reported number.
The quality of the quarter deteriorated at nearly every level of the income statement.
- **Advertising:** Revenue fell 8% (-14% in constant currency). Non-Alibaba advertising dropped 5% as e-commerce, gaming and cosmetics budgets shrank.
- **Alibaba:** Ad revenue fell 33%, lapping last year's local-services promotion spending. The release puts Alibaba revenue at $30.5 million. The call summary cited $13.5 million, but the release figure is the reported number.
- **Value-added services:** Revenue slipped 1%, a sharp reversal from roughly 19% growth in Q2.
- **Costs:** Cost of revenues jumped about 22% on higher ad production costs.
- **Margins:** Non-GAAP operating margin compressed to 17%, from 28% in both Q1 and Q2 and 30% a year ago.
Below the operating line, a $32 million net interest and other loss further eroded profit. Management partly tied this to lower returns on wealth management products. As a result, non-GAAP net income was just $14.3 million against $70.9 million of non-GAAP operating income.
GAAP EPS of $0.10 actually exceeded the non-GAAP figure. That is because an $8 million investment gain and equity-method items were excluded from the adjusted results. Investors should not read the GAAP figure as a sign of hidden strength. Operating cash flow also turned negative. The release reports $10.2 million used in operations, while the call summary cited roughly -$20 million. Either way, it is a sharp drop from $164 million in Q1.
The conference call did little to soften the picture. The tone shifted from Q1's talk of "initial signs of stabilization" to "appropriately prudent" and "limited visibility." For Q4, management flagged three pressures:
- a high comparison base in food-delivery advertising;
- lighter handset launch timing;
- cautious Double 11 budgets.
More damaging was a first look at 2027. Management expects handset advertising, excluding Apple, to be flat to down and auto ads to decline slightly as the government manages the pace of new car launches. Management said 2027 ad growth is under "quite a lot of pressure." Cosmetics, games, entertainment and luxury advertisers are trimming budgets with no clear recovery timeline. On the user side, monthly actives slipped to 551 million from 561 million in Q2 and 567 million at the end of 2025. Daily actives were flat at 254 million.
There is a credible product story, but it is early and not yet monetizing at scale.
- **Video creators:** About 15,000 were onboarded in Q3, versus fewer than 10,000 in Q2.
- **Engagement:** Video supply and viewing time both grew double digits sequentially.
- **Search:** Conversational search queries doubled quarter over quarter, though intelligent search usage remains below its 2025 peak amid competition from standalone AI products.
- **AI ad tool:** A new intelligent ad-placement tool handled 20% of new app-download campaigns in October.
- **Content marketing:** It remains about half of ad revenue, with celebrity marketing revenue and advertiser counts growing year over year.
A busier Apple launch cadence in 2027 is another potential offset. These are real engagement and tooling gains, but they are not yet showing up as revenue.
The balance sheet is a cushion, with $2.31 billion in cash and short-term investments. Nearly $797 million of long-term loans has, however, moved into current liabilities, which makes cash generation more relevant. Shrinking profits and negative operating cash flow give bears legitimate ammunition here.
The market had largely anticipated trouble. Shares entered the report at $6.00, down 21.9% since the open after the August report. That was essentially at the bottom of the inter-earnings range: a 52-week low of $5.99 was set the day before the release. The stock sat about 24% below its 200-day moving average of $7.91. Investor sentiment remained negative but improved slightly, from -0.26 to -0.22, consistent with expectations already being low. Momentum and AVWAP trend readings remain negative.
The bottom line is that Weibo's slowdown has become a contraction, and management's first 2027 commentary points to continued pressure rather than a rebound. Video, search and AI ad tools give the company something to build on. Until those initiatives offset weakness in core advertisers and the Alibaba relationship, a depressed share price reflects the fundamentals rather than an obvious mispricing.
Read our earnings preview for Weibo Corporation: https://www.earningswhispers.com/article/WB/23110
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-10 | |
| Oct-28 | |
| Oct-12 | |
| Sep-21 | |
| Aug-21 | |
| Aug-20 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Jul-29 | |
| Jul-09 | |
| Jul-08 | |
| Jun-17 |
