Research Solutions Doubles The EPS Estimate, But Slowing Recurring Growth And A Trimmed EBITDA Outlook Put The Record AI Pipeline On The Clock
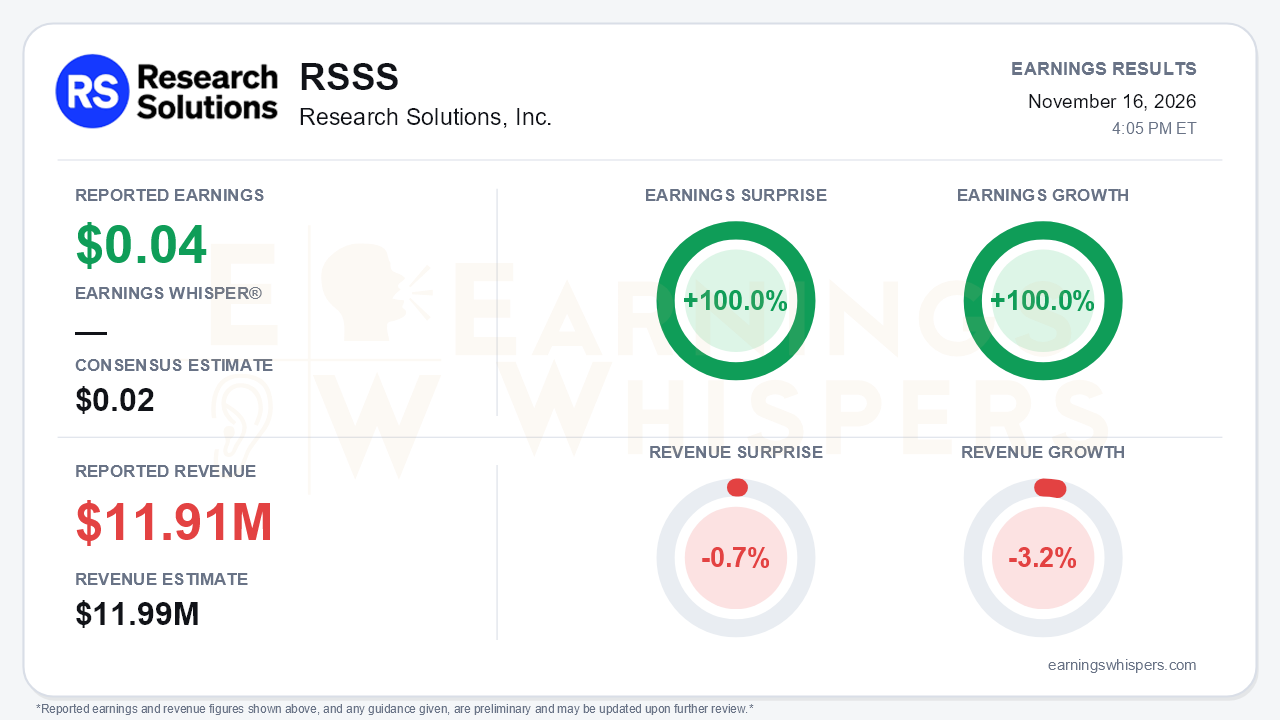
Research Solutions (NASDAQ: RSSS) delivered a quarter that looks better on the earnings line than in the growth metrics underneath it. Fiscal first-quarter earnings of $0.04 per share beat the $0.02 consensus by 100.0% and grew 100.0% year over year. Revenue of $11.91 million missed the $11.99 million consensus by 0.7% and fell 3.2% from a year ago. The central tension is clear: management produced its most confident AI narrative yet, with a record deal and a pipeline above $5 million of ARR, while reported recurring growth decelerated for another quarter and full-year adjusted EBITDA expectations moved lower.
The quality of the beat deserves scrutiny. The $0.04 figure is adjusted net income excluding one-time items. On a GAAP basis, the company earned $765,000, or $0.02 per diluted share, essentially unchanged from $749,000 a year ago. Even that GAAP result was helped by a non-cash stock-compensation recovery from restricted stock forfeitures, which turned the line into a credit of roughly $197,000 versus a $212,000 expense last year. G&A rose 32.8% on legal and severance costs. Adjusted EBITDA fell 30.3% to $1.0 million, an 8.6% margin, or $1.5 million excluding one-time items, roughly flat with last year. The real operating improvement came at the gross line. Gross margin expanded 300 basis points to 53.6%, driven by mix shift and a transaction margin that rose to 26.7% from 23.8%. That more than offset a dip in platform gross margin to 87.0% from 88.1% as hosting costs rose.
The deceleration shows up in the recurring business. Platform revenue grew just 3.7%, down from 7% growth cited on the prior call and 14% two quarters earlier. Total ARR growth slowed to 5.7% from 8.5% and 14%. B2B ARR still grew 11.5% to $16.5 million, but incremental B2B ARR in the quarter was only $257,000, less than half the $561,000 added a year ago. Management put Q1 B2B bookings at about $500,000. The call cited the prior quarter at roughly $961,000 in one context and about $1.3 million in another, but either figure marks a steep sequential drop. B2C ARR fell another $299,000 to about $6.0 million. Churn is down about 30% from a year ago but remains near $300,000 a quarter, which management called its biggest pain point. Transaction revenue declined 8.2% on lower paid order volume even as active customers rose to 1,360, with academic accounts up 17% and corporate accounts down 2.1%. Management said part of that weakness is unexplained and acknowledged that AI "zero-click" substitution is possible. That is a meaningful admission for a business built on article access.
The forward story is where the call gained conviction. After the quarter closed, the company signed the largest deal in its history: a roughly $1 million ARR Scite expansion with a long-time Article Galaxy customer. It will book in Q2 on a one-year term, with potential upside in years two and three. Management described the pipeline, now above $5 million of ARR, as its strongest ever, including another roughly $1 million pharma opportunity. Several AI metrics are moving quickly:
- AI-related ARR reached about $1.1 million, up 38% since fiscal year-end.
- Customers with AI in their contracts rose to 49 from 42.
- AI reads doubled to more than 33 million after integrations with ChatGPT, Claude and now Microsoft Copilot.
- Researchers at more than 15 corporate customers placed hundreds of orders through AI assistants in October, up from a few dozen per month over the summer.
The costs and timing pressures are equally concrete. The big deal slipping a quarter, plus severance, legal and IT security spending that will continue into Q2, led management to say full-year adjusted EBITDA will come in a little lower than previously discussed. Management added that the exit run-rate should exceed its prior view. Large-deal sales cycles have stretched to five to seven months or longer amid AI and security reviews. Sales and marketing spending is also set to rise by $100,000 to $200,000.
The balance sheet gives management room to execute. Cash was $12.6 million with no debt after a $1.2 million Scite earn-out payment, though about $5.6 million of contingent earn-out liability remains. The board views buybacks as the best use of cash and flagged a possible announcement.
Investor sentiment remains deeply negative but improved, rising to -0.78 from -0.93 before the prior report. The stock has not reflected that thaw. Shares at $1.89 are down 11.7% since the open following the last report and sit 16.4% below the 200-day moving average of $2.26. Earnings Whispers price and AVWAP trend readings are both negative.
The bottom line is that Research Solutions offered a credible AI-monetization story, with a record deal, a much larger pipeline and agentic ordering gaining traction. However, the reported numbers are moving the other way: slowing ARR growth, thin bookings, eroding transactions and B2C, and a softer EBITDA outlook. The adjusted EPS beat does little to resolve that gap. Investors will need to see the $1 million deal and pipeline conversion show up in Q2 net-new ARR before the improving narrative can outweigh the decelerating results.
Read our earnings preview for Research Solutions, Inc.: https://www.earningswhispers.com/article/RSSS/23028
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-16 | |
| Nov-11 | |
| Nov-11 | |
| Nov-08 | |
| Nov-05 | |
| Nov-03 | |
| Oct-06 | |
| Sep-16 | |
| Sep-11 | |
| Sep-10 | |
| Sep-09 | |
| Sep-03 | |
| Sep-01 | |
| Aug-18 |
