Iridex Misses Badly And Cuts Guidance Again: Margin Gains Can't Offset Collapsing International Demand And Thinning Cash
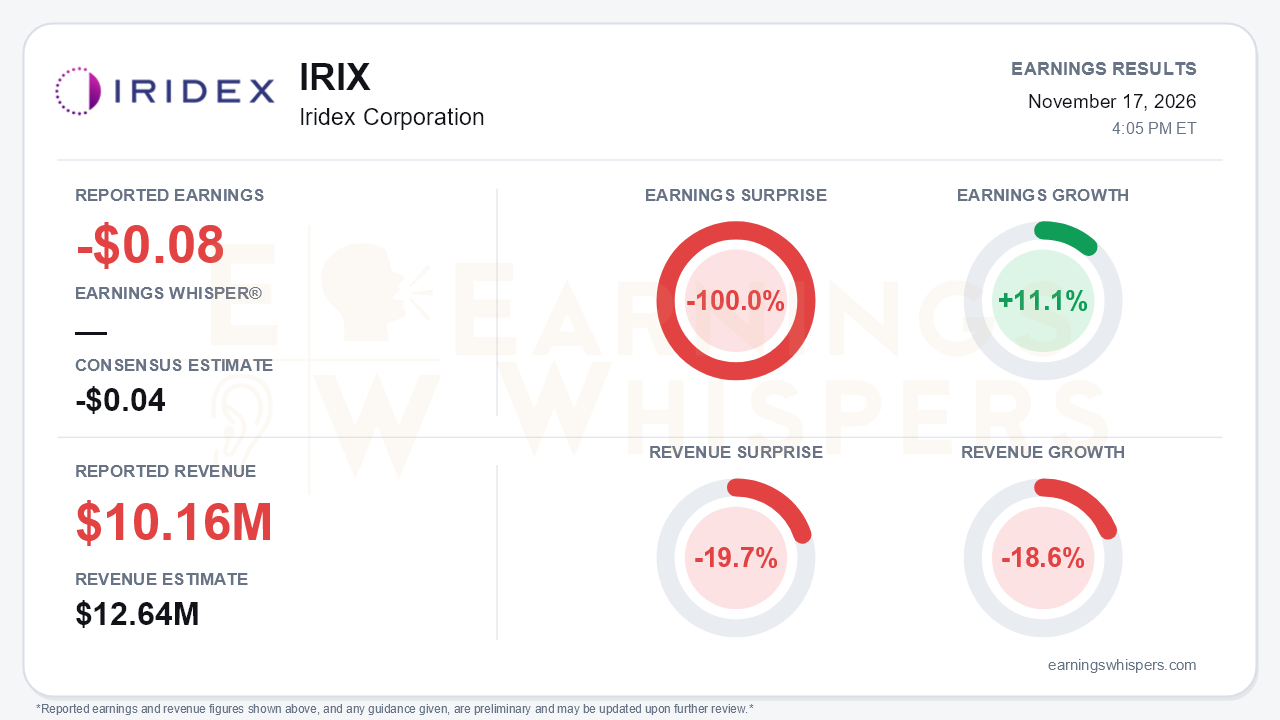
Iridex delivered a quarter where the cost story kept improving while the revenue story broke. The company reported a third-quarter loss of $0.08 per share, twice the $0.04 loss consensus expected, a 100.0% negative surprise. Revenue of $10.16 million fell 18.6% year over year and missed the $12.64 million consensus by 19.7%. That is a large miss for a company whose outlook management had reaffirmed on three straight calls. The loss did narrow from $0.09 a year ago, and earnings growth registers at 11.1%. But that improvement came from margin repair and an easy prior-year comparison, not from the business growing. Management cut full-year 2026 revenue guidance to $46-48 million from $51-53 million, roughly 10% at the midpoint, and that cut is the real headline.
The revenue deterioration is accelerating. Sales were roughly flat year over year in the first quarter and down about 7% in the second, before falling sharply in Q3. The weakness was broad.
- **Retina:** revenue fell to $5.1 million from $6.7 million, its third consecutive double-digit decline. Management had told investors on the Q2 call to expect low-single-digit second-half retina growth, and that is no longer achievable. China retina orders fell to about $400,000 from roughly $4 million a year ago, and European distributors are deferring orders while they await MDR approval for Pascal amid competitive pricing.
- **Cyclo G6:** family revenue slipped to $3.2 million from $3.5 million, a reversal from 19% growth in Q2. Probe volume fell to about 11,900 from 14,900 as international distributors worked through inventory pulled forward earlier in the year.
- **Other revenue:** fell to $1.9 million on lower service revenue and no royalties.
Gross margin is the genuine bright spot, though it deserves careful reading. Reported gross margin jumped to 42.4% from 32.1% a year ago and 34.2% in Q2. Part of the year-over-year gain reflects a roughly $0.8 million inventory write-off that depressed last year's quarter. The release cites a 38.7% "pro forma" figure and a 370-basis-point improvement. The 38.7% appears to match the prior-year margin excluding that write-off, so the cleaner reading is that Q3 margin ran about 370 basis points above a like-for-like base. That gain came from geographic mix and pricing discipline, and it is still real progress. Even so, operating expenses were flat at $5.5 million, and adjusted EBITDA slid to a $0.6 million loss. That compares with a $0.4 million loss in Q2 and a small profit in Q1, so lower volume more than absorbed the margin gains.
The balance sheet is where bears have the most ammunition:
- Cash fell $1.0 million in the quarter to $3.7 million.
- Inventory has climbed to $11.8 million from $7.9 million at year-end as the company built safety stock for its manufacturing transition.
- Stockholders' equity has dwindled to $2.6 million.
- The earlier goal of positive operating cash flow for fiscal 2026 has been replaced by a goal to "drive toward breakeven."
Management argues cash burn should drop significantly in Q4 as inventory converts to sales, including a deferred Japan Pascal order of about $300,000. The CFO said Q4 could be adjusted-EBITDA positive at the high end of the range. Note how much that rests on: the revised guidance implies a meaningful sequential revenue rebound in Q4, which requires a quarter that just disappointed to be followed by a strong one.
The forward catalysts are almost entirely about cost and focus rather than growth:
- **Facility move:** the San Jose relocation is complete, with regulatory audits passed, about $600,000 in annualized savings, and six months of free rent.
- **Contract manufacturing:** the transition to contract manufacturers is expected to drive further margin expansion through 2027.
- **Further cuts and review:** additional 2027 operating-expense reductions are planned, and a strategic review of product lines and international distribution is underway.
- **U.S. strength:** Pascal revenue grew about 50% and U.S. probe volume held steady at higher prices. Two-year MicroPulse TLT data also support earlier use.
Management was explicit that the review may mean accepting lower revenue in some regions or products. That is a rational profit-first pivot, but it means the top line could keep shrinking by design. No 2027 guidance was offered. External headwinds remain, including energy costs tied to the Iran war in Asia and Europe and developments in Saudi Arabia, with the Middle East still excluded from guidance. The call's tone shifted from Q2's "inflection point" language to calling results "disappointing."
The market had already been treating Iridex as a distressed microcap. Shares opened at $0.82 after the August report, then hit a 52-week low of $0.61 in mid-September. They rallied to $1.02 in early October, roughly at the $1.00 200-day moving average. The Earnings Whispers trend readings are mixed to negative, with AVWAP negative while price and momentum are neutral. That October bounce has to contend with a report that undercut the near-term revenue and cash narrative.
The bottom line is that Iridex is becoming a leaner, higher-margin company while its revenue base erodes faster than its cost base shrinks. The margin progress is credible, and the 2027 restructuring plan is coherent. But a sharp miss, a guidance cut after repeated reaffirmations, collapsing China retina demand, and cash under $4 million leave little room for error. The Q4 rebound management is counting on now carries most of the weight in the investment case.
Read our earnings preview for Iridex Corporation: https://www.earningswhispers.com/article/IRIX/23116
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-10 | |
| Nov-03 | |
| Oct-12 | |
| Oct-05 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Aug-04 | |
| Jul-20 | |
| Jun-09 | |
| May-20 | |
| May-19 |
