Full Truck Alliance Meets The Whisper As A Profit And Cash Surge Masks Slowing Core Monetization
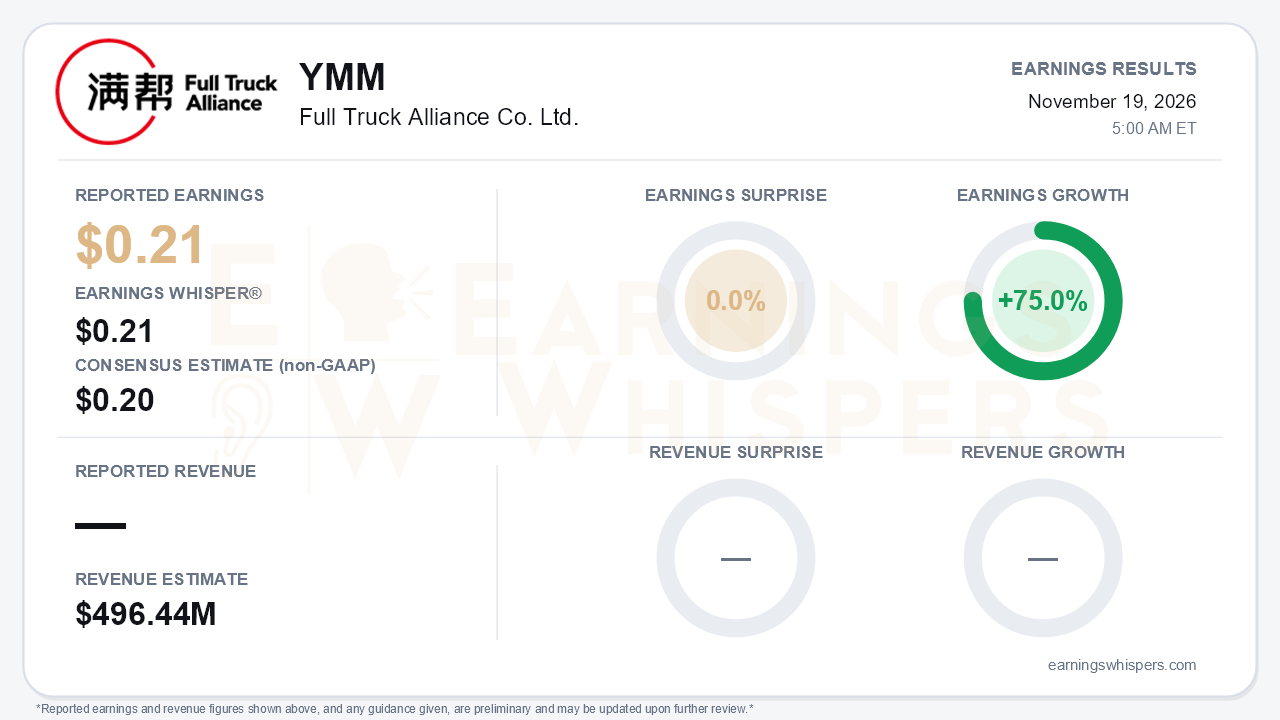
Full Truck Alliance delivered exactly what the most informed expectations demanded and little more. Non-GAAP earnings of $0.21 per ADS edged past the $0.20 consensus but matched the $0.21 Earnings Whisper, an in-line result with a 0.0% surprise. The year-over-year comparison is far more striking: earnings grew 75.0%, GAAP net income rose 49.0% to RMB1.37 billion, and non-GAAP adjusted net income climbed 47.0% to RMB1.45 billion. That is a sharp acceleration from the roughly 6% profit growth posted in the second quarter. The central tension is that the profit inflection came alongside clear deceleration in the platform's core volume and monetization engines. Those engines are what ultimately justify the growth story.
The quality of the earnings jump deserves scrutiny. Operating income more than doubled, up 107.4% to RMB1.61 billion. Revenue was not the main driver; total net revenue rose only 6.8% to RMB3.59 billion. Cost of revenues instead collapsed from RMB1.61 billion to RMB1.03 billion. Tax-related costs net of government grants fell to RMB816.8 million from RMB1.43 billion, mainly in freight brokerage. The provision for credit solutions also shrank from RMB144.4 million to RMB47.7 million as the lending book was wound down. Those are real savings. However, they stem from tax mechanics and a deliberate retreat from credit rather than from faster growth in the matching business. Below the operating line, other income fell by nearly half and income tax expense jumped. That explains why net income growth trailed operating income growth so widely. Cash generation was the cleanest positive. Operating cash flow nearly doubled year over year to RMB3.16 billion, helped by credit-book collections. Total cash and investments reached RMB35.5 billion, which comfortably supports the US$0.084-per-ADS quarterly dividend.
The call made the slowdown in operating trends explicit. Fulfilled orders grew 11.3% to 70.6 million, down from 12.7% in the second quarter and 14.3% in the first; management blamed weather and holiday timing. Transaction service revenue, the core monetization line, rose 25.0% to RMB1.82 billion, a step down from 33% in each of the prior two quarters. Part of that slowdown reflects heavier trucker subsidies booked as contra-revenue. The more consequential admission was structural. Commission penetration now stands near 95%, and management said penetration-led growth is largely complete. Future gains must come from per-order pricing and mix, which is a harder lever to pull. The fulfillment rate also slipped to 44.7% from a record 47.0% in the second quarter, although it remains 4.1 points higher year over year. On the positive side, shipper MAUs rose 12.4% to 3.76 million. Freight brokerage also rebounded 9.2% on higher fees and share gains as smaller non-compliant platforms exit.
The catalyst list is broadening. The Sinopec fueling partnership went nationwide, with more than 24,000 partner gas stations. Overseas, the Qmove business doubled daily orders quarter over quarter. It began charging commissions in Indonesia, the UAE and Turkey and entered Brazil as its fifth market. Management is also extending AI dispatch agents to mid- and long-tail routes. Against these catalysts, the credit wind-down carries its own costs. Value-added services revenue fell to RMB331.3 million from RMB560.7 million. The non-performing loan ratio rose to 4.7% from 3.8% in the second quarter, which management attributed to a shrinking denominator. Freight brokerage profitability also remains tied to VAT and tax-refund policy. That dependence makes the biggest earnings tailwind sensitive to regulation.
Guidance adds to the mixed picture. Fourth-quarter revenue guidance of RMB3.19 billion to RMB3.29 billion was described as above estimates. Even so, it implies growth of flat to 3.1%, a clear slowdown from the 6.8% just reported. Bears have legitimate ammunition here, since a reassuring guide relative to expectations still points to decelerating top-line momentum.
Investor sentiment became noticeably more positive, rising to 0.54 from 0.36 at the prior report. The stock has not followed. Shares closed at $8.38 before the release, just 1.3% above the $8.27 open after the August report, and 3.9% below the 200-day moving average of $8.72. The stock climbed from an inter-earnings low of $7.91 in late October to a high of $9.28 on November 5. It then gave back much of that move, entering the report 9.7% below the peak. The Earnings Whispers trend readings are largely neutral, with AVWAP still negative.
The bottom line is that Full Truck Alliance converted tax savings, lower credit provisions and a shrinking loan book into a powerful profit and cash-flow quarter. Even so, it only matched the Whisper while its core order growth, take-rate expansion and fulfillment rate all cooled. With penetration nearly maxed and fourth-quarter revenue guided to slower growth, the next leg depends on pricing, overseas traction and new services such as fueling. Improving sentiment has yet to pull the stock back above its long-term average.
Read our earnings preview for Full Truck Alliance Co. Ltd.: https://www.earningswhispers.com/article/YMM/23171
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| Nov-11 | |
| Oct-28 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Aug-05 | |
| Aug-03 | |
| May-21 | |
| May-21 | |
| May-12 | |
| Apr-30 | |
| Apr-14 |
