Elastic Accelerates To 17% Growth And Record Margins, But An FX-Trimmed Guide And Back-Loaded Q4 Leave The Stock Near Its Lows
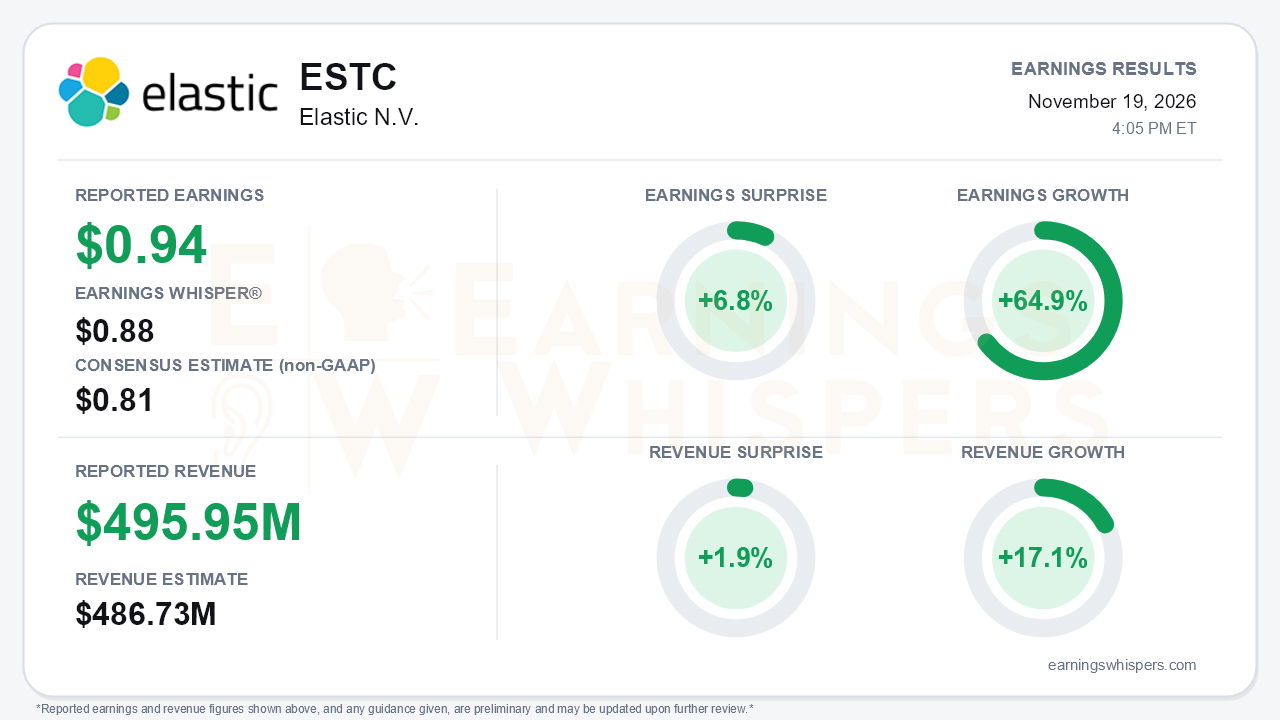
Elastic delivered one of its cleanest quarters in some time. Non-GAAP EPS of $0.94 beat the $0.81 consensus and the $0.88 Earnings Whisper for a 6.8% surprise, and earnings grew 64.9% year over year. Revenue of $495.95 million topped the $486.73 million consensus by 1.9% and grew 17.1%. That growth rate is accelerating, up from 15% in Q1 and 14% in constant currency in Q4 FY26. Sales-led subscription revenue grew 19% in constant currency, versus 17% and 16% in the prior two quarters. The central tension is that this acceleration came with a guide that holds reported full-year revenue flat and implies a sharp Q3 slowdown. That leaves investors to weigh a better quarter against a second half that management has made dependent on Q4.
Margins drove the earnings beat. Non-GAAP operating margin reached a record 22.2%, against roughly 19% guided, 16.2% in Q1 and 16.5% a year ago. GAAP operating income swung to $22 million (4.4% margin) from an $8.2 million loss. Management called it the start of sustainable GAAP operating profitability, and it guided GAAP operating margin positive for both Q3 and the full year. The quality of the margin gain deserves some scrutiny, however. Gross margin was flat at 78.0%, so the leverage came from operating expenses. Non-GAAP R&D spending actually fell year over year, from $79.7 million to $77.2 million, after the company booked $22.3 million of restructuring charges in the first half. GAAP net income was only $171,000, or $0.00 per share, because of a $28 million tax provision. Adjusted free cash flow was $44 million, or a 9% margin, which included $6.7 million of restructuring cash, and the full-year 21.5% FCF margin target was held.
Beneath the headline, the mix shift toward cloud is pronounced. Annual Elastic Cloud revenue grew 30% and now accounts for 41% of revenue. Monthly cloud grew just 3%, and other subscription, mostly self-managed, rose 10% and slipped 1% sequentially. Management described consumption as very strong and broad-based:
- Security was the fastest-growing solution, with search/AI close behind.
- AI penetration among $100K+ customers climbed to 40%, from 37% in Q1 and 28% three quarters ago.
- Wins included an eight-figure SIEM consolidation and a sovereign-cloud telco choosing Elastic as its sole vector database.
- Token consumption through Elastic Inference Service is emerging as a new monetization lever.
The softer data points are real. The $100K+ customer count rose by only about 30 after a record 80-plus additions in Q1. Total RPO growth slowed to 23% from 27% in Q1 and 28% in Q4 FY26. cRPO held at 20% in constant currency. Observability still lags the other solutions.
Guidance is where bears have legitimate ammunition. In constant currency, the full-year outlook rose again:
- Total revenue growth increased to 15.9% from 15.3%.
- Sales-led subscription growth increased to 18.0%.
- Non-GAAP EPS moved to $3.35–$3.41.
On a reported basis, the picture is flatter. A stronger dollar creates a $9.5 million second-half headwind, so the revenue midpoint stayed near $2.004 billion. Reported sales-led growth slipped to 17.2% from 17.4%. Management passed through only the Q2 beat, citing caution on Europe and the Middle East. The Q3 guide calls for 12.9% reported growth (13.9% constant currency), and Q3 EPS guidance of $0.90–$0.92 sits below the quarter just reported. Management expects a Q4 snapback to roughly 17.4% constant-currency growth because self-managed renewals are weighted about 20% more toward that quarter. That back-loading drew analyst questions and adds execution risk. A planned FY28 change that reduces quarterly cloud disclosure will also lower visibility.
The market setup is more complicated than the beat implies. Shares have fallen 20.1% since opening at $103.89 after the August report. The stock peaked at a 52-week high of $108 that same day and then gave back the entire post-report spike. It entered this report at $83.01, just 3.9% above the inter-earnings low of $79.87 set two days earlier. Shares remain 21.4% above the 200-day moving average, so the longer-term uptrend has not been erased, but recent buyers are underwater. The Earnings Whispers trend readings are mixed: sequential growth and momentum are positive while AVWAP is negative. Investor sentiment was essentially unchanged at a decidedly negative -0.47, so expectations were already subdued going in. Management's own repurchases, averaging $86.31 a share, plus a fresh $500 million authorization, signal that it sees value at these levels.
The bottom line is that Elastic delivered accelerating revenue, record margins and its first sustained GAAP operating profit, while lifting constant-currency guidance for the second straight quarter. However, the reported outlook was held flat, Q3 is guided to a noticeable slowdown, and the full-year math now depends heavily on Q4 self-managed renewals. With sentiment still negative and shares near their post-August lows, the next test is whether that Q4 renewal cohort arrives as planned, not whether Elastic can beat a quarter.
Read our earnings preview for Elastic N.V.: https://www.earningswhispers.com/article/ESTC/23176
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-19 | |
| Nov-18 | |
| Nov-16 | |
| Nov-11 | |
| Nov-05 | |
| Nov-04 | |
| Oct-30 | |
| Oct-26 |
IBD Stock Of The Day: Software Stock Elastic Rises In Buy Zone After 150% Rally
ESTC +3.77%
Investor's Business Daily
|
| Oct-22 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 |
