CleanSpark Heads Into Earnings Needing Proof Its AI Lease Can Outrun Mining Decline
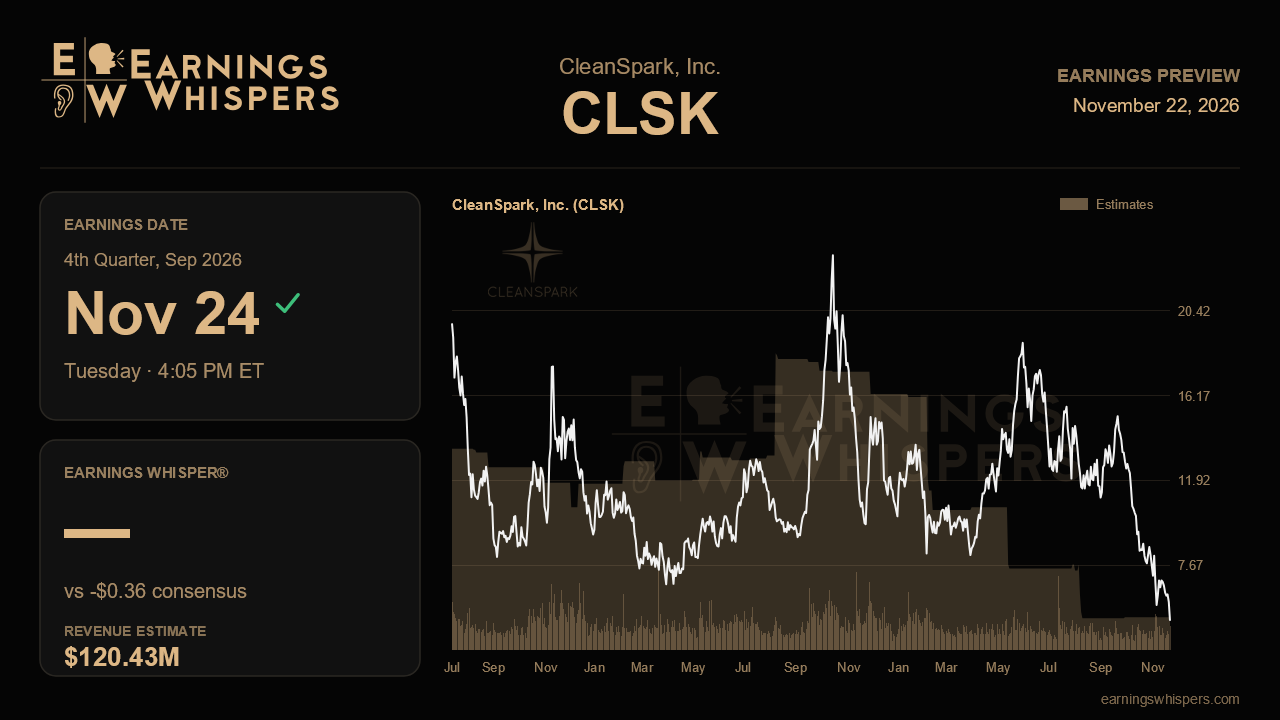
CleanSpark finally delivered the data center lease it had been promising for a year, and the market's response has been to cut the stock by roughly two-thirds. That contradiction frames the fiscal fourth-quarter report due after the close on November 24. The company now has a signed 20-year triple net lease at Sandersville with a high-investment-grade tech tenant, worth $6.6 billion in contracted revenue and roughly $330 million in average annual net operating income. Investors appear to be focused instead on the shrinking Bitcoin mining business that pays the bills until that first data hall comes online in late calendar 2027.
The Street's numbers show how much the funding engine has slowed. Consensus calls for a loss of $0.36 per share on revenue of about $120.4 million, a 46% drop from the $223.7 million reported a year ago and a sequential decline from last quarter's $138 million. The year-ago loss was just a penny, which explains the eye-catching negative EPS growth figure. That comparison means little because CleanSpark's GAAP results are dominated by non-cash marks on its Bitcoin holdings. Last quarter's $240 million net loss included $133 million of mark-to-market charges, so the bottom line will mostly reflect where Bitcoin closed the period, not how well the company operated. Management has not issued formal guidance, which leaves the operating detail to carry the report.
That detail starts with mining economics. Gross margin slid from 47% to 40% to 38% over the first three quarters of the fiscal year, and revenue per Bitcoin mined fell from about $100,000 to roughly $72,000. Management called it the toughest mining environment it had seen. The revenue consensus implies another step down, so the margin line will show whether cost discipline can hold the business near breakeven on a cash basis. Its digital asset management program, which had generated $25.8 million year to date by selling Bitcoin above spot, is another lever worth tracking. Management also hinted it would rather tap its Bitcoin balance than issue undervalued stock, so any change in holdings will reveal how that tradeoff is playing out.
The AI side has to show momentum beyond a single signature. Management pledged no equity or equity-linked raise for Sandersville and targeted project debt above 90% of cost. Progress on that financing would be the strongest validation of the self-funded story, and delays or costlier terms would challenge it. The 885 megawatts of Texas capacity under exclusivity with the same counterparty is the next proof point. Converting any of it into a signed lease would show the Sandersville template can be repeated. Continued exclusivity without a contract, especially with the ERCOT batch-zero review and Austin County's data center moratorium unresolved, would keep the Texas discount in place. Updates on the goal of pushing contracted power beyond 2.1 gigawatts, the Washington, Georgia expansion and the 2027 ready-for-service timeline round out the checklist.
Sentiment has soured sharply. Bearish readings deepened to 44% from about 15% heading into the last report, and the stock has trailed the S&P 500 by more than 54 percentage points since then. At $4.89, shares sit right on top of their post-earnings low of $4.84 and far below the 200-day average near $11.90, a long way from last quarter's range of $11.83 to $19.17. The bar for upside is low, but the stock has no technical support to lean on if the news disappoints.
The central question is whether CleanSpark can show that the Sandersville lease is the start of a financed, repeatable pipeline rather than a single deal. If debt funding and Texas commercialization advance while mining margins stabilize, the gap between the contracted value and the share price becomes hard to ignore. If they stall, the market will keep treating CleanSpark as a struggling miner with an expensive promise.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-19 | |
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 |
Bitcoin Miners Pivoted to AI-Only to Find It's Just as Turbulent as Crypto
CLSK +13.99%
The Wall Street Journal
|
| Nov-02 | |
| Oct-17 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 |
