Mechanics Bancorp Needs HomeStreet Cost Savings To Outrun Rising Deposit Costs
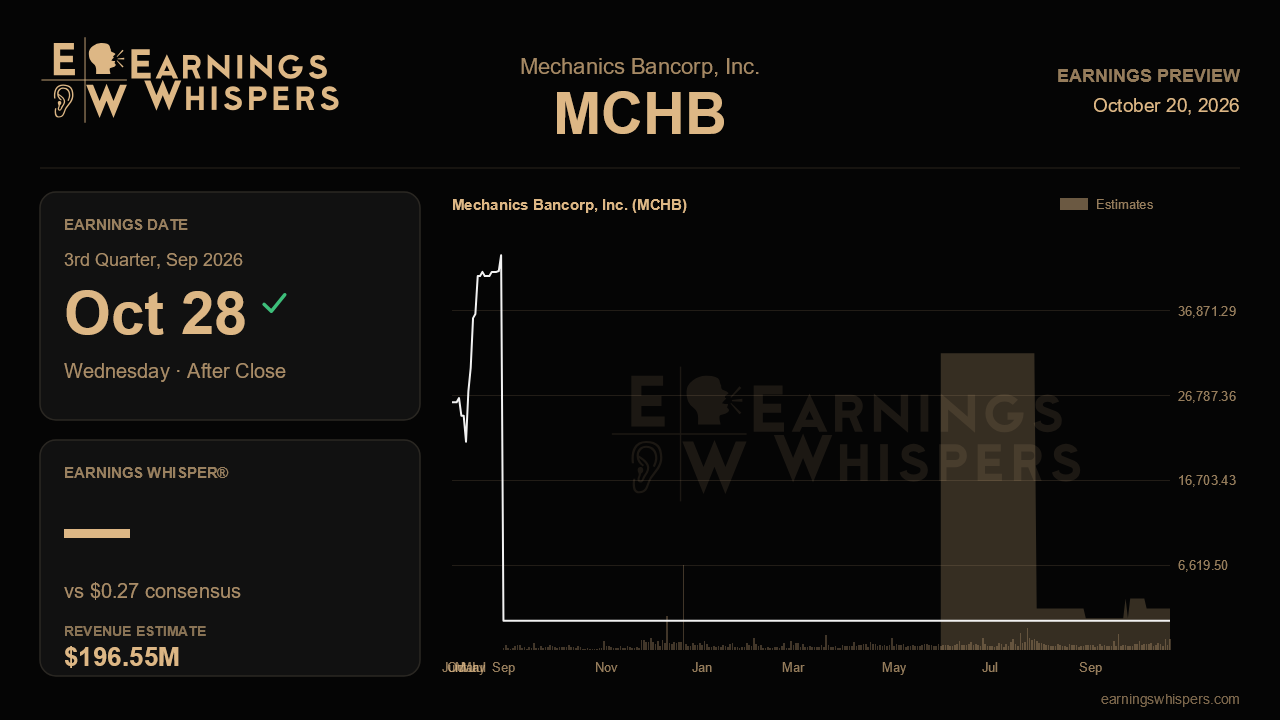
Mechanics Bancorp spent its last report declaring the hard part over. The HomeStreet integration was substantially complete, the DUS business had been sold to Fifth Third, and capital was piling up fast enough to fund an unusually generous dividend plan. The market has not been convinced. Shares have fallen 11.5% since that report while the S&P 500 gained 3.6%, leaving the stock at $14.23, below its 200-day moving average of $15.23 and only about 1.5% above its post-earnings low of $14.02. When the bank reports after the close on October 28, the question is whether self-help can carry earnings while the core revenue engine stays stuck in neutral.
The Street is looking for EPS of $0.27, matching last quarter and up a modest 3.9% from $0.26 a year ago. Consensus revenue of $196.6 million implies a 37.5% year-over-year decline and a steep drop from the prior quarter's $261.7 million. Much of that gap likely reflects the departure of the DUS business and other noise in reported revenue rather than a collapse in banking activity, but the headline figure underscores the point. Profit growth from here has to come from costs, capital deployment and balance sheet repositioning, not a bigger top line. Flat EPS is a low bar on paper, but it leaves little room for slippage on the expense side.
That is where the third quarter matters most. Management cut full-time staff from 1,890 to 1,756 and said a large share of the resulting savings would land in this period, keeping it on track for a roughly $430 million annual noninterest expense run rate by the fourth quarter. The efficiency ratio already improved to 58.4% from 61.6%. A further visible step down would validate the cost story. A stall would raise doubts about the reaffirmed 2027 targets of 17% to 18% return on tangible common equity and 1.3% to 1.4% return on assets.
The revenue side is the bigger risk. Net interest income slipped 1% last quarter to $177.2 million as earning assets shrank, and management shifted its deposit-cost outlook from flat to modestly rising through the back half of the year, citing stiff competition and customers moving out of noninterest-bearing accounts into money market products. The spot cost of deposits had already climbed to 1.28% at June 30 from 1.21% at the end of March. Readers should check whether the quarterly average follows the spot rate higher and how much noninterest-bearing balance erosion continued. Offsetting that, the planned sale of about $310 million of securities yielding 1.78% and reinvestment near 5.5% should help the margin, which edged up to 3.62% last quarter. Expect a roughly $25 million after-tax loss on that restructuring, so core and reported results may diverge sharply. Any update on selling the remaining roughly $600 million of auto loans, a portfolio whose runoff has weighed on the margin, would also be telling.
Credit and capital round out the checklist. Nonperforming assets ticked up to 0.28% of assets, still low but worth monitoring given management's complaint about irrational credit pricing in the market, which has also kept loan growth subdued alongside a thin spread between multifamily loans and securities. On capital, the bank guided to a 25 cent third-quarter dividend and a $75 million to $100 million cleanup payout in the fourth quarter. Reconfirming that range would support the roughly 7% 2027 dividend yield management has highlighted.
Sentiment has improved, moving from 28% bearish before last quarter to 19.5% bearish now, yet the share price tells a gloomier story. That disconnect frames the report. If expense savings show up clearly and the securities repositioning lifts the margin enough to offset firmer deposit costs, the self-help thesis holds and the dividend plan looks secure. If deposit pricing erodes net interest income faster than costs fall, the stock's slide toward its range low may prove to have been the market reading the story correctly.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Sep-16 | |
| Aug-19 | |
| Aug-06 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| May-13 | |
| May-07 | |
| May-01 | |
| Apr-30 | |
| Apr-30 | |
| Apr-30 | |
| Apr-29 |
