LSB Industries Must Show Volume Gains Can Outrun Fading Nitrogen Prices In Q3
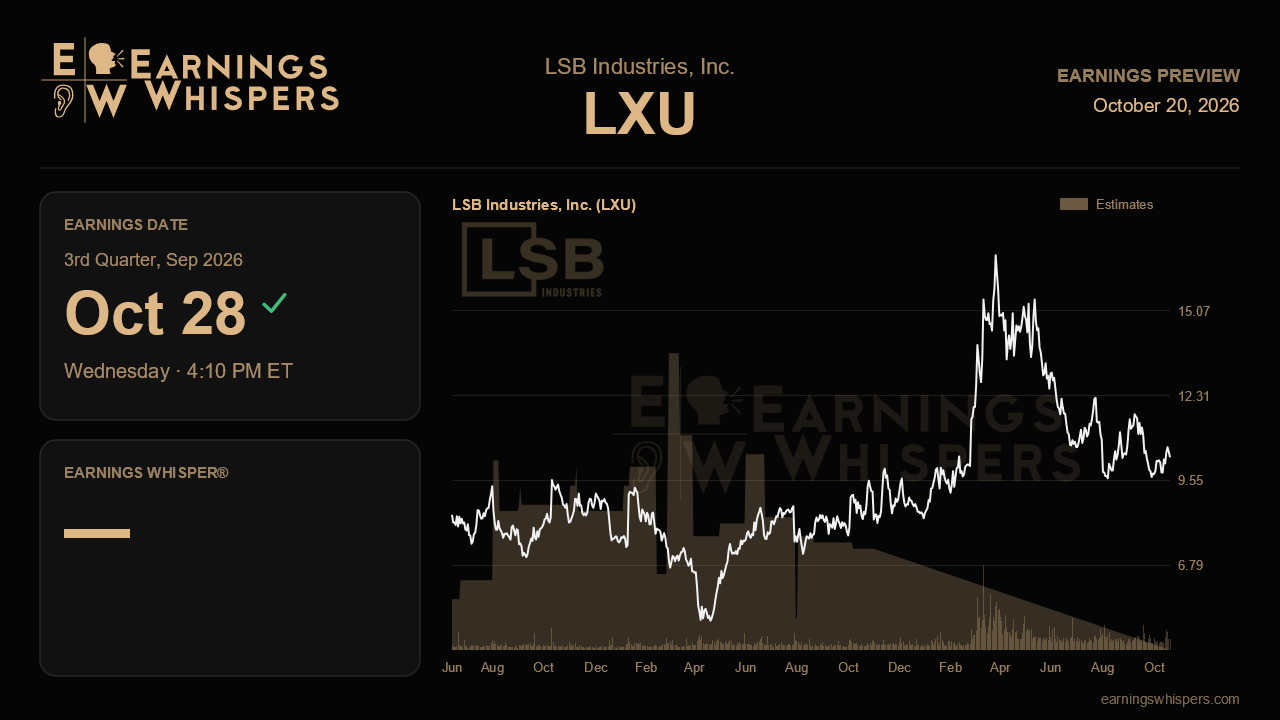
LSB Industries heads into its third-quarter report with a clean operational story and a messier pricing one. Last quarter, management finished two complex plant turnarounds on time and on budget, pushed El Dorado's ammonia output well above nameplate, and roughly doubled its earnings target for the carbon capture project. The catch is that ammonia and UAN prices have slid from their first-half highs. The report due after the close on October 28 should show which force carried the quarter: more tons, or cheaper tons.
The usual Street benchmarks are of little help this time, since there is no usable consensus figure for earnings or revenue. That leaves the year-ago quarter as the practical yardstick. A year ago LSB earned $0.10 a share on $155.4 million of revenue, with adjusted EBITDA of about $40 million. The second quarter just reported showed a loss of $0.09 a share on $168.1 million of revenue, but that period absorbed a $35 million to $40 million turnaround hit. Management estimated EBITDA would have been about $90 million without the outages. Because the Pryor turnaround was pulled forward into the second quarter, the third quarter should carry much less maintenance downtime. A clear jump back to profitability is therefore the minimum reasonable expectation.
The main operating test is El Dorado. Management said the plant was running near 1,375 tons a day after its turnaround, up from roughly 1,250 to 1,300 before. It added that cooler weather could push output toward 1,400 tons. If third-quarter volumes confirm that run rate, it would support the claim that the turnaround lifted structural earnings power and not just reliability. Management also reaffirmed that full-year production would meet or exceed targets. Any slip from that language would undercut the core of last quarter's confident tone.
Pricing is where the narrative is most exposed. Coming into the second quarter, management had pointed to Tampa ammonia near $775 a metric ton and NOLA UAN around $480 a ton. By the time of the call, August Tampa had settled at $635 and UAN was closer to $300. Much of the third quarter will reflect those lower levels. The key question is whether higher volumes can offset weaker realizations well enough to keep year-over-year EBITDA growing, as it has for several quarters. Two factors cut in opposite directions. Strong ammonium nitrate demand from mining helps. Middle East tensions could lift pricing again, though they also add volatility to global gas markets.
Costs and capital plans round out the checklist. SG&A is running at $50 million to $55 million a year, well above the original $35 million to $40 million plan, and management sees about half of that as lasting. Any sign of further creep would erode operating leverage. On growth, investors should look for progress on the carbon capture project, which is targeted to start operating in early 2027 at $25 million to $30 million of annual EBITDA. The roughly 100,000-ton El Dorado ammonia expansion is now in engineering ahead of a planned investment decision in the second quarter of 2027. Cash of about $220 million and net leverage of 1.1x give LSB room to fund both, so steady balance sheet progress would reinforce the case.
The market remains doubtful. The stock has slipped 1.7% since the last report while the S&P 500 gained 4.1%. At $10.48, it sits below its 200-day moving average of $11.72 and in the lower half of its post-earnings range of $9.37 to $12.02. That range is well beneath the prior quarter's high of $15.53. Sentiment has improved from clearly bearish to only mildly negative, which suggests skepticism is easing even though the share price has not followed. Ultimately, the report will be judged on whether higher production and a lighter maintenance schedule can absorb the drop in nitrogen prices. If they can, last quarter's execution story holds up. If pricing overwhelms the volume gains, the stock's lag will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Sep-01 | |
| Jul-30 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| May-19 | |
| Apr-30 | |
| Apr-29 | |
| Apr-29 | |
| Apr-15 | |
| Apr-02 |
