LSB Industries More Than Doubles EPS On AN Mix Shift And Pricing, But CCS Delay And Fading Premiums Complicate The Outlook
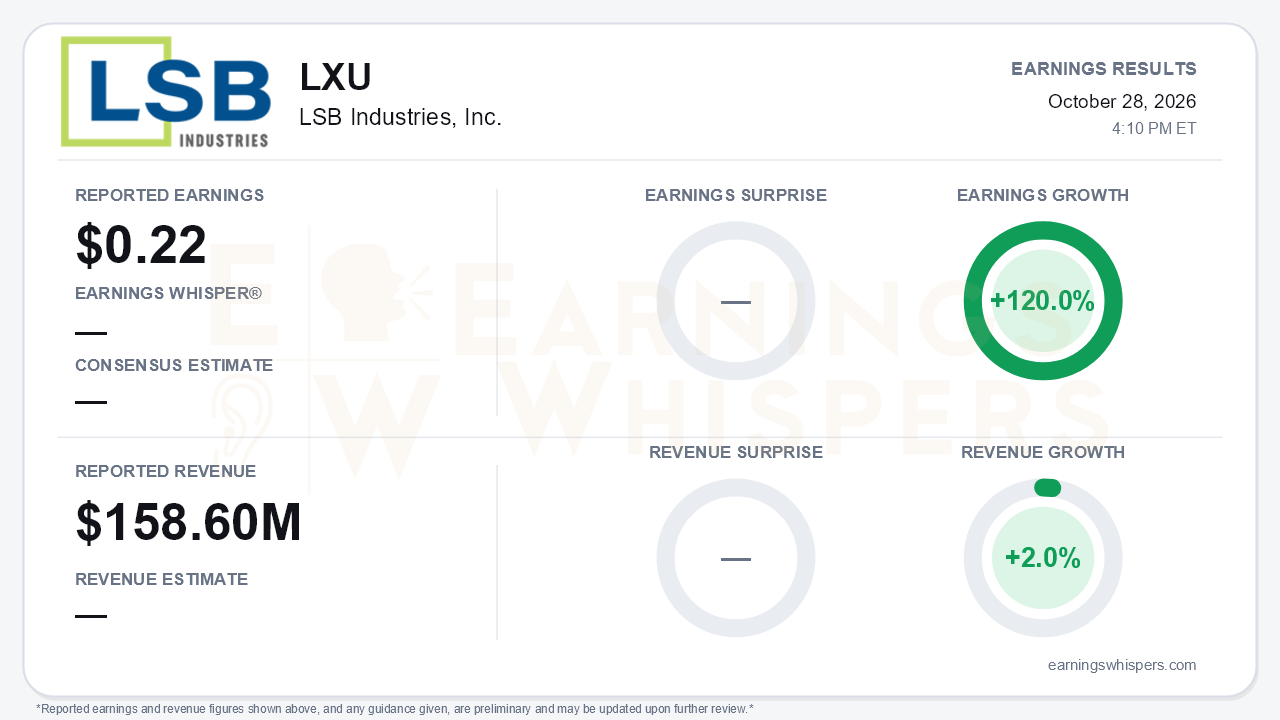
LSB Industries delivered its strongest quarter of 2026, with third-quarter earnings of $0.22 per share, up 120.0% from $0.10 a year earlier. Revenue rose only 2.0% to $158.6 million. No consensus estimate or Earnings Whisper was available, so the quarter is best judged on its trajectory. On that basis it was a clear step up. Adjusted EBITDA climbed to $62.3 million from $40.1 million, and it also improved sequentially from roughly $52 million in Q1 and $53 million in Q2. The central tension is that LSB is earning more on fewer tons with a better mix, while several of the price and cost tailwinds behind this quarter look temporary.
The flat top line hides a sharp change in what LSB is selling.
- **Mix shift toward ammonium nitrate:** Strong industrial demand pushed management to move production from UAN toward AN. AN and nitric acid volumes rose 23%, and netback prices rose 19%, lifting that line 41% to $80.9 million.
- **UAN collapse:** UAN volumes fell 59%, partly because of the Pryor turnaround, and UAN revenue dropped 61%.
- **Ammonia pricing:** Ammonia netbacks jumped 32% to $528 per ton, even as ammonia volumes fell 7%.
- **Costs:** Natural gas was 5% cheaper at $2.93/MMBtu.
Total tons sold fell 13%, yet gross profit rose to $43.1 million from $25.5 million. That is a genuine mix-and-price story.
The quality of the beat still deserves scrutiny. Management acknowledged that only about half of the Q3 cost benefit is sustainable, with the rest tied to inventory-build timing and precious-metals recoveries. SG&A also rose to $14.8 million from $10.3 million, driven by retention stock compensation, costs from the Leidos trial and fees on the CCS deal. GAAP net income of $16.3 million is the cleaner measure here, because adjusted EBITDA adds back $6.3 million of turnaround costs this quarter and nearly $39 million year-to-date.
The call added substance to the multi-year case:
- **Operations:** El Dorado is running at 1,350-1,370 tons per day after its turnaround, up from about 1,300 before, and management expects more output in winter.
- **Earnings and cash flow:** Trailing EBITDA topped $220 million, compared with $200 million at the Q2 call. Free cash flow reached roughly $74 million through nine months, against $44 million for all of 2025.
- **Balance sheet:** Net leverage held at 1.1x, down from 1.8x at year-end 2025.
- **Value-creation framework:** Management consolidated its initiatives into roughly $100 million of incremental annualized EBITDA. That includes a $55 million operational-improvement target, with about $35 million in run-rate by the end of 2026. It also raised the El Dorado ammonia expansion estimate to $20-25 million from about $20 million, with a final investment decision still slated for Q2 2027.
- **Capital return:** Management introduced small but recurring quarterly buybacks, a shift in cash deployment.
Bears have legitimate ammunition, though:
- **CCS delay:** The El Dorado carbon capture project is the largest single piece of the framework at an expected $25-30 million annually. The EPA's Class VI tracker now points to the second half of 2027, versus the Q1 2027 target cited last quarter. Management believes an earlier date is possible, but that is a hope, not a commitment.
- **Lost grant:** LSB was not selected for the USDA phase-two grant tied to the El Dorado expansion.
- **AN spot premium:** The premium on roughly 10% of AN volumes is expected to roll off in the first half of 2027 as shuttered supply returns. That directly undercuts the mix advantage that powered this quarter.
- **Ammonia prices:** Tampa ammonia averaged $622 in Q3 but was $545 in October, down from $635 cited in August and about $775 referenced at the Q1 call. Management noted that Tampa rose nearly $100 the day before the call.
- **Fall season:** Warm, dry weather and a late harvest threaten fall application.
The pricing picture is genuinely mixed. NOLA UAN rose to about $390 from roughly $300 at the Q2 call. European curtailments, estimated at 20-25% of capacity, support the cost curve through spring 2027. With Q4 about 70% sold and Q1 2027 much less committed, LSB has meaningful exposure to price moves in either direction.
The Leidos trial, now underway with prior damages claims above $300 million, is an unpriced optionality item, and the outcome is uncertain.
Investor expectations had already been recovering before the release. Earnings Whispers sentiment moved from -0.22 at the prior report to +0.05, a meaningful improvement from negative to slightly positive. The stock has not followed. Shares closed at $10.37 the day before the report, down 2.7% from the $10.66 open after the July release and about 11.8% below the 200-day moving average of $11.76. The Earnings Whispers trend readings are mixed, with momentum positive while price and AVWAP trends remain negative. The market has been treating LSB with more caution than the improving operating data alone would justify.
The bottom line is that LSB produced a high-quality operational quarter in most respects. Record production, a profitable shift toward industrial AN, sharply higher EBITDA and real deleveraging all support a credible earnings-improvement story. However, roughly half the cost benefit is non-recurring, the AN premium has a visible expiration date, ammonia pricing has cooled, and the CCS earnings stream has been pushed further out. Whether the stock can close its gap to the 200-day average likely depends on evidence that the operational-improvement run-rate and the buybacks can offset those fading tailwinds in 2027.
Read our earnings preview for LSB Industries, Inc.: https://www.earningswhispers.com/article/LXU/20953
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| Oct-28 | |
| Oct-28 | |
| Oct-27 | |
| Oct-20 | |
| Oct-14 | |
| Oct-13 | |
| Sep-01 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-15 | |
| May-19 | |
| Apr-29 | |
| Apr-29 |
