T1 Energy Must Prove Its Margin Story Can Outrun A Stalled G2 Financing
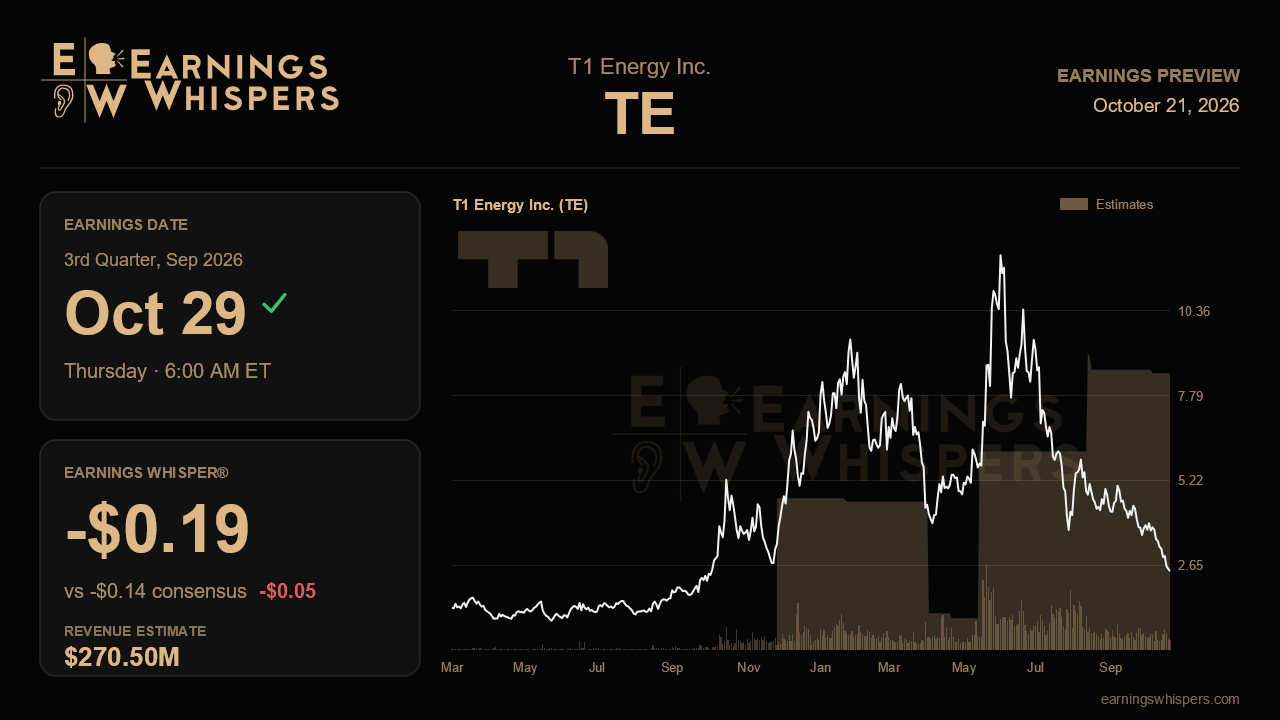
T1 Energy heads into its third-quarter report with a striking disconnect. Operationally, the summer call was the most confident the company has sounded in a year: margins up, factory output climbing, a second big integrated offtake signed and a long-awaited tariff regime finally on the books. The stock has gone the other way, losing more than half its value since that report. At $2.47, shares sit just above their post-earnings low of $2.40 and far beneath the 200-day moving average near $6.28. The market is clearly pricing something the income statement has not yet shown, and the October 29 release before the open is the company's chance to show whether that fear is warranted.
The Street is looking for a loss of 14 cents a share on revenue of about $270.5 million. That revenue figure implies roughly 8% sequential growth from the prior quarter's $250.1 million and about 28.5% growth from a year ago, a solid but not heroic step. The per-share loss estimate matches last quarter's result, while the year-over-year comparison looks dramatic only because the year-ago loss was 85 cents. The whisper number sits lower, at a 19-cent loss, which signals that the more skeptical crowd expects a wider shortfall than consensus. That gives T1 a somewhat lower bar on the bottom line, though not one investors should treat as easily cleared.
There is a good reason for that caution. Last quarter's adjusted EBITDA of $10.7 million leaned on a one-time $24 million tariff refund, meaning underlying profitability was modest at best. Without that cushion, this quarter has to stand on genuine gains in gross margin and cost control. Gross margin climbed to 19.5% in the second quarter from 17% in the first and roughly 7% exiting last year, and management argued that the new Section 232 framework, with its minimum import price and added tariff, is lifting merchant pricing above levels the company previously locked in. Another step up in margin would validate that argument. A flat or slipping margin, especially with SG&A having jumped about $20 million on legal and financing costs, would suggest the tariff windfall is slower to reach the bottom line than promised.
Volume is the second test. The G1 module plant produced 935 megawatts in the second quarter, with monthly output rising, and management firmed its full-year language to the high end of a 3.1 to 4.2 gigawatt range. Reaching that high end requires continued sequential gains, so third-quarter production that holds near or below the prior quarter would quietly undercut the guidance upgrade. Contract coverage of roughly 3 gigawatts for 2026, including the new 641 megawatt Clearway deal, provides demand visibility, so any shortfall would point to execution rather than end markets.
The bigger overhang is the balance sheet. The comprehensive debt package for the G2 cell fab in Austin has slipped repeatedly from its original April target, forcing a $120 million convertible in July on top of a $176 million convert in April. First cell production has already moved from late 2026 to the first quarter of 2027, and remaining Phase 1 capex stands near $250 million, up from about $225 million the quarter before. Sentiment has swung from solidly bullish before the last report to mildly bearish now, a shift that tracks closely with these financing worries rather than with operating results.
That makes the financing update the hinge of this report. A closed, debt-heavy G2 package with the Q1 2027 timeline intact would go a long way toward reconciling the improving operations with a battered share price. Another quarter of delay, more equity-linked bridges or further capex creep would tell investors the dilution risk embedded in the stock is real, regardless of how good the margins look.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-21 | |
| Sep-25 | |
| Aug-27 | |
| Aug-27 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-03 | |
| Aug-03 | |
| Jul-30 |
