T1 Energy Needs A Closed G2 Financing More Than A Narrower Loss
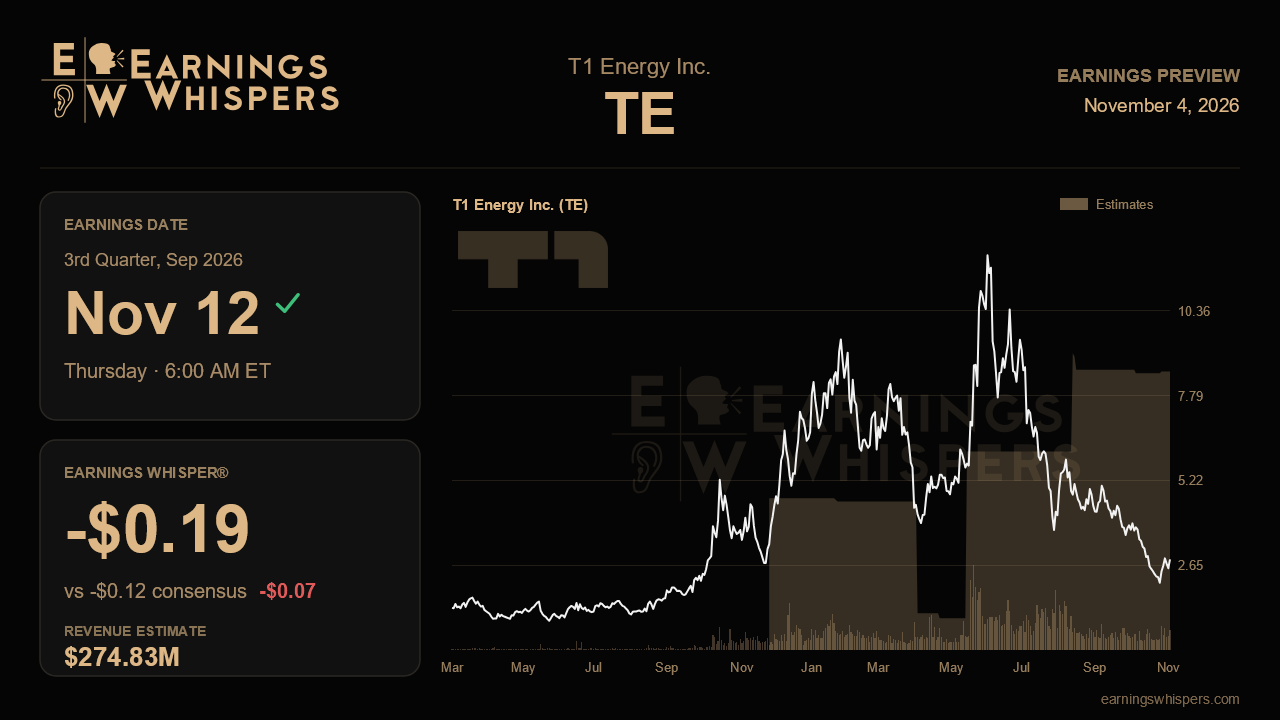
T1 Energy heads into its third-quarter report with a business that looked healthier on its last call and a stock that has been cut in half since. That gap is the story. Margins widened, a second integrated offtake landed and the Section 232 trade action that management had long called a one-way option finally arrived. Yet the shares have fallen about 50% since mid-August, trailing the S&P 500 by nearly 48 percentage points. The market is clearly pricing financing and execution risk, not operating momentum, and this report is the company's chance to address that.
The Street expects a loss of $0.12 a share on revenue of about $274.8 million. That would be roughly a 31% revenue gain from $210.5 million a year ago and a sharply smaller loss than the $0.85 per share lost in the same quarter of 2025. Sequentially, it implies about 10% revenue growth from the second quarter's $250.1 million and a slightly narrower loss than last quarter's $0.14. The whisper number of a $0.19 loss sits meaningfully below consensus. That suggests the more skeptical crowd is bracing for another quarter of heavy financing, legal and advisory costs. It also means a print near consensus could clear a lower informal bar.
The operating checklist begins with the G1 module plant. Management said full-year 2026 output and sales should land near the high end of its 3.1 to 4.2 gigawatt range, which is firmer language than in earlier calls. Second-quarter production was 935 megawatts, the second-highest quarter on record. Getting to the top of that range likely requires second-half volumes well above that pace, so third-quarter output is the first real test of the promise. Gross margin is the other key measure. It reached 19.5% last quarter, up from 17% in the first quarter and roughly 7% exiting 2025. Holding or extending that level would support management's view that post-232 merchant pricing is running above previously contracted levels. A pullback would raise questions about whether the tariff benefit is reaching the income statement. Investors should also look past headline adjusted EBITDA. Last quarter's $10.7 million included a one-time $24 million tariff refund, so underlying profitability was thinner than it appeared.
The bigger questions concern the balance sheet. The comprehensive, debt-heavy financing for the G2 Austin cell fab was targeted for April and then the second quarter, and it was still open at the August call. In the meantime, T1 has leaned on a $176 million convertible in April and a $120 million convertible bridge in July. Remaining Phase 1 capital spending was put at about $250 million, up from $225 million the prior quarter. First-cell production at G2 has already slipped to the first quarter of 2027. A closed financing, together with confirmation that the 2027 start date is holding, would validate the improved tone of the last call. Another delay, another dilutive bridge or a further slide in the cell schedule would reinforce the market's skepticism. Updates on the Evervolt TopCon IP deal, the T1 NRI services business, the Norway data center asset and Commerce's case-by-case tariff-offset rulings matter too, but they are secondary.
Sentiment has turned with the price. Readings have shifted from solidly bullish before the last report to mildly bearish now. At $2.83, the stock sits less than half of its 200-day moving average of $6.04 and in the lower part of its post-earnings range of $2.08 to $5.86. That range is a steep step down from the prior quarter's $3.50 to $12.49.
The central issue is straightforward. T1 has shown it can run G1 profitably. What it has not shown is that it can fund G2 without repeatedly diluting shareholders. If the release pairs steady margins and rising volumes with real financing progress, the improving narrative survives. If it does not, strong module economics may again be overshadowed by the cost of building the cell fab.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Oct-30 | |
| Oct-27 | |
| Oct-22 | |
| Oct-21 | |
| Sep-25 | |
| Aug-27 | |
| Aug-27 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 |
