Wabash Needs Its Backlog Rebound To Show Up In Margins As Trailer Recovery Faces Proof Test
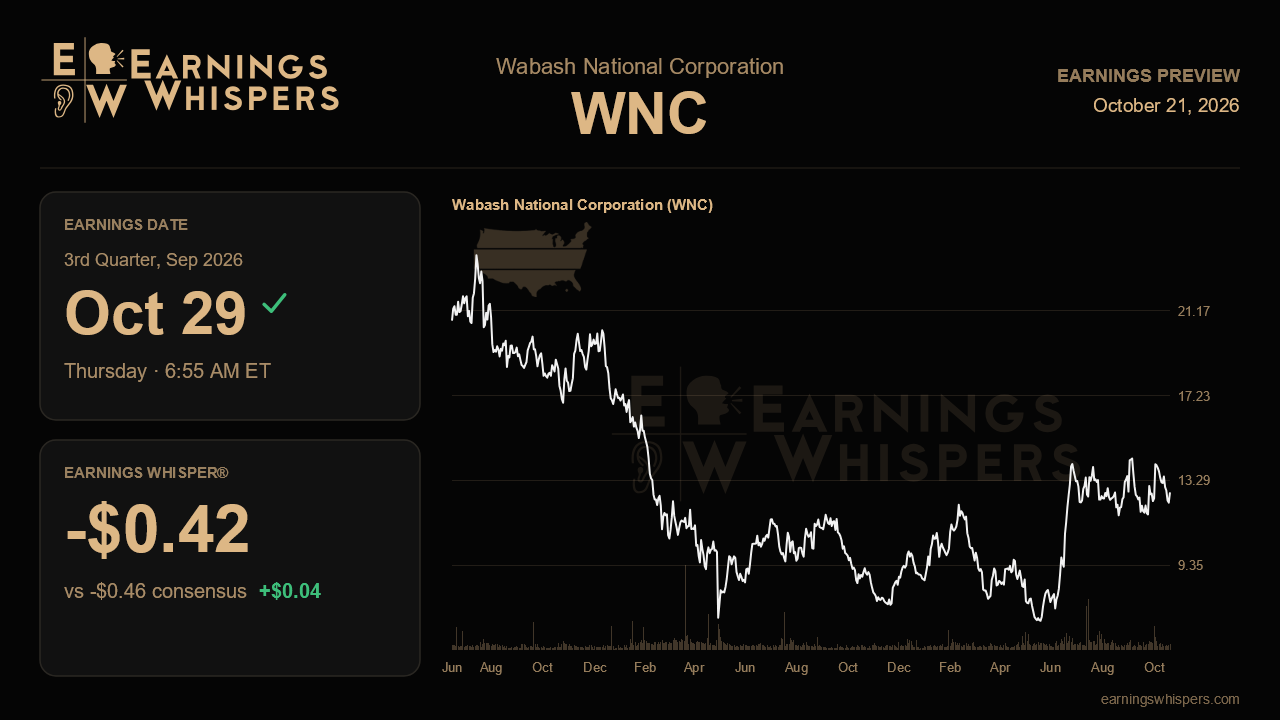
Wabash National heads into its third-quarter report with a story that has improved faster than its stock price. Last quarter the trailer maker posted its first positive gross margin in several quarters, grew backlog in a second quarter for the first time in company history, and opened its 2027 order book months ahead of schedule at customers' request. Since then the shares have slipped 5.7% while the S&P 500 gained 3.9%. This report is a test of whether that recovery narrative is turning into financial results, or whether the market's hesitation is justified while the company remains unprofitable.
The Street expects a loss of $0.46 per share, a modest improvement from the $0.51 loss a year ago and the $0.53 loss last quarter. That figure sits just below the midpoint of management's guidance for a loss of $0.40 to $0.50. The whisper number of a $0.42 loss points to the better half of that range. The gap is small, but it suggests investors want more than a guidance-midpoint result. On the top line, management guided to $440 million to $460 million, up from $417.2 million last quarter and well ahead of the $381.6 million reported a year ago. Landing inside that range would mean revenue growth in the mid-to-high teens, a meaningful change for a company coming off a deep cyclical trough.
Margins are where the quarter gets more complicated. Management said material margin would be roughly flat versus the second quarter, because older, lower-priced backlog is still working through the plants. The 200 to 300 basis points of pricing benefit it described are not expected to arrive until the fourth quarter and mostly in 2027. As a result, gross margin holding near last quarter's 4.1% on higher volume would support the plan, and any expansion would come from operating leverage rather than price. Adjusted EBITDA improved from a $38 million loss in the first quarter to a $9 million loss in the second. Because management reaffirmed positive EBITDA for the second half, the third quarter should come in near breakeven or better. A result still well below zero would raise doubts about that commitment, especially with fourth-quarter revenue expected to decline seasonally.
Backlog may matter even more than the earnings line. The order book rose from about $800 million at its low to $956 million, and management described the shift as deferred demand becoming committed orders. With the 2027 book open and dry-van quotes reportedly between $39,500 and $41,500, investors should look for backlog to hold or rise. They should also look for evidence that the new orders carry that higher pricing. Management has tied those prices to a return to roughly $150 million to $170 million of EBITDA in a replacement-level 2027, so details on order mix and price realization will help investors judge that target. Updates on truck bodies, which lag dry vans by six to nine months, and on the preliminary antidumping and countervailing duty rulings against Chinese competitors will also shape the outlook.
The balance sheet is another item to check. Management said a $300 million revolver refinancing was nearly complete, which would address a September 2026 maturity. A $150 million convertible note funds the working-capital build. Confirmation that the refinancing closed, along with free cash flow that stays near or above last quarter's slightly positive level, would ease concerns about leverage and dilution.
Sentiment has become much more bullish than before the last report, even as the shares have lagged. At $12.73, the stock trades well above its 200-day moving average of $10.73 but in the middle of its $11.41 to $14.55 post-earnings range. That range follows a rally from below $7 the prior quarter. The central question is whether Wabash can show that higher volume and a growing, better-priced backlog are moving it toward positive earnings on schedule. Signs of progress could reopen the upper end of the range, while another quarter of deferred margin gains would test investors' patience.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-06 | |
| Oct-05 | |
| Sep-24 | |
| Aug-19 | |
| Aug-04 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-22 | |
| Jul-16 | |
| Jul-15 | |
| Jul-14 | |
| Jul-09 | |
| Jul-01 |
