FMC's Third-Quarter Sales Guidance Collapse Puts Full-Year Plan And Balance Sheet On Trial
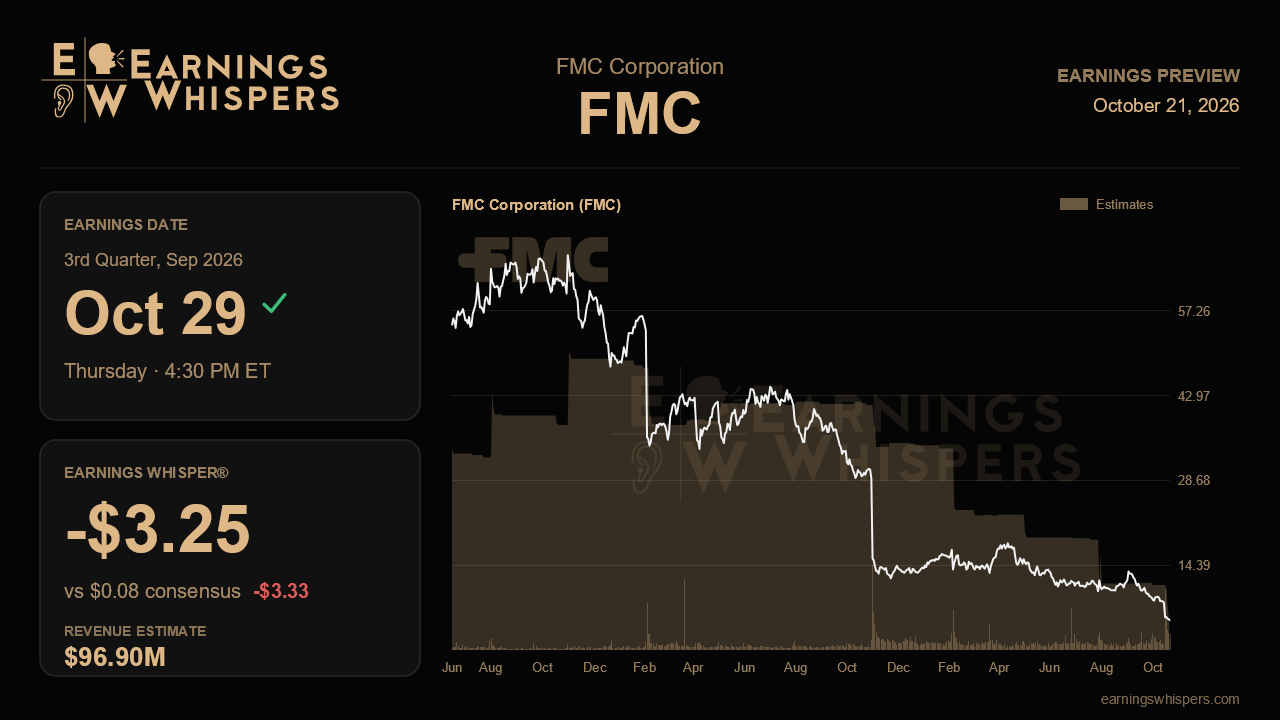
Three months ago, FMC asked investors to accept a weak third quarter in exchange for a strong fourth. Since then, the third quarter has gone from weak to nearly empty. The company now expects third-quarter revenue of just $65 million to $125 million, down from a prior range of $840 million to $900 million. That is not a trim; it is a near-total erasure of a quarter's sales. When FMC reports after the close on October 29, the numbers themselves will matter less than whether management can explain what happened and whether the rest of the recovery story still stands.
Wall Street has fully absorbed the new range. Consensus calls for revenue of about $96.9 million, almost exactly the midpoint of guidance and roughly 82% below the year-ago quarter. The EPS consensus of $0.08 compares with $0.89 a year ago, a 91% decline. The more telling figure is the whisper number of a $3.25 loss per share, far below the published consensus. That gap suggests many investors expect charges, write-downs or other items that analysts' formal estimates have not yet captured, so a headline loss would not by itself shock the market. The bar for the reported figures is low; the bar for credibility is high.
The second-quarter call is the essential reference point. Back then, management cut full-year guidance for the first time after two calls of reaffirmation, lowering sales to $3.5 billion to $3.7 billion, EBITDA to $620 million to $680 million and adjusted EPS to $1.19 to $1.49. The explanations were pricing that now looked set to fall by a mid-to-high single digit percentage and soft North American volumes, where rice plantings hit multi-decade lows, insect pressure was light, growers traded down to generics and Pyroxasulfone lost IP protection. Those headwinds alone do not obviously account for a near-billion-dollar swing in quarterly sales. The release needs to clarify whether the revenue shortfall reflects demand, channel or accounting decisions, and whether that revenue is lost or merely shifted into later periods.
That distinction bears directly on the fourth quarter, which management had guided to roughly 4% sales growth and 5% EBITDA growth, with a planned EBITDA jump of about $165 million from the third quarter. Even before the latest cut, that ramp depended on Brazil direct sales and new active ingredients that were not fully backed by orders. If FMC reaffirms the fourth-quarter growth target and a full-year framework anywhere near the July ranges, the narrative of a trough year followed by 2027 recovery survives. A withdrawn outlook, or a fourth quarter that also slides, would argue the problems run deeper than pricing.
The balance sheet is the other pressure point. Management had touted a de-risked capital structure: the $1.2 billion secured bond deal, maturities pushed to 2029, the $200 million Corteva prepayment for Rimasoxafen, and a target of roughly $2.6 billion in year-end net debt, near 4 times leverage. With third-quarter earnings largely gone, that leverage math worsens unless asset sales and the sale-leaseback land as planned. Free cash flow guidance of $75 million to $225 million, already flattered by the one-time Corteva payment, deserves scrutiny, as does the board's review of the roughly $50 million annual dividend, which now looks harder to defend.
The market has delivered its verdict in advance. Shares have fallen about 49% since the last report, trailing the S&P 500 by nearly 54 points, and at $5.31 trade far below the 200-day average of $12.86 and not far above the post-earnings low of $4.85. Oddly, sentiment is less bearish than before the last report, perhaps reflecting a sense that the worst is priced in. Whether that holds depends on one question: can FMC show that this quarter's collapse is a contained reset rather than evidence that its fourth-quarter rebound and 2027 growth bridge are slipping out of reach?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Sep-28 | |
| Sep-23 | |
| Sep-21 | |
| Sep-17 | |
| Aug-28 | |
| Aug-27 | |
| Jul-30 |
