FMC's $672 Million Channel Reset Buries The Quarter, And The Underlying Miss, Second Q4 Cut And Thin Covenant Headroom Matter More
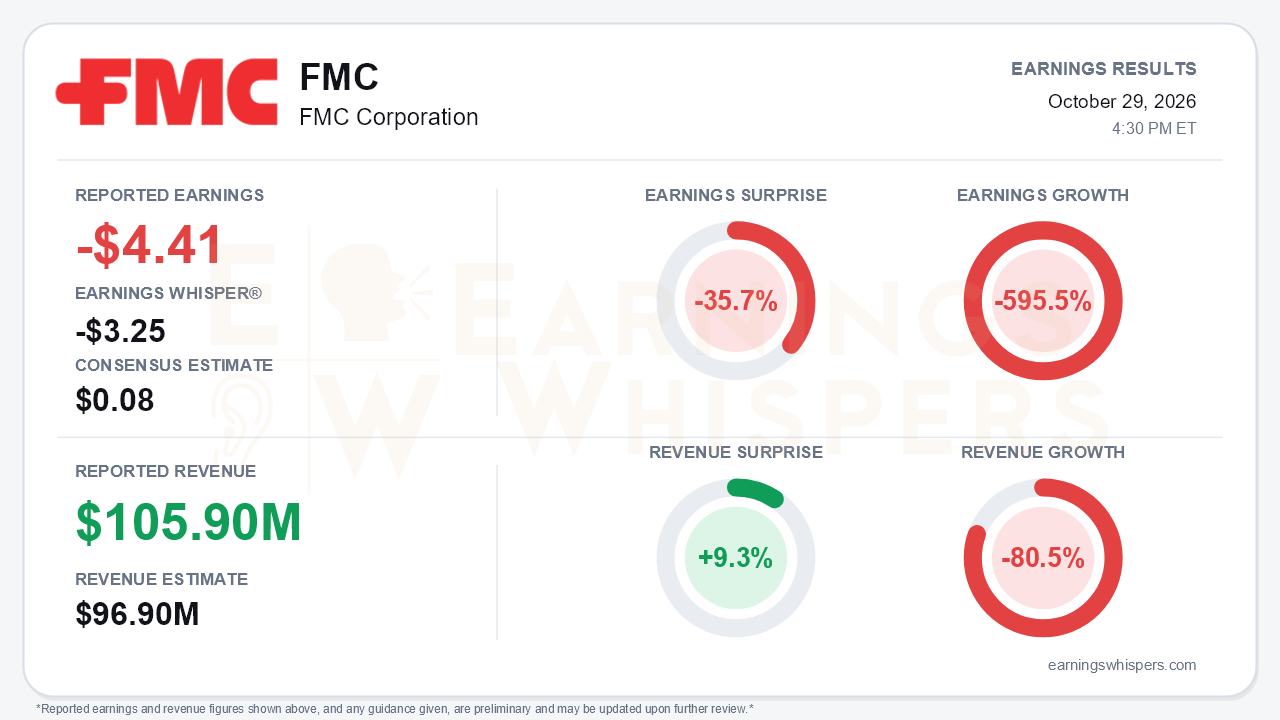
FMC Corporation reported an adjusted loss of $4.41 per share for the third quarter, against a consensus estimate of a $0.08 profit and an Earnings Whisper number of a $3.25 loss. The company missed expectations by 35.7%, and earnings fell 595.5% year over year, a swing from an adjusted profit of $0.89 a year ago. Revenue of $105.9 million beat the $96.9 million consensus by 9.3% but fell 80.5% from the prior year. That beat is an artifact of how the commercial-action charges were modeled rather than a sign of strength. The central takeaway is that the previously announced $639 million revenue hit and $672 million Adjusted EBITDA hit from FMC's channel reset were expected. What investors were not positioned for was that the business beneath those charges also missed, and the outlook was cut again.
The quality of the quarter deserves scrutiny on two levels. Excluding India and the commercial actions, revenue was $745 million, down 22%. Volume fell 21% as channel customers sharply cut replenishment orders in the final weeks of September, and price fell 2%. That result fell well short of the $840 million to $900 million management had guided on the prior call. Underlying Adjusted EBITDA of $113 million also missed the $120 million to $140 million guide.
The GAAP picture is far worse. The net loss of $2.07 billion, or $15.54 per share, included an $809 million valuation allowance against historical deferred tax assets and a $288 million non-cash impairment tied to Rynaxypyr intangibles. After those write-downs, FMC stockholders' equity was slightly negative at quarter-end, at negative $19.4 million. The one genuinely positive line was cash. Free cash flow of negative $18 million improved $214 million year over year on working capital.
Management's explanation of the reset is coherent:
- About $500 million of the charge closes out the old North America gross-price-and-rebate model and marks channel inventory down toward expected net pricing. The company says this carries no change to its forward cash obligation.
- The remaining roughly $175 million reprices high-priced products held by channel customers in Brazil, the U.S., Canada and Argentina. Management says this component will reduce future cash collections over the coming quarters.
- Implementation is still ongoing and is expected to take three quarters.
The guidance trajectory is what undermines confidence. Fourth-quarter Adjusted EBITDA guidance fell to $210 million to $230 million from an implied $275 million to $315 million. Adjusted EPS guidance fell to $0.56 to $0.70 from $1.09 to $1.33. Full-year free cash flow went from a positive $75 million to $225 million to a range of negative $350 million to negative $150 million. Restructuring cash spend rose for a third straight time, to $180 million. Year-end net debt is now guided to about $3.1 billion, up from roughly $2.6 billion. The tone shifted from the prior call's 'worst is behind us' to an acknowledgment that confidence 'can only be rebuilt through execution.' The CEO also conceded that further cost cuts cannot fix performance and that R&D partnership models may be needed.
The forward story rests on a preliminary framework of $650 million to $730 million of EBITDA in 2027 and $760 million to $840 million in 2028. Management pointed to several supports:
- roughly 50% growth from new actives in 2027;
- Fluindapyr registrations pending in six new countries;
- potential Isoflex approvals in Europe;
- footprint savings;
- early customer feedback on the new pricing model that management called 'very positive.'
Balance-sheet support is arriving as well. Tessenderlo's $403 million equity investment closed in September, giving it a roughly 20% stake and a board seat. The India sale is targeted for a December 1 close, and a Delaware sale-leaseback is planned by year-end. Bears have legitimate ammunition, however. The 2027 range replaces earlier 'mid-teens growth' language with a wider band starting from a lower base. Leverage of about 6.1x sits against a 6.75x covenant limit that is reinstated December 31, and interest coverage is 2.3x against a 2.0x minimum. Additional risks include possible El Niño demand effects, a high-single-digit fourth-quarter price decline, Middle East cost inflation, and weaker diamide partner sales in 2027.
Investor sentiment, already negative, became meaningfully more so, sliding from -0.45 before the prior report to -0.61. The stock has been treated accordingly. At $4.75, shares are down 54.8% from the $10.50 open following the July report and sit 62% below the 200-day moving average of $12.51. Price and AVWAP trend readings remain negative. The market has spent the quarter repricing FMC from a recovery story to a balance-sheet story.
The bottom line is that the headline charge was largely telegraphed, but the quarter still broke the investment setup. Underlying sales and EBITDA missed guidance, fourth-quarter guidance was cut for a second time, free cash flow swung deeply negative, and covenant headroom is thin. The new pricing model, the Tessenderlo capital and the 2027–28 framework give FMC a credible path. That path now depends on flawless execution through a destocked channel, and management's own credibility is the asset most in need of repair.
Read our earnings preview for FMC Corporation: https://www.earningswhispers.com/article/FMC/21194
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-29 | |
| Oct-29 | |
| Oct-21 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Oct-15 | |
| Sep-28 | |
| Sep-23 | |
| Sep-21 | |
| Sep-17 |
