Civista Reaches Its EPS Run-Rate Target Early On Margin Expansion, But A Sub-Debt Reset And Souring Sentiment Complicate The Setup
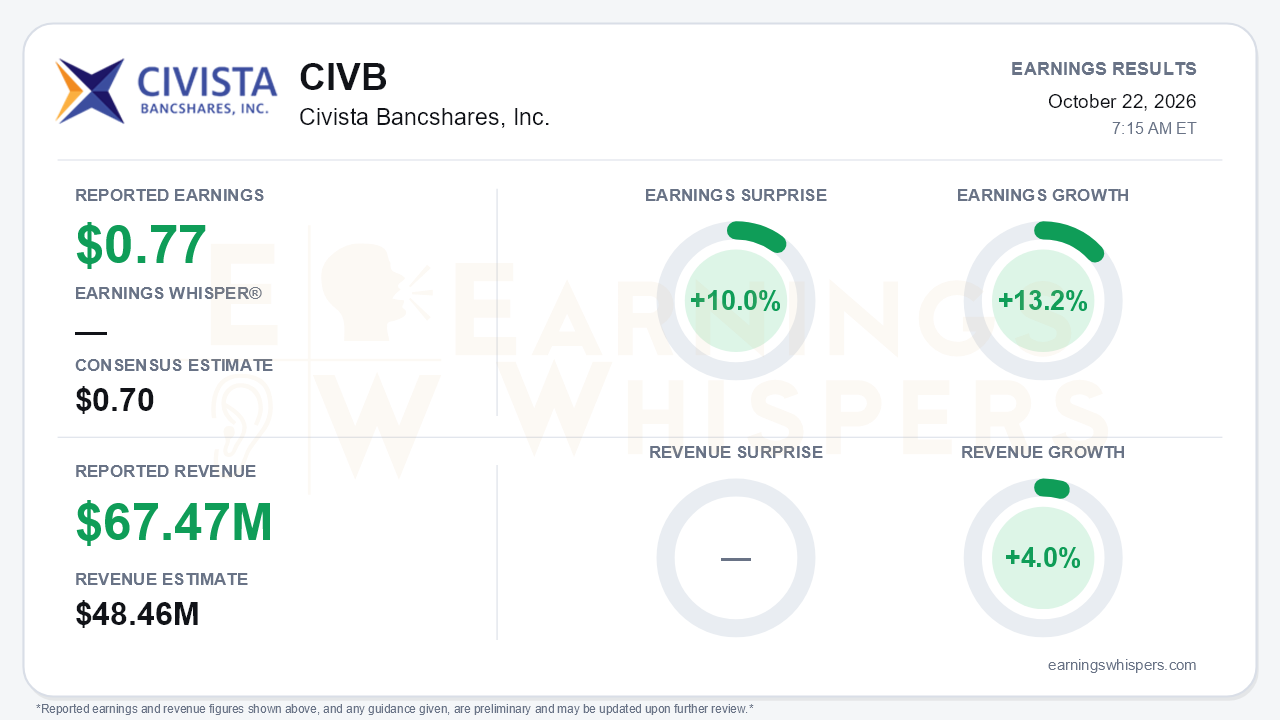
Civista Bancshares delivered a clean, broad-based beat in the third quarter. Diluted EPS of $0.77 topped the $0.70 consensus by 10.0% and grew 13.2% year over year. Revenue of $67.47 million exceeded the $48.46 million consensus by 39.2% and rose 4.0%. The more important development is sequential. EPS stepped up from $0.69 in the second quarter and $0.72 in the first, putting Civista at the roughly $0.75 quarterly run-rate that management had earlier said would arrive only in late 2026 or early 2027. Net income rose 25.5% to $16.0 million. EPS grew about half as fast because the November 2025 Farmers Savings Bank merger lifted weighted shares from 18.8 million to 20.8 million. That dilution remains part of the story for shareholders.
The quality of the beat holds up well. Two one-time items roughly cancelled out. A $1.8 million insurance gain from the December branch fire was largely offset by a $1.6 million loss on securities sold in a balance sheet repositioning. A higher effective tax rate, 19.1% versus 16.7% in the second quarter, worked against the bottom line. The real engine was spread income:
- **Net interest income** rose 14.1% year over year to $39.4 million.
- **Net interest margin** widened for a fourth straight quarter to 3.93%, up from 3.89%, 3.85%, and 3.69% over the prior three quarters.
- **Interest expense** fell as short-term FHLB borrowings were cut roughly in half from a year ago and brokered deposits declined another $25 million.
- **Pre-provision net revenue** climbed to $21.1 million from $18.9 million in the second quarter.
- **Non-interest expense** slipped to $28.0 million, driving the efficiency ratio down to 55.3% from 58.2%.
Credit was quiet. Net charge-offs were just $0.1 million, helped by $1.56 million of recoveries, and non-performing assets fell to $27.6 million.
The call reinforced that the improvement is operational, not cosmetic. Loan growth accelerated to a 4.7% annualized pace ($38 million), compared with 3.1% in the second quarter and a contraction in the first. Early payoffs eased to $47 million from $68 million and $83 million in the two prior quarters. Core deposits grew $44 million, led by $30.3 million of non-interest-bearing balances, reversing a $44 million total deposit decline in the second quarter. Undrawn construction lines have risen every quarter, from $162 million at year-end to $268 million, which points to funding demand still ahead. Management raised its targets across the board:
- **Fourth-quarter margin:** now guided within 1-2 basis points of the third quarter, versus a prior outlook of the upper 3.80s.
- **Fee income:** guided to $9.0-$9.5 million.
- **Expenses:** guidance cut to $28.7-$29.5 million from $29.6-$30 million.
Buybacks also resumed, with 82,075 shares repurchased this year. The new CEO, Chuck Parcher, used his first call to signal continuity, and management noted that M&A dialogue may be reviving.
Bears still have legitimate ammunition, and the most concrete is the margin itself. On December 1, Civista's subordinated debt resets from a 3.25% fixed rate to three-month SOFR plus 219 basis points. Management estimates this will cost about 2 basis points of margin in the fourth quarter and 5-6 basis points per quarter once the full impact lands in early 2027. That headwind partly offsets two tailwinds: roughly $270 million of commercial loans repricing over the next year, and a slightly asset-sensitive balance sheet that gains 1-2 basis points per rate hike. Rising rates carry their own risks, including deposit betas (management assumes about 50%) and pressure on residential demand, the portfolio's fastest-growing category. Part of the expense beat was timing, with investments in staff, marketing, and IT shifting into the fourth quarter and 2027. The rate backdrop is also eroding capital marks. Unrealized securities losses widened to $59.9 million from $34.9 million last quarter. As a result, tangible book value per share slipped to $19.87 from $20.43 and the tangible common equity ratio dipped to 9.88% from 10.23%, even though both remain above year-end levels.
The market setup is more complicated than the surprise implies. Investor sentiment deteriorated meaningfully heading into the report, falling from -0.20 to -0.41. Shares closed at $26.75 before the release, 2.7% below the open following the July report. The stock had given back much of its run to a 52-week high of $29.97 in early August and was trading closer to its October 1 low of $25.91. It remained about 4.4% above its 200-day moving average of $25.62, so the pullback had not broken the longer-term trend. The Earnings Whispers trend signals were mixed, with momentum positive while AVWAP remained negative.
The bottom line is that Civista posted the kind of quarter skeptics were not positioned for. Margin, loan growth, core deposits, fees, and efficiency all improved, and earnings reached management's run-rate target ahead of schedule. The open question is durability. The sub-debt reset, rate-driven funding and capital pressure, and deferred expenses will test whether the 3.93% margin and $0.77 EPS represent a new floor or a near-term peak.
Read our earnings preview for Civista Bancshares, Inc.: https://www.earningswhispers.com/article/CIVB/20509
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| Oct-22 | |
| Oct-22 | |
| Oct-22 | |
| Oct-21 | |
| Oct-01 | |
| Sep-15 | |
| Aug-31 | |
| Jul-24 | |
| Jul-23 | |
| Jul-23 | |
| Jul-23 | |
| Jul-22 | |
| Jun-15 | |
| Apr-24 | |
| Apr-22 |
