BioMarin Must Prove Voxzogo Can Hold Ground As Amicus Lifts Revenue Toward $1 Billion
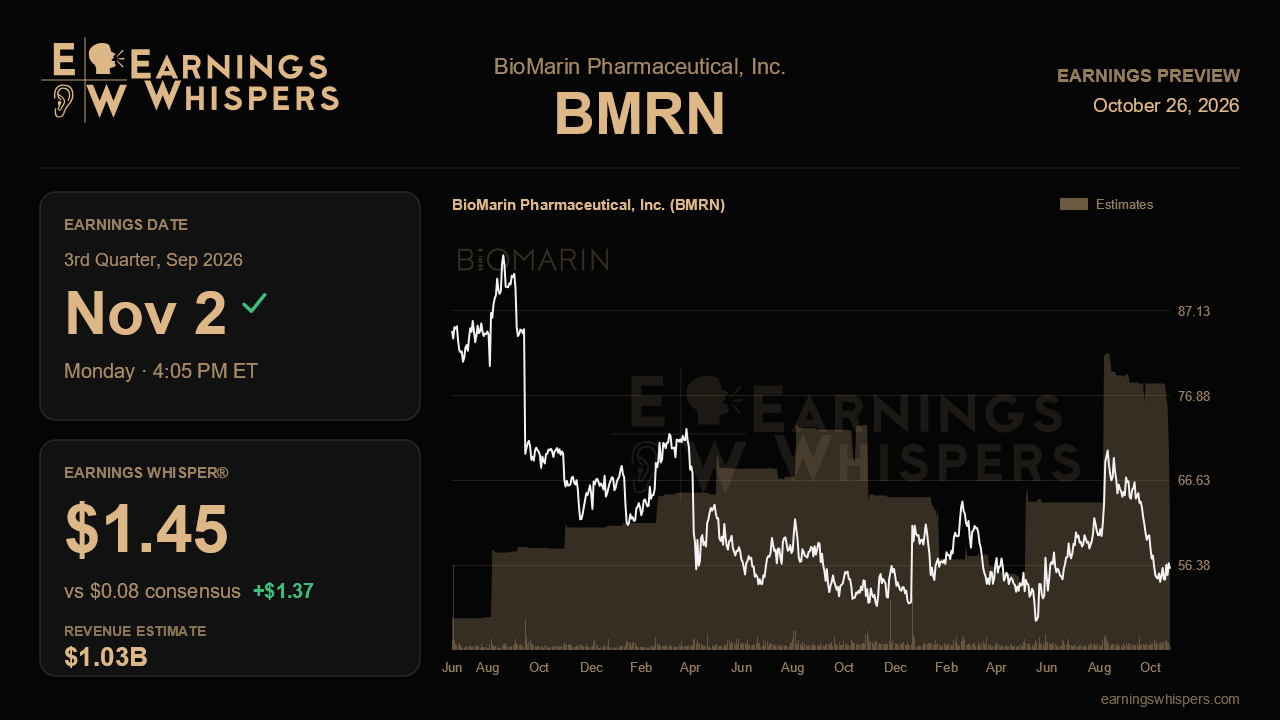
BioMarin heads into its third-quarter report with a striking disconnect between its business and its stock. Last quarter management delivered its most confident call in a year, raising full-year revenue and earnings guidance, lifting peak sales targets for the newly acquired Amicus drugs and putting a number on cost synergies for the first time. The market has since knocked the shares down 13.7%, trailing the S&P 500 by more than 12 percentage points. The November 2 report, due after the close, is a test of which side has it right.
On the top line, analysts expect about $1.03 billion in revenue, up roughly 33% from $776.1 million a year ago and a modest step up from the $989.7 million posted in the second quarter. Much of that year-over-year jump reflects a full quarter of Amicus's Galafold and Pombiliti/Opfolda, so the more telling comparison is sequential. The earnings picture is muddier. The published consensus of $0.08 per share looks out of step with both the company's full-year non-GAAP guidance of $4.90 to $5.10 and last quarter's result of $1.11, while the whisper number of $1.45 sits far above it. That gap suggests the real bar is much closer to the whisper, and a quarter that merely clears $0.08 would not impress anyone tracking the full-year math.
Guidance frames the setup. Full-year consensus of $4.91 in EPS sits right at the bottom of management's range, and the $3.86 billion revenue estimate actually falls below the $3.875 billion low end. In other words, analysts are not fully buying the raised outlook. A clean quarter that keeps BioMarin on track for the middle of its ranges would close that skepticism gap; another raise would be a meaningful statement given the Street's caution.
Voxzogo is the swing factor. Management lifted its guidance so the low end now exceeds $1 billion, but it also disclosed that roughly 10% of US patients had switched to a competing therapy approved in February. That was the first time switching showed up as a reported fact rather than a forecast. The key question is whether the switching rate has stabilized or kept climbing through the summer, and whether international growth and new patient starts are offsetting US losses. Any update on the hypochondriplasia filing, submitted unusually quickly, and the reception of the full Phase 3 data matters too, because label expansion is the clearest path to defending the franchise. The ITC litigation, with a final decision due in December, remains an overhang management will likely be asked to address.
The Amicus integration is the second pillar. Pro forma Galafold grew about 10% and Pombiliti/Opfolda more than 65% last quarter, supporting combined peak targets of $2.6 billion. Sustaining that pace, along with early evidence on the roughly $220 million synergy plan and the faster deleveraging timeline, would validate the bull case. Investors should also watch how much the roughly $50 million in quarterly acquisition interest expense continues to weigh on earnings alongside higher operating spending. Palynziq, up 27% last quarter with fresh adolescent approvals, offers another source of upside in the metabolic business.
Sentiment has warmed from decidedly bearish before the last report to roughly neutral now, yet the stock sits near the bottom of its post-earnings range of $53.90 to $70.98 and below its 200-day moving average of $58.48. That combination implies modest expectations and room for relief if the numbers hold up. Ultimately, the report hinges on Voxzogo: if switching has leveled off and the franchise stays on its billion-dollar trajectory while Amicus keeps delivering, the narrative of accelerating growth remains intact. If US erosion is deepening, the recent selloff may prove justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It was generated automatically, with the help of AI, from Earnings Whispers and company data, and checked by Earnings Whispers before publication.
Mentioned In This Article
Latest News
| 4 hours | |
| 7 hours | |
| Oct-09 | |
| Oct-09 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-14 | |
| Sep-11 | |
| Sep-09 | |
| Sep-04 | |
| Sep-02 | |
| Sep-02 | |
| Sep-01 | |
| Aug-31 |
