BioMarin Tops Depressed EPS Bar And Crosses $1 Billion, But A Guidance Cut And Softer VOXZOGO Trends Complicate The Story
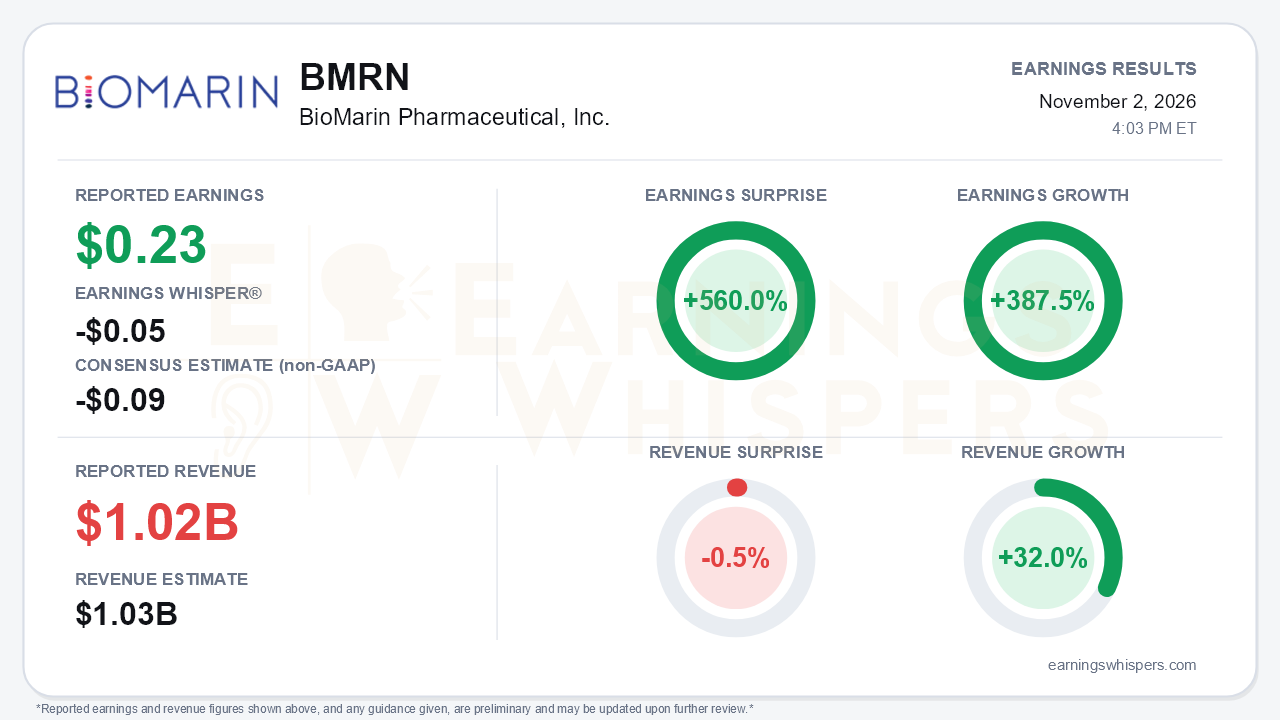
BioMarin's third quarter delivered a headline beat on a low bar, and the forward picture weakened. The rare-disease company reported non-GAAP earnings of $0.23 per share, against a consensus estimate of -$0.09 and an Earnings Whisper number of -$0.05. That is a 560.0% surprise, and earnings grew 387.5% from a year ago. Revenue reached $1.025 billion, up 32.0% and above $1 billion in a quarter for the first time, though it missed the $1.03 billion consensus by 0.5%. That is the central tension. The quarter beat on earnings and set a revenue milestone, yet management lowered full-year revenue guidance for the first time in 2026, and VOXZOGO, its main growth franchise, slowed again.
The quality of the beat deserves scrutiny. Consensus was negative because Wall Street expected a large acquired IPR&D charge from the Alesta deal. BioMarin does not exclude that charge from non-GAAP results, and it came to $288 million. The upside therefore reflects how the charge flowed through relative to expectations as much as operating strength. On a GAAP basis, the net loss widened to $123 million, or $0.63 per share, from $31 million. Several Amicus-related costs drove the wider loss:
- intangible amortization of $99 million, up from $5 million;
- interest expense of $56 million, up from under $3 million;
- inventory step-up amortization;
- integration costs.
Non-GAAP operating margin improved to 13.4% from 2.8%, though both quarters carried IPR&D hits. The balance sheet now holds roughly $4.2 billion of debt against $736 million in cash, versus $597 million of debt and about $2 billion in cash and investments at year-end. That is a materially more leveraged company.
The Amicus acquisition drove most of the growth. Revenue growth accelerated from roughly 20% in the second quarter, and Metabolic Conditions revenue jumped 44% to $744 million. GALAFOLD contributed $152 million, with patients up 13%. POMBILITI + OPFOLDA added $49 million, with patients up 69%, helped by competitor Pompe supply constraints in Europe that management expects to keep benefiting the product into 2027. Integration is clearly going well:
- Cost synergies are running ahead of schedule, with the 2028 target maintained.
- Management said the deal is now accretive within nine months and tracking accretive for calendar 2026.
- On the second-quarter call, management had called the deal modestly dilutive.
Beneath the acquired growth, the legacy picture is less impressive:
- NAGLAZYME fell 11% on order timing.
- PALYNZIQ grew only 2% after an order-timing benefit in the second quarter.
- VIMIZIM's 18% gain was also order-timing driven.
VOXZOGO is where bears have legitimate ammunition. Revenue grew 12% to $245 million, down from 14% growth in the second quarter and 26% for fiscal 2025, partly because a large international order slipped into the fourth quarter. Children treated rose 17%, so underlying demand is still expanding. However, U.S. retention fell to about 85% at the end of September from about 90% at the end of July, and management said it will stop disclosing U.S. switching metrics. Investors will reasonably read that as a less transparent window into competitive pressure. That pressure could intensify if Ascendis' weekly CNP, which has a positive CHMP opinion, wins EU approval.
The guidance cut spans both revenue and EPS:
- Total revenue guidance fell to $3.8–$3.9 billion from $3.875–$3.925 billion.
- The main driver is a single international customer deferring about $70 million of expected fourth-quarter orders into early 2027.
- Rising liquidity strain tied to the prolonged Middle East conflict adds to the pressure.
- A little more than half of the deferral is VOXZOGO, putting the $1 billion-plus franchise target at risk.
- Non-GAAP EPS guidance fell to $2.80–$3.10 from $4.90–$5.10.
The EPS reset looks dramatic, but most of it reflects about $1.55 per share from Alesta and $0.32 from the BMN 450 Fabry license. Management indicated that, excluding those deals and the revenue cut, the midpoint would be roughly unchanged. The bigger operational worry is that delayed orders could push follow-on orders later into 2027. On the positive side, the catalyst calendar is full:
- a POMBILITI adolescent PDUFA in January;
- VOXZOGO's full-approval PDUFA for achondroplasia on February 28, 2027;
- a hypochondroplasia PDUFA on May 30, 2027;
- Ascendis royalty income;
- BMN 440 data in 2027.
Investor sentiment entering the report remained negative but improved meaningfully, rising from -0.36 to -0.15. The stock has not shared that improvement. At $58.51, shares were down 9.7% since the opening after the August report. They sat essentially on the 200-day moving average of $58.42 and 17.6% below the $70.98 52-week high set on August 12. That leaves the stock in the lower half of its inter-earnings range, 8.6% above the October low. The trend readings are split. Sequential growth and momentum are positive, while price and AVWAP trends remain negative.
The bottom line is that BioMarin's Amicus bet is working faster than promised, and the pipeline and regulatory calendar are stronger than they were a year ago. The headline EPS beat, however, says more about charge-laden expectations than about core acceleration. Lower revenue guidance, order-timing fragility in international markets, slowing VOXZOGO growth and reduced disclosure on U.S. retention give skeptics a credible case. Whether the deferred orders actually land in early 2027 will be the near-term test.
Read our earnings preview for BioMarin Pharmaceutical, Inc.: https://www.earningswhispers.com/article/BMRN/21370
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-30 | |
| Oct-26 | |
| Oct-26 | |
| Oct-09 | |
| Oct-09 | |
| Oct-05 | |
| Oct-02 | |
| Oct-01 | |
| Sep-14 | |
| Sep-11 | |
| Sep-09 |
