Clarivate Must Show Its Promised Second-Half Recurring Revenue Inflection Is Real
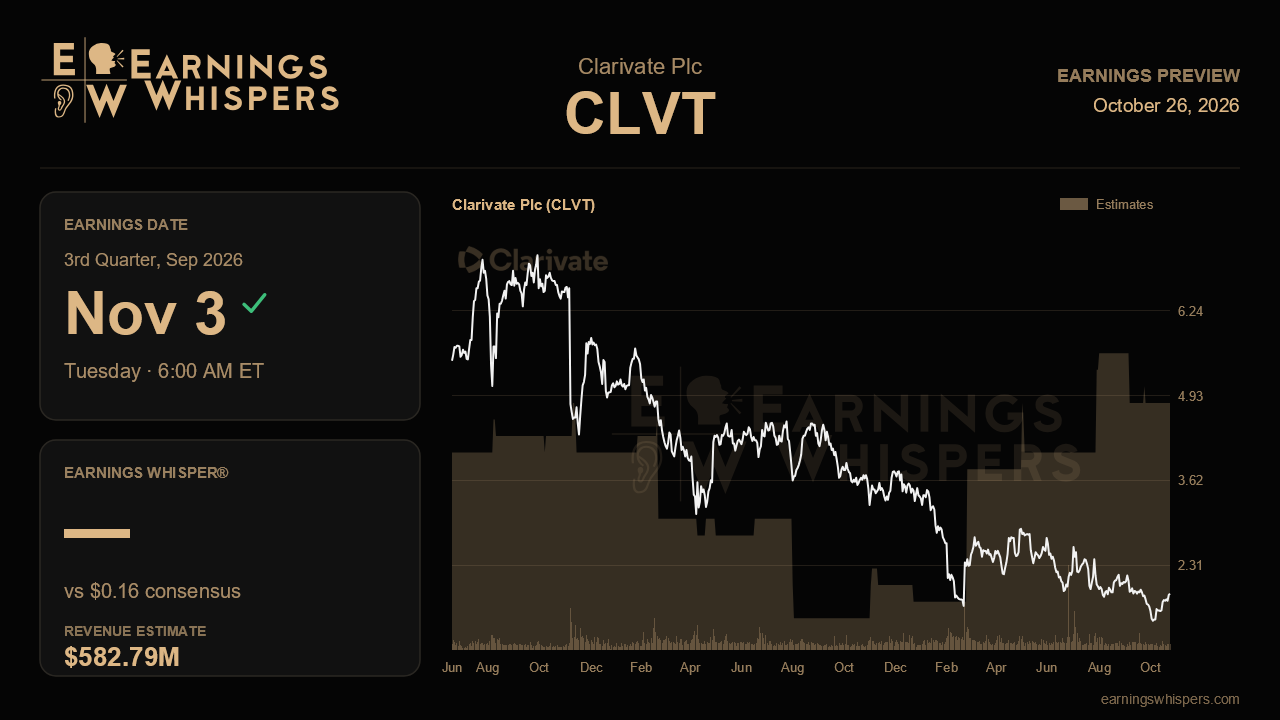
Clarivate spent its last earnings call telling a more confident story. It is shrinking into a cleaner, more recurring business, investing in agentic AI products and expanding margins, and it says organic growth should accelerate in the second half. The September quarter is where that story gets its first real test. Management has promised a second-half pickup in recurring revenue and a return to growth in its intellectual property segment. A stock trading below $2 cannot afford to have those promises slip another quarter.
The Street expects earnings of $0.16 per share on revenue of about $582.8 million. That EPS figure matches both the prior quarter and the year-ago period. Revenue would fall roughly 6.5% from $623.1 million a year ago and come in slightly below June's $587.3 million. Much of that contraction reflects disposals, currency and weak transactional sales rather than a collapse in the subscription base, but the headline decline still matters. For the full year, management reaffirmed non-GAAP EPS of $0.70 to $0.80 on revenue of $2.30 billion to $2.42 billion. Consensus of $0.76 and $2.36 billion sits comfortably inside both ranges, with EPS a touch above the midpoint. The wrinkle is that management already steered revenue to just below the midpoint, near $2.35 billion. Analysts are therefore leaning slightly more optimistic than the company's own framing, which leaves little room for further transactional softness.
The operating scorecard comes down to three questions. First, does organic annual contract value growth start climbing from the 1.5% posted in June? That was a slight dip from 1.6% in the first quarter, and full-year guidance now points to only the lower half of a 2% to 3% range. Another flat or weaker print would undercut the acceleration narrative. Second, does IP recurring revenue move from flat to positive? New segment president Simon Webster, the former CPA Global chief, is the face of that turnaround, and a quarter of genuine growth would lend it credibility quickly. Third, is the Academia and Government business still tracking toward roughly 3% ACV growth? Early traction for Web of Science Research Intelligence would help answer that. The product had 77 paying customers and a multi-million-dollar pipeline at last count, so a rising customer tally or commentary on the newer Nexus Connect and IP1 launches would suggest the AI products are generating revenue rather than just headlines.
Margins are the most reliable part of the story. Adjusted EBITDA margin topped 42% in the second quarter, and the full-year target of about 43% implies the back half must run even higher. Hitting that would confirm that cost discipline is offsetting soft top-line trends. Cash is less comfortable. Free cash flow guidance has slid to the low end, roughly flat year over year, because of about $70 million in one-time transaction and restructuring costs. Any further erosion would worry holders of a leveraged balance sheet. Progress toward closing the Life Sciences and Health sale to Alteros by year end matters for the same reason, since the proceeds underpin roughly $900 million of planned debt reduction. This will also be the first report under new CFO Michael Easton, so the clarity of his guidance commentary carries extra weight.
Sentiment has cooled into the print, with bearish readings rising to 58.6% from 52.0% last quarter. Yet the stock has gained 5.1% since the last report, beating the S&P 500 by about 2.4 percentage points. At $1.87, shares sit in the middle of a $1.42 to $2.26 post-earnings range. They remain well below the 200-day moving average of $2.27 and far beneath the prior quarter's range, which ran as high as $3.05. In other words, a modest rebound has not repaired much of the earlier damage.
Ultimately, this report hinges on whether recurring growth visibly turns higher. Reaffirmed guidance and fatter margins would keep the thesis alive. But if ACV stalls near 1.5% and IP stays flat, investors are likely to treat the accelerating-growth language as aspiration rather than evidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-22 | |
| Oct-15 | |
| Oct-06 | |
| Sep-24 | |
| Sep-23 | |
| Sep-22 | |
| Sep-17 | |
| Sep-17 | |
| Aug-06 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-29 | |
| Jul-20 |
